Archived - Evaluation of the Canadian Centre for Justice Statistics Program - Information Sheet

Evaluation of the Canadian Centre for Justice Statistics Program - Information Sheet
Description - Evaluation of the Canadian Centre for Justice Statistics Program - Information Sheet

1: About the evaluation

Statistics Canada evaluates programs like the Canadian Centre for Justice Statistics (CCJS) to assess their relevance and performance. The evaluation of the CCJS covered the period from 2011/2012 to 2015/2016 and program expenditures of $40.7 million.

The evaluation was conducted in accordance with the Treasury Board of Canada Policy on Evaluation (2009). It provides a neutral assessment of the relevance and performance of the CCJS based on evidence gathered through a document and literature review, a survey of users, key informant interviews, and other data.

A yellow ribbon crosses the page with the text: "Police Line Do Not Cross"

A magnifying glass appears on the yellow ribbon with the text: $40.7 M in program expenditures

2: About the CCJS

The mandate of the CCJS is to provide information to the justice community and the public on the nature and extent of crime and on the administration of criminal and civil justice in Canada.

CCJS survey topics include

  • police-reported crime
  • homicide
  • police administration
  • adult and youth criminal courts and corrections
  • expenditures and personnel for civil courts and adult corrections.

3: We learned that the CCJS…

  • aligns with the Government of Canada's current priorities and is responsive to the ongoing needs of a wide range of users.
  • provides statistical information that is accessible, accurate, interpretable, relevant and released according to established schedules.
  • remains committed to offering quality crime and justice outputs that meet overall needs and priorities.
  • offers accessibility and quality of customized information and support services to its stakeholders, who are satisfied with them.

4: Satisfaction with CCJS

Statistics Canada uses six dimensions to evaluate the quality and fitness for use of its statistical information. CCJS survey respondents were asked to rate their level of satisfaction with these quality dimensions.

  • CCJS overall: 94% of satisfied respondents
  • Data accuracy: 94% of satisfied respondents
  • Data coherence: 94% of satisfied respondents
  • Data interpretability: 88% of satisfied respondents
  • Data accessibility (website): 88% of satisfied respondents
  • Data timeliness: 74% of satisfied respondents
  • Relevance - coverage of issues of most importance: 49% of respondents who said completely or to a great extent and 47% of respondents who said to some extent
  • Relevance - responsiveness to emerging trends: 20% of respondents who said completely or to a great extent and 64% of respondents who said to some extent

A yellow ribbon crosses the page with the text: "Police Line Do Not Cross"

5: How can we improve the CCJS?

  • Explore the possibility of producing more timely indicators in key selected areas with input from partners to provide earlier indications of issues and trends.
  • Establish an appropriate mechanism through which academia can be part of formal consultations.
  • Explore communication vehicles to promote awareness of CCJS data among the research and academia community.

Management agreed with the evaluation recommendations and proposed an action plan to address them.

Source: Evaluation of the Canadian Centre for Justice Statistics Program (2011/2012 to 2015/2016).

Concordance: Harmonized Commodity Description and Coding System (HS) 2012 - Harmonized Commodity Description and Coding System (HS) 2017 at the 6-digit level - HS6 (Exports- Imports)

As part of the 2017 World Customs Organization (WCO) amendments, a number of codes have been terminated and recoded.

Updates at the 6-digit level are made every 5 years by the WCO, in order to reflect international standards and trade patterns.

This concordance table lists the terminated HS codes alongside with the new 2017 recoded HS codes at the 6-digit level.

These changes will take effect January 1st, 2017.

Concordance: Harmonized Commodity Description and Coding System (HS) 2012 - Harmonized Commodity Description and Coding System (HS) 2017 at the 6-digit level - SH6 (Export- Import)
2012 Terminated HS Codes2017 HS Codes
0301.930301.93
0301.990301.93
0301.990301.99
0302.110302.11
0302.110302.99
0302.130302.13
0302.130302.99
0302.140302.14
0302.140302.99
0302.190302.19
0302.190302.99
0302.210302.21
0302.210302.99
0302.220302.22
0302.220302.99
0302.230302.23
0302.230302.99
0302.240302.24
0302.240302.99
0302.290302.29
0302.290302.99
0302.310302.31
0302.310302.99
0302.320302.32
0302.320302.99
0302.330302.33
0302.330302.99
0302.340302.34
0302.340302.99
0302.350302.35
0302.350302.99
0302.360302.36
0302.360302.99
0302.390302.39
0302.390302.99
0302.410302.41
0302.410302.99
0302.420302.42
0302.420302.99
0302.430302.43
0302.430302.99
0302.440302.44
0302.440302.99
0302.450302.45
0302.450302.99
0302.460302.46
0302.460302.99
0302.470302.47
0302.470302.99
0302.510302.51
0302.510302.99
0302.520302.52
0302.520302.99
0302.530302.53
0302.530302.99
0302.540302.54
0302.540302.99
0302.550302.55
0302.550302.99
0302.560302.56
0302.560302.99
0302.590302.59
0302.590302.99
0302.710302.71
0302.710302.99
0302.720302.72
0302.720302.99
0302.730302.73
0302.730302.99
0302.740302.74
0302.740302.99
0302.790302.79
0302.790302.99
0302.810302.81
0302.810302.92
0302.810302.99
0302.820302.82
0302.820302.99
0302.830302.83
0302.830302.99
0302.840302.84
0302.840302.99
0302.850302.85
0302.850302.99
0302.890302.49
0302.890302.73
0302.890302.89
0302.890302.99
0302.900302.91
0303.110303.11
0303.110303.99
0303.120303.12
0303.120303.99
0303.130303.13
0303.130303.99
0303.140303.14
0303.140303.99
0303.190303.19
0303.190303.99
0303.230303.23
0303.230303.99
0303.240303.24
0303.240303.99
0303.250303.25
0303.250303.99
0303.260303.26
0303.260303.99
0303.290303.29
0303.290303.99
0303.310303.31
0303.310303.99
0303.320303.32
0303.320303.99
0303.330303.33
0303.330303.99
0303.340303.34
0303.340303.99
0303.390303.39
0303.390303.99
0303.410303.41
0303.410303.99
0303.420303.42
0303.420303.99
0303.430303.43
0303.430303.99
0303.440303.44
0303.440303.99
0303.450303.45
0303.450303.99
0303.460303.46
0303.460303.99
0303.490303.49
0303.490303.99
0303.510303.51
0303.510303.99
0303.530303.53
0303.530303.99
0303.540303.54
0303.540303.99
0303.550303.55
0303.550303.99
0303.560303.56
0303.560303.99
0303.570303.57
0303.570303.99
0303.630303.63
0303.630303.99
0303.640303.64
0303.640303.99
0303.650303.65
0303.650303.99
0303.660303.66
0303.660303.99
0303.670303.67
0303.670303.99
0303.680303.68
0303.680303.99
0303.690303.69
0303.690303.99
0303.810303.81
0303.810303.92
0303.810303.99
0303.820303.82
0303.820303.99
0303.830303.83
0303.830303.99
0303.840303.84
0303.840303.99
0303.890303.25
0303.890303.59
0303.890303.89
0303.890303.99
0303.900303.91
0304.390304.39
0304.490304.39
0304.490304.47
0304.490304.48
0304.490304.49
0304.510304.51
0304.590304.51
0304.590304.56
0304.590304.57
0304.590304.59
0304.690304.69
0304.890304.69
0304.890304.88
0304.890304.89
0304.930304.93
0304.990304.93
0304.990304.96
0304.990304.97
0304.990304.99
0305.310305.31
0305.390305.31
0305.390305.39
0305.440305.44
0305.490305.44
0305.490305.49
0305.590305.52
0305.590305.53
0305.590305.54
0305.590305.59
0305.640305.64
0305.690305.64
0305.690305.69
0306.210306.31
0306.210306.91
0306.220306.32
0306.220306.92
0306.240306.33
0306.240306.93
0306.250306.34
0306.250306.94
0306.260306.35
0306.260306.95
0306.270306.36
0306.270306.95
0306.290306.39
0306.290306.99
0307.190307.12
0307.190307.19
0307.290307.22
0307.290307.29
0307.390307.32
0307.390307.39
0307.410307.42
0307.490307.43
0307.490307.49
0307.590307.52
0307.590307.59
0307.790307.72
0307.790307.79
0307.890307.83
0307.890307.87
0307.910307.42
0307.910307.82
0307.910307.91
0307.990307.43
0307.990307.49
0307.990307.84
0307.990307.88
0307.990307.92
0307.990307.99
0308.190308.12
0308.190308.19
0308.290308.22
0308.290308.29
0805.200805.21
0805.200805.22
0805.200805.29
1211.201211.20
1211.301211.30
1211.401211.40
1211.901211.50
1211.901211.90
1302.191302.14
1302.191302.19
1404.901211.20
1404.901211.30
1404.901211.40
1404.901211.50
1404.901211.90
1404.901404.90
1604.191604.18
1604.191604.19
1605.541605.54
1605.591605.54
1605.591605.59
2202.902202.91
2202.902202.99
2204.292204.22
2204.292204.29
2811.192811.12
2811.192811.19
2812.102812.11
2812.102812.12
2812.102812.13
2812.102812.14
2812.102812.15
2812.102812.16
2812.102812.17
2812.102812.19
2848.002853.90
2853.002853.10
2853.002853.90
2903.892903.83
2903.892903.89
2903.992903.93
2903.992903.94
2903.992903.99
2904.902904.31
2904.902904.32
2904.902904.33
2904.902904.34
2904.902904.35
2904.902904.36
2904.902904.91
2904.902904.99
2910.902910.50
2910.902910.90
2914.692914.62
2914.692914.69
2914.702914.71
2914.702914.79
2918.192918.17
2918.192918.19
2920.902920.21
2920.902920.22
2920.902920.23
2920.902920.24
2920.902920.29
2920.902920.30
2920.902920.90
2921.192921.12
2921.192921.13
2921.192921.14
2921.192921.19
2922.132922.15
2922.132922.19
2922.192922.16
2922.192922.17
2922.192922.18
2922.192922.19
2923.902923.30
2923.902923.40
2923.902923.90
2924.292924.25
2924.292924.29
2926.902926.40
2926.902926.90
2930.502930.80
2930.902930.60
2930.902930.70
2930.902930.80
2930.902930.90
2931.902931.31
2931.902931.32
2931.902931.33
2931.902931.34
2931.902931.35
2931.902931.36
2931.902931.37
2931.902931.38
2931.902931.39
2931.902931.90
2932.192932.14
2932.192932.19
2933.392933.39
2933.392939.80
2933.592933.59
2933.592939.80
2933.792933.79
2933.792939.80
2933.992933.92
2933.992933.99
2933.992939.80
2934.992934.99
2934.992939.80
2935.002935.10
2935.002935.20
2935.002935.30
2935.002935.40
2935.002935.50
2935.002935.90
2939.912939.71
2939.992939.79
3002.103002.11
3002.103002.12
3002.103002.13
3002.103002.14
3002.103002.15
3002.103002.19
3003.403003.41
3003.403003.42
3003.403003.43
3003.403003.49
3003.903003.60
3003.903003.90
3004.403004.41
3004.403004.42
3004.403004.43
3004.403004.49
3004.903004.60
3004.903004.90
3103.103103.11
3103.103103.19
3705.103705.00
3705.903705.00
3808.503808.52
3808.503808.59
3808.913808.59
3808.913808.61
3808.913808.62
3808.913808.69
3808.913808.91
3808.923808.59
3808.923808.92
3808.933808.59
3808.933808.93
3808.943808.59
3808.943808.94
3808.993808.59
3808.993808.99
3812.303812.31
3812.303812.39
3824.903824.84
3824.903824.85
3824.903824.86
3824.903824.87
3824.903824.88
3824.903824.91
3824.903824.99
3901.903901.40
3901.903901.90
3907.603907.61
3907.603907.69
3909.303909.31
3909.303909.39
3926.903926.90
3926.909620.00
4011.614011.70
4011.624011.80
4011.634011.80
4011.694011.90
4011.924011.70
4011.934011.80
4011.944011.80
4011.994011.90
4401.104401.11
4401.104401.12
4401.394401.39
4401.394401.40
4403.104403.11
4403.104403.12
4403.204403.21
4403.204403.22
4403.204403.23
4403.204403.24
4403.204403.25
4403.204403.26
4403.494403.49
4403.924403.93
4403.924403.94
4403.994403.49
4403.994403.95
4403.994403.96
4403.994403.97
4403.994403.98
4403.994403.99
4406.104406.11
4406.104406.12
4406.904406.91
4406.904406.92
4407.104407.11
4407.104407.12
4407.104407.19
4407.294407.29
4407.994407.29
4407.994407.96
4407.994407.97
4407.994407.99
4408.394408.39
4408.904408.39
4408.904408.90
4409.294409.22
4409.294409.29
4412.314412.31
4412.324412.31
4412.324412.33
4412.324412.34
4412.394412.31
4412.394412.39
4418.714418.73
4418.714418.74
4418.724418.73
4418.724418.75
4418.794418.73
4418.794418.79
4418.904418.91
4418.904418.99
4419.004419.11
4419.004419.12
4419.004419.19
4419.004419.90
4421.904421.91
4421.904421.99
4421.909620.00
4801.004801.00
4802.614801.00
4802.614802.61
4802.624801.00
4802.624802.62
5402.595402.53
5402.595402.59
5402.695402.63
5402.695402.69
5502.005502.10
5502.005502.90
5506.905506.40
5506.905506.90
5704.905704.20
5704.905704.90
6005.316005.35
6005.316005.36
6005.326005.35
6005.326005.37
6005.336005.35
6005.336005.38
6005.346005.35
6005.346005.39
6304.916304.20
6304.916304.91
6815.106815.10
6815.109620.00
6907.106907.21
6907.106907.22
6907.106907.23
6907.106907.30
6907.106907.40
6907.906907.21
6907.906907.22
6907.906907.23
6907.906907.30
6907.906907.40
6908.106907.21
6908.106907.22
6908.106907.23
6908.106907.30
6908.106907.40
6908.906907.21
6908.906907.22
6908.906907.23
6908.906907.30
6908.906907.40
7326.907326.90
7326.909620.00
7616.997616.99
7616.999620.00
8409.918409.91
8409.918542.31
8409.918542.32
8409.918542.39
8415.908415.90
8415.908542.31
8415.908542.32
8415.908542.39
8418.998418.99
8418.998542.31
8418.998542.32
8418.998542.39
8419.908419.90
8419.908542.31
8419.908542.32
8419.908542.39
8424.818424.41
8424.818424.49
8424.818424.82
8432.308432.31
8432.308432.39
8432.408432.41
8432.408432.42
8450.908450.90
8450.908542.31
8450.908542.32
8450.908542.39
8456.108456.11
8456.108456.12
8456.908456.40
8456.908456.50
8456.908456.90
8459.408459.41
8459.408459.49
8460.118460.12
8460.198460.19
8460.218460.22
8460.218460.23
8460.218460.24
8460.298460.29
8460.908460.12
8460.908460.19
8460.908460.22
8460.908460.23
8460.908460.24
8460.908460.29
8460.908460.90
8465.918465.20
8465.918465.91
8465.928465.20
8465.928465.92
8465.938465.20
8465.938465.93
8465.948465.20
8465.948465.94
8465.958465.20
8465.958465.95
8465.968465.20
8465.968465.96
8465.998465.20
8465.998465.99
8469.008472.90
8472.908472.90
8473.108473.40
8473.108542.31
8473.108542.32
8473.108542.39
8473.218473.21
8473.218542.31
8473.218542.32
8473.218542.39
8473.298473.29
8473.298542.31
8473.298542.32
8473.298542.39
8473.308473.30
8473.308542.31
8473.308542.32
8473.308542.39
8473.309620.00
8473.408473.40
8473.408542.31
8473.408542.32
8473.408542.39
8473.508473.40
8473.508473.50
8473.508542.31
8473.508542.32
8473.508542.39
8504.908504.90
8504.908542.31
8504.908542.32
8504.908542.39
8508.708508.70
8508.708542.31
8508.708542.32
8508.708542.39
8509.908509.90
8509.908542.31
8509.908542.32
8509.908542.39
8516.908516.90
8516.908542.31
8516.908542.32
8516.908542.39
8517.708517.70
8517.708542.31
8517.708542.32
8517.708542.39
8518.908518.90
8518.908542.31
8518.908542.32
8518.908542.39
8522.908522.90
8522.908542.31
8522.908542.32
8522.908542.39
8522.909620.00
8528.418528.42
8528.518528.52
8528.618528.62
8529.108529.10
8529.108542.31
8529.108542.32
8529.108542.33
8529.108542.39
8529.908529.90
8529.908542.31
8529.908542.32
8529.908542.39
8536.508536.50
8536.508542.31
8536.508542.39
8536.908536.90
8536.908542.31
8536.908542.39
8542.318542.31
8542.328542.32
8542.338542.33
8542.398542.39
8543.708539.50
8543.708542.31
8543.708542.33
8543.708542.39
8543.708543.70
8543.908542.31
8543.908542.32
8543.908542.39
8543.908543.90
8701.908701.91
8701.908701.92
8701.908701.93
8701.908701.94
8701.908701.95
8702.108702.10
8702.108702.20
8702.908702.20
8702.908702.30
8702.908702.40
8702.908702.90
8703.218703.21
8703.218703.40
8703.218703.60
8703.228703.22
8703.228703.40
8703.228703.60
8703.238703.23
8703.238703.40
8703.238703.60
8703.248703.24
8703.248703.40
8703.248703.60
8703.318703.31
8703.318703.50
8703.318703.70
8703.328703.32
8703.328703.50
8703.328703.70
8703.338703.33
8703.338703.50
8703.338703.70
8703.908703.80
8703.908703.90
8711.908711.60
8711.908711.90
9005.909005.90
9005.909620.00
9006.109006.59
9006.599006.59
9006.919006.91
9006.919620.00
9007.919007.91
9007.919620.00
9015.909015.90
9015.909620.00
9025.198542.31
9025.198542.39
9025.199025.19
9025.808542.31
9025.808542.39
9025.809025.80
9025.908542.31
9025.908542.32
9025.908542.39
9025.909025.90
9026.108542.31
9026.108542.39
9026.109026.10
9026.208542.31
9026.208542.39
9026.209026.20
9026.808542.31
9026.808542.39
9026.809026.80
9026.908542.31
9026.908542.32
9026.908542.39
9026.909026.90
9027.108542.31
9027.108542.39
9027.109027.10
9027.208542.31
9027.208542.39
9027.209027.20
9027.308542.31
9027.308542.39
9027.309027.30
9027.508542.31
9027.508542.39
9027.509027.50
9027.808542.31
9027.808542.39
9027.809027.80
9027.908542.31
9027.908542.32
9027.908542.39
9027.909027.90
9030.338542.31
9030.338542.39
9030.339030.33
9030.898542.31
9030.898542.39
9030.899030.89
9030.908542.31
9030.908542.32
9030.908542.39
9030.909030.90
9031.808542.31
9031.808542.39
9031.809031.80
9032.908542.31
9032.908542.32
9032.908542.39
9032.909032.90
9033.008542.31
9033.008542.32
9033.008542.39
9033.009033.00
9033.009620.00
9401.519401.52
9401.519401.53
9403.819403.82
9403.819403.83
9406.009406.10
9406.009406.90
9504.308542.31
9504.308542.32
9504.308542.39
9504.309504.30
9504.508542.31
9504.508542.32
9504.508542.39
9504.509504.50

Survey on Research Activities and Commercialization of Intellectual Property in Higher Education (SRACIPHE)

The Questionnaire

1. Verify or provide the business or organization’s legal and operating name, and correct information if needed.

Will be pre-filled
Note: Legal name should only be modified to correct a spelling error or typo.
Note: Press the help button (?) for additional information.

  • Legal name
  • Operating name (if applicable)

2. Verify or provide the contact information for the designated contact person for the business or organization, and correct information if needed.

Will be pre-filled
Note: The designated contact person is the person who should receive this questionnaire. The designated contact person may not always be the one who actually completes the questionnaire.

  • First name
  • Last name
  • Title
  • Preferred language of communication
    • English
    • French
  • Mailing address (number and street)
  • City
  • Province, territory or state
  • Postal code 
  • Country
  • Email address
    Example: user@exemple.gov.ca
  • Telephone number (including area code)
    Example: 123-123-1234
  • Extension number (if applicable)
  • Fax number (including area code)
    Example: 123-123-1234

3. Verify or provide the current operational status of the business or organization identified by the legal and operating name above.

  • Operational
  • Not currently operational (e.g., temporarily or permanently closed, change of ownership)
    • Why is this business or organization not currently operational?
      • Seasonal operations
        • When did this business or organization close for the season?
          Date: YYYY-MM-DD
        • When does this business or organization expect to resume operations?
          Date: YYYY-MM-DD
      • Ceased operations
        • When did this business or organization cease operations?
          Date: YYYY-MM-DD
        • Why did this business or organization cease operations?
          • Bankruptcy
          • Liquidation
          • Dissolution
          • Other – specify the other reasons why the operations ceased
      • Sold operations
        • When was this business or organization sold?
          Date: YYYY-MM-DD
        • What is the legal name of the resulting or continuing business or organization?
      • Amalgamated with other businesses or organizations
        • When did this business or organization amalgamate?
          Date: YYYY-MM-DD
        • What is the legal name of the resulting or continuing business or organization?
        • What are the legal names of the other amalgamated businesses or organizations?
      • Temporarily inactive but expected to reopen
        • When did this business or organization become temporarily inactive
          Date: YYYY-MM-DD
        • When does this business or organization expect to resume operations?
          Date: YYYY-MM-DD
        • Why is this business or organization temporarily inactive?
      • No longer operating because of other reasons
        • When was this business or organization cease operations?
          Date: YYYY-MM-DD
        • Why did the business or organization cease operations?

4. Verify or provide the current main activity of the business or organization identified by the legal and operating name above.

Note: The described activity was assigned using the North American Industry Classification System (NAICS). 
Note: Press the help button (?) for additional information, including a detailed description of the activity with example activities and any applicable exclusions.

  • This is the main activity
  • This is not the main activity
    Provide a Brief but precise description of this business or organization’s main activity
    e.g., breakfast cereal manufacturing, shoe store, software development

5. Was this business or organization’s main activity ever classified as prefilled NAICS will appear here?

  • Yes
    When did the main activity change?
    Date: YYYY-MM-DD
  • No

6. Search and select the industry activity classification that best corresponds to this business or organization’s main activity. 

How to search:

  1. Filter the search results by first selecting the business or organization’s activity sector. 
  2. Enter keywords or a brief description that best describe the business or organization’s main activity. 
  3. Press the Search button to search the database for an industry activity classification that best matches the keywords or description you provided.
  4. Select an industry activity classification from the list.

Select this business or organization’s activity sector (optional)

Enter keywords or a brief description, then press the Search button

Display example of NAICS search:

Select this business or organization’s activity sector (optional)

Enter keywords or a brief description, then press the Search button

Select an industry activity classification

  • Furniture stores (442110)
  •  Used merchandise stores (453310)
  •  Window treatment stores (442291)
  •  All other home furnishings stores (442298)
  •  Print and picture frame stores (442292)
  •  Floor covering stores (442210)
  •  Hardware stores (444130)
  •  None of the above - a Statistics Canada representative may call you to confirm the main activity.

Module 1: Institutional Information (Question 7 to Question 11)

7. Which of the following best describes this institution?

Select one.

  1. This institution is a university, college, CEGEP or polytechnic that conducted $500,000 or more in research and development during the 2025 fiscal year using institutional personnel 
  2. This institution is a centre collégial de transfert de technologie et de pratiques sociales novatrices (college centre for the transfer of technology and innovative social practices; CCTT) registered as a not-for-profit organization
  3. This institution is a technology transfer office, registered as a not-for-profit organization, providing intellectual property management and support services to higher education sector clients 
  4. None of the above

8. Report this institution’s fiscal year that had an end date between April 1, 2025, and March 31, 2026.

All questions in this survey should be answered in reference to this institution’s fiscal year reported above. This corresponds to the reference year for the survey (2025).

From: YYYY-MM-DD
To: YYYY-MM-DD


Help text block for reporting instructions

Many universities, colleges, polytechnics and CEGEPs have complex legal structures covering multiple legal entities that serve the core activities of the higher education institution. The following question is not an exercise to list all the legal structures that are part of an institution's organizational structure but to clarify what entities are being reported through this questionnaire to avoid double counting.

In general, this report should include all organizational units and legal entities that support the mission of the higher education institution.
This includes the activities of all departments within the institution that are engaged, in whole or in part, in research, intellectual property support and management, and commercialization. For colleges and CEGEPs this includes the activities of Centre collégial de transfert de technologie et de pratiques sociales novatrices (college centres for the transfer of technology and innovative social practices; CCTTs) and Technology Access Centres that are embedded within the institution.

Postsecondary institutions affiliated with research institutes or hospitals should report only the portion of research activities carried out at the affiliated hospital, research institute or research centre that is under the direct control of or administered by the postsecondary institution. Research activities that are not under the control or administered by the postsecondary institution should not be reported.

Technology Transfer Offices (TTOs) and CCTTs that operate as separate not-for-profit organizations affiliated with one or more postsecondary institutions, as subsidiaries may report independently.

Combined reporting

A single combined response may be submitted for the following institutional entities or arrangements, provided that the information is held or managed by the institution completing this survey, and the affiliated institution is not submitting a report in its own name.

Examples of affiliated legal entities that may be included in a combined report include:

  • affiliated or federated university colleges that do not administer research funding independently, and do not receive invention disclosures directly
  • small affiliated entities whose research activities (if any) and intellectual property are fully managed by the parent institution
  • established network of institutions, wholly owned and operated subsidiaries (e.g., innovation centres, affiliated research institutes)
  • TTOs and CCTTs that operate as separate not-for-profit organizations affiliated with one or more postsecondary education institutions, as subsidiaries, where noted in Question 10.

9. Does this report cover one or more legal entities? 

  1. This response covers a parent legal entity named in Question 1
    Select this option if you are:
    • an overarching institution, such as a university, college, CEGEP or polytechnic. Include any centre collégial de transfert de technologie et de pratiques sociales novatrices (college centre for the transfer of technology and innovative social practices; CCTT), Technology Access Centre or Technology Transfer Office (TTO)embedded within the institution in this report; or,
    • a CCTT or TTO that operates as a separate not-for-profit organization affiliated with one or more postsecondary institutions.
  2. This response covers the institution named in Question 1 and one or more independent affiliated legal entities
  3. The response for this institution is included in the report of another institution

Please name the institution that is providing the information on behalf of this institution:

Select this option if another institution is reporting on behalf of this institution.

10. For each institution included in this report (including the parent institution), please provide the following information.


Help text

To add an institution, enter the institution’s legal name, federal business number and select the type of institution. Then click the add this institution box.

To remove an institution, click on the Remove this institution button.

Providing a federal business number is optional. If a business number is not available, you may leave this field blank and continue adding the institution.


Current number of institutions included in this report:

Legal name of institutionFederal business number (nine digits)Type of institution
  Select

Select type of institution:

  • University
  • College 
  • Polytechnic
  • CEGEP
  • Engineering school
  • Management or commerce school
  • Centre collégial de transfert de technologie et de pratiques sociales novatrices (college centre for the transfer of technology and innovative social practices) or Technology Access Centre 
  • Technology transfer office 
  • Other institution

11. Please provide any additional comments or clarifications that may help us interpret or better understand your responses to module 1: Institutional information.

Text box:

Module 2: Research partnerships (Question 12 to Question 15)

12. Did this institution have any active formal institutional-level research partnership agreements in place?


Help text

An institutional-level research partnership agreement refers to a formal, ongoing collaboration framework with an external organization that supports multiple or future research projects. These agreements are broader than individual project-specific research and development (R&D) agreements.

Include

  • strategic research alliances
  • institutional-level partnerships with any sector (e.g., business, government, non-profit institution)
  • consortium participation where this institution is a named partner
  • long-term collaboration supporting multiple projects
  • joint research institutes, research centres or affiliation agreements that support multiple or ongoing research projects, even where the agreement covers activities beyond research.

Exclude

  • individual, project-specific R&D agreements (these should be reported in subsequent questions).
  • ancillary agreements (e.g., non-disclosure agreements, material transfer agreements, licensing agreements)
  • informal collaborations without a signed agreement.

  • Yes
    If ‘Yes’ is selected:
    Please select all types of active partners. 
    1. Businesses
    2. Federal government
    3. Other levels of government (e.g., provincial, territorial, municipal, Indigenous)
    4. Non-profit organizations
    5. Other universities
    6. Other colleges
    7. Centres collégiaux de transfert de technologie et de pratiques sociales novatrices (college centres for the transfer of technology and innovative social practices; CCTT) that operate as separate not-for-profit organizations
    8. Hospitals
    9. Research institutes
    10. International organizations
    11. Other - Please specify other types of partners
  • No

13. In the 2025 fiscal year, did this institution manage any of the following types of research and development (R&D) agreements? 


Help text

This question applies only to R&D agreements or contracts that govern specific research projects or collaborations, and not to general agreements or supporting documents.

Please exclude framework-type agreements, such as consortium memberships, general partnerships, memoranda of understanding and informal agreements that establish general collaboration terms.

In addition, exclude ancillary or supporting agreements (e.g., material transfer agreements, non-disclosure agreements or licensing agreements for existing intellectual property) that support a primary project-level R&D agreement.


Select all that apply.

  1. Sponsored or Contract Research Agreements
    (definition: external funded research projects with defined deliverables, timelines, and intellectual property terms)
  2. Collaborative Research Agreements (no external funds brought to this institution)
    (e.g., projects conducted jointly with external partners without financial transfers)
  3. Grant-Based Research Agreements
    (e.g., research projects funded through formal grants (government or non-profit) with binding terms)
  4. Clinical Trial/Clinical Research Agreements
    (e.g., projects involving human subjects, clinical trials or regulated clinical research)
  5. Research Services/Testing Agreements
    (e.g., fee-for-service where this institution delivers research, testing or analysis according to a defined statement of work)
  6.  Other type of R&D agreement - Please specify other types of R&D agreements managed by this institution
    Or
  7. This institution did not manage any R&D agreements 

14. Which of the following research infrastructure or facilities at this institution were used by external partners or clients (e.g., under research contracts, collaborations or service agreements)?


Help text

Include

  • cases where external partners or clients accessed, used or benefited from this institution's research infrastructure, facilities, equipment, databases, materials or specialized resources
  • access may be provided directly, through supervised use, through institution staff acting on behalf of the external partner or through services delivered using the infrastructure 
  • the provision of materials, samples, datasets or other research resources to external organizations under formal agreements (e.g., material transfer agreements, data-sharing agreements or similar arrangements).

Exclude

  • facilities used solely by faculty or staff acting in their institutional role, even if the research was conducted under external contract or funding
  • major national research facilities and large-scale research infrastructures that are hosted by, but not operated as part of, this institution. Examples include TRIUMF, SNOLAB, Ocean Networks Canada, Ocean Tracking Network, VIDO, and the Icebreaker facilities
  • national advanced research computing infrastructure administered by the Digital Research Alliance of Canada.

Select all that apply.

  1. Research facilities (e.g., laboratories, test facilities, greenhouses) 
  2. Specialized technology platforms (e.g., clean rooms, nanofabrication, imaging and microscopy facilities)
  3. Digital research infrastructures owned by this institution (e.g., supercomputers or high-performance computing clusters, data platforms, simulation environments, data repositories; include only those that are not designated national infrastructure)
  4. Life sciences and health infrastructures (e.g., biobanks, clinical research units)
  5. Field and environmental infrastructures (e.g., observatories, research and field stations, environmental monitoring systems)
  6. Social sciences and digital humanities infrastructures (e.g., survey labs, digital humanities platforms)
  7. Prototyping, machine shop, makerspace facilities
  8. Other - Please specify other research infrastructure or facilities used by external partners
    OR
  9. This institution did not provide access to any research infrastructure or facilities to external clients during the fiscal year

15. Please provide any additional comments or clarifications regarding your responses to module 2: Research partnerships, including any context that may help us interpret your responses (optional).

Text box:

Module 3: Intellectual property (Question 16 to Question 35)


Help text block for questions 16 to 22

Intellectual property (IP)-related activities

Activities related to IP are actions that involve identifying, protecting, managing or using IP (e.g., patents, copyrights, trademarks) or supporting others in doing so.

These activities may support the development, commercialization or application of research results, technologies or new ideas.

Management and support of IP refer to institutional activities that help identify, protect, manage or enable the use of IP, even if this institution does not own or commercialize the IP directly.

IP related activities may also include, for example:

  • using invention disclosure processes
  • finding external collaborations
  • identifying potential use
  • providing IP assessment or advisory services
  • creating documentation required to protect IP
  • providing patent, copyright or other IP protection support
  • managing or licensing IP
  • licensing support or guidance
  • providing commercialization or knowledge transfer support
  • facilitating external collaborations related to IP development or use
  • providing funding for IP activities 
  • applying for IP on behalf of a third party or supporting an application by creating required documentation.

Institutions should include these activities whether support is provided in-house or delivered through external partners.

IP activities may be carried out by one or more units within an institution or organization, such as an office of applied research, a vice president’s research office, an industry liaison office or a technology transfer office.


16. In the 2025 fiscal year, did this institution provide the following activities through offices or units with formally assigned responsibility for intellectual property (IP) management or support?


Help text

For this question, consider only activities conducted by formal offices or units with assigned responsibility for IP management or support (e.g., technology transfer offices, research offices or equivalent).

IP management includes the identification, protection, and licensing of Intellectual property (e.g., invention disclosures, patenting, licensing).

IP support includes advisory or facilitation services directly related to these activities (e.g., patent strategy advice, disclosure support, IP-related industry liaison). 

Include

  • IP management or support activities provided directly by this institution’s staff.

Exclude

  • general entrepreneurship or commercialization activities (e.g., incubators, accelerators, entrepreneur-in-residence programs, business mentorship) 
  • activities not tied to specific IP assets or IP processes
  • academic coursework related to IP.

Select all that apply.

  1. This institution provided IP management activities
  2. This institution provided IP support activities
  3. This institution outsourced IP management or support activities to other postsecondary institutions
  4. This institution outsourced IP management or support activities to external offices other than postsecondary institutions
    OR
  5. This institution did not perform IP support or management activities and did not outsource them

17. How were responsibilities for intellectual property (IP)–management and support organized within this institution in the 2025 fiscal year?


Help text

Consider only units with formally assigned responsibility for IP activities (e.g., office of applied research, vice president’s research office, industry liaison office, technology transfer office or research offices), regardless of their location within the institution.


Select only one.

  1. Centralized—a coordinated central office manages IP activities within the institution. (e.g., research office or technology transfer office)
  2. Decentralized—a dispersed number of offices manage IP activities for their respective areas of responsibility. 
  3. There is no formal organizational responsibility for IP recognized within this institution.

18. For the 2025 fiscal year, provide the number of full-time equivalent (FTE) employees in formal offices or units responsible for intellectual property (IP) management or support.


Help text

FTE employees are the number of FTE jobs, defined as total hours worked divided by average annual hours worked in full-time jobs. This can also be described as FTE work-years. If you have three persons working one quarter of their time on this activity, the FTE is equal to 0.25+0.25+0.25 = 0.75 FTE.

Include

  • staff with explicitly assigned responsibilities for IP (identification, protection, licensing).

Exclude

  • staff in incubators, accelerators, entrepreneur-in-residence programs or other commercialization initiatives unless they are part of a formal IP-responsible unit
  • faculty or researchers without formally assigned IP roles
  • general entrepreneurship or business support.

Total number of FTE employees:

19. Please provide or estimate the total operating budgets of all formal offices or units responsible for intellectual property (IP) management and support in the 2025 fiscal year.


Help text

Report all amounts in thousands of Canadian dollars (CAN$ ’000). For example, report $1,250,000 as 1,250.

Include budget for IP costs (e.g., fees paid to external patent attorneys or agents, patent maintenance fees, Intellectual property filing fees).

Exclude the costs associated with courses that lead to completion of degree or certification and the salaries of professors that do not work within an office that manages IP.

Please specify in the end-of-module comment box if your response is an estimate.


 Total amount (CAN$ ’000)
Total operating budget for management or support of IP 

20. In the 2025 fiscal year, which organizations received intellectual property (IP) services from this institution?


Help text

Include all organizations that received IP services during the 2025 fiscal year.

For centres collégiaux de transfert de technologie et de pratiques sociales novatrices (college centres for the transfer of technology and innovative social practices; CCTT) registered as a not-for-profit organization, please indicate if IP services are provided to the CEGEP(s) or college(s) with which the CCTT is affiliated.

If this report covers more than one institution (as indicated in Question 9), please report as internal all IP-related services provided to institutions combined in this report.

Higher education includes universities, colleges, polytechnics, CEGEPs, and research units administered by them.

Government includes federal, provincial/territorial, and other levels and types of government organizations and public research bodies.


Select all that apply.

  1. Internal users within this institution
  2. Affiliated CEGEPs or colleges 
  3. External (arm’s-length) research institutes, hospitals or hospital research centres
  4. External (arm’s-length) higher education institutions
  5. External (arm’s-length) organizations such as businesses or government organizations
  6. Other - Specify the other types of users or organizations receiving IP services

21. For each of the following types of recipients, indicate which services related to intellectual property (IP) were provided by this institution.

  1. IP services provided from the institution to internal users
    Select all that apply.
    1. Identifying or assessing IP potential (e.g., disclosure review, market or feasibility assessment)
    2. Managing or supporting IP protection (e.g., preparing disclosures, working with legal advisors, filing applications)
    3. Providing IP advice or strategy (e.g., ownership, protection, commercialization approaches)
    4. Negotiating or managing IP-related agreements (e.g., research or licensing agreements)
    5. Managing IP assets or portfolio (e.g., tracking, maintaining records, managing filings)
    6. Managing or supporting commercialization of IP
    7. Providing training, outreach or awareness related to IP (exclude formal academic programs)
    8. Providing funding for IP activities
  2. IP services provided from the institution to affiliated colleges and CEGEPs
    Select all that apply.
    1. Identifying or assessing IP potential (e.g., disclosure review, market or feasibility assessment)
    2. Managing or supporting IP protection (e.g., preparing disclosures, working with legal advisors, filing applications)
    3. Providing IP advice or strategy (e.g., ownership, protection, commercialization approaches)
    4. Negotiating or managing IP-related agreements (e.g., research or licensing agreements)
    5. Managing IP assets or portfolio (e.g., tracking, maintaining records, managing filings)
    6. Managing or supporting commercialization of IP
    7. Providing training, outreach or awareness related to IP (exclude formal academic programs)
    8. Providing funding for IP activities
  3. IP services provided from the institution to external research institutes or hospitals
    Select all that apply.
    1. Identifying or assessing IP potential (e.g., disclosure review, market or feasibility assessment)
    2. Managing or supporting IP protection (e.g., preparing disclosures, working with legal advisors, filing applications)
    3. Providing IP advice or strategy (e.g., ownership, protection, commercialization approaches)
    4. Negotiating or managing IP-related agreements (e.g., research or licensing agreements)
    5. Managing IP assets or portfolio (e.g., tracking, maintaining records, managing filings)
    6. Managing or supporting commercialization of IP
    7. Providing training, outreach or awareness related to IP (exclude formal academic programs)
    8. Providing funding for IP activities
  4. IP services provided from the institution to external higher education institutions
    Select all that apply.
    1. Identifying or assessing IP potential (e.g., disclosure review, market or feasibility assessment)
    2. Managing or supporting IP protection (e.g., preparing disclosures, working with legal advisors, filing applications)
    3. Providing IP advice or strategy (e.g., ownership, protection, commercialization approaches)
    4. Negotiating or managing IP-related agreements (e.g., research or licensing agreements)
    5. Managing IP assets or portfolio (e.g., tracking, maintaining records, managing filings)
    6. Managing or supporting commercialization of IP
    7. Providing training, outreach or awareness related to IP (exclude formal academic programs)
    8. Providing funding for IP activities
  5. IP services provided from the institution to external partners or clients
    Select all that apply.
    1. Identifying or assessing IP potential (e.g., disclosure review, market or feasibility assessment)
    2. Managing or supporting IP protection (e.g., preparing disclosures, working with legal advisors, filing applications)
    3. Providing IP advice or strategy (e.g., ownership, protection, commercialization approaches)
    4. Negotiating or managing IP-related agreements (e.g., research or licensing agreements)
    5. Managing IP assets or portfolio (e.g., tracking, maintaining records, managing filings)
    6. Managing or supporting commercialization of IP
    7. Providing training, outreach or awareness related to IP (exclude formal academic programs)
    8. Providing funding for IP activities

22. In the 2025 fiscal year, which of the following services related to intellectual property (IP) were obtained from external providers?

  1. IP services obtained from external providers
    Select all that apply.
    1. Identifying or assessing IP potential (e.g., disclosure review, market or feasibility assessment)
    2. Managing or supporting IP protection (e.g., preparing disclosures, working with legal advisors, filing applications)
    3. Providing IP advice or strategy (e.g., ownership, protection, commercialization approaches)
    4. Negotiating or managing IP-related agreements (e.g., research or licensing agreements)
    5. Managing IP assets or portfolio (e.g., tracking, maintaining records, managing filings)
    6. Managing or supporting commercialization of IP
    7. Providing training, outreach or awareness related to IP (exclude formal academic programs)
    8. Providing funding for IP activities
      OR
    9. IP services were not obtained from external providers

23. In the 2025 fiscal year, did this institution receive any invention disclosures?


Help text

An invention disclosure is a formal submission by a researcher, staff member or student to this institution (e.g., to a technology transfer or intellectual property (IP) office) describing a potentially protectable invention, design, copyright, patent, plant variety, software or algorithm, trade secret or trademark.

Exclude

  • licensing agreements or licences executed without an invention disclosure
  • IP originating entirely outside this institution (unless formally disclosed to this institution).

  • Yes
  • No

24. In the 2025 fiscal year, did this institution protect, or help its researchers to protect, any of its disclosed inventions or creations using any of the following intellectual property types?

Select all that apply.

  1. Patents
  2. Copyrights
  3. Trademarks
  4. Industrial designs 
  5. Plant varieties
  6. Trade secrets
  7. Other - Please specify other types of IP protection
    OR
  8. This institution did not pursue any protection for any newly disclosed inventions

25. In the 2025 fiscal year, did this institution hold or own any type of intellectual property?

  • Yes
  • No

26. How is intellectual property ownership determined at this institution?


Help text

More than one mechanism may apply.

Institutional policies may guide internal research, while contracts often determine ownership in collaborative research.

Select all options that reflect how ownership is determined across this institution.


Select all that apply.

  1. Determined by institutional rules (e.g., institutional policies, directives, frameworks or similar instruments, employment agreements or collective agreements)
  2. Determined through negotiated project-specific contracts or agreements
  3. Researchers may choose whether to retain or assign ownership (i.e., inventor choice)
  4. Determined by external requirements (e.g., funding program requirements, government legislation, directives or frameworks that predetermine or restrict ownership.
  5. Other - Please specify other methods of determining IP ownership

27. For intellectual property generated from research and development conducted at this institution, which parties assume ownership under the following scenarios?

  1. Research conducted solely by the reporting institution 
    Select all that apply.
    1. Ownership by researchers
    2. Ownership by the institution 
    3. Joint ownership between researchers and the institution
    4. Varies depending on the project
    5. Other - Please specify other ownership arrangements
  2. Research conducted at this institution in collaboration with any external partners such as other institutions in the higher education sector, businesses, governments or non-profit organizations.
    Select all that apply.
    1. Sole ownership by this institution
    2. Joint ownership among education institutions
    3. Ownership by researchers
    4. Joint ownership among education institutions and individual researchers
    5. Ownership by non-education partners
    6. Joint ownership between this institution and one or more non-education partners
    7. Joint ownership among all participants
    8. Ownership by one or more collaborating partners where this institution does not hold ownership
    9. Ownership varies depending on the project or agreement
    10. Other - Please specify other ownership arrangements
      OR
    11. Not applicable

28. In the 2025 fiscal year, for intellectual property generated from research and development conducted at this institution, which ownership structure was the most common at the institution?

  1. Research conducted solely by the reporting institution
    1. Ownership by researchers
    2. Ownership by the institution 
    3. Joint ownership between researchers and the institution
    4. Varies depending on the project
    5. Other
  2. Research conducted at this institution in collaboration with any external partners, such as other higher education sector institution(s), businesses, government or non-profit organizations. 
    1. Sole ownership by this institution
    2. Joint ownership among education institutions
    3. Ownership by researchers
    4. Joint ownership among education institutions and individual researchers
    5. Ownership by non-education partners
    6. Joint ownership between this institution and one or more non-education partners
    7. Joint ownership among all participants
    8. Ownership by one or more collaborating partners where this institution does not hold ownership 
    9. Ownership varies depending on the project or agreement
    10. Other

29. For the 2025 fiscal year, how many patent applications were filed, how many patents were granted and how many active patents were held by this institution?

Include

  • patents owned or co-owned by the institution
  • patents and applications managed on behalf of the institution (e.g., by a Technology Transfer Office or affiliated entity)
  • new applications filed and patents granted during the fiscal year
  • active patents, which include all patents that were in force at the end of the fiscal year, regardless of when they were granted.

Exclude

  • patents owned only by external organizations (e.g., industry partners)
  • patents where the institution has no ownership or legal rights
  • duplicate reporting of the same patent by multiple entities.
 Total number
Patent applications filed during the fiscal year 
New patents granted during the fiscal year 
All active patents held at the end of the fiscal year  

30. In the 2025 fiscal year, what types of intellectual property (IP) did this institution license?

A licence is a formal legal agreement that grants a person or organization permission to use, make, reproduce, modify, sell or otherwise exploit IP owned by another party, under specified terms and conditions, while ownership of the IP remains with the licensor.

A licence may be:

  • exclusive (granted to one licensee only)
  • non-exclusive (granted to multiple licensees)
  • sole (shared between the licensor and one licensee)
  • royalty-bearing or royalty-free.

In short, a licence provides permission to use IP without transferring ownership.

Select all that apply.

  1. Patents
  2. Software or digital tools (e.g., databases) 
  3. Industrial designs 
  4. Copyrights 
  5. Trademarks, branding or marketing outputs 
  6. Integrated circuit topographies 
  7. Plant varieties or breeders’ rights 
  8. Research datasets or data collections 
  9. Biological materials or cell lines 
  10. Other - Please specify other types of IP licensed
    OR
  11. This institution did not license IP in the 2025 fiscal year 

31. What were the total payments received from external parties for intellectual property (IP) owned by this institution?

Include

  • licensing income (e.g., fees, royalties, milestone payments) 
  • option and access fees
  • sales of IP
  • realized equity gains 
  • settlement income from IP enforcement.

Exclude

  • in-kind contributions or non-monetary benefits
  • internal transfers within this institution or affiliated entities
  • unrealized equity value 
  • patent reimbursement.

Amount (CAN$ ’000):

32. Please rate the importance of the following obstacles in limiting or affecting this institution's commercialization of intellectual property (IP) capabilities.


Help text

Commercialization activities include actions that support the development, transfer or use of research, technologies or IP in real-world or market settings. Examples include licensing IP, creating start-ups or spin-offs, developing partnerships with industry, prototyping or testing technologies, and supporting adoption or market entry.


Rate the importance.
Select from “not important” to “very important” as applicable

Type of obstaclesNot importantSlightly importantModera-tely importantImportantVery important
Lack of commercialization expertise or culture within this institution     
Limited personnel in tech transfer offices or research and development commercialization teams     
Market constraints
(e.g., small domestic market, uncertain demand, competitive environment)
     
Lack of industry partners or networks
(e.g., few potential licensees, collaborators or co-developers)
     
Lack of available funding to support proof of concept development     
Limited access to funding for commercialization
(e.g., venture capital, seed funding, angel investors or early-stage commercialization grants)
     
Regulatory or administrative burden or complexity     
Difficulties and complexities associated with patenting IP     
Other     

33. Please specify the “other” obstacles that this institution encountered in the commercialization of intellectual property.

Other obstacles:

34. Which of the following types of resources did this institution use for information, guidance or advice on intellectual property (IP) matters?

Select all that apply.

  1. Canadian Intellectual Property Office
  2. Other Canadian government offices
    (e.g., federal, provincial, territorial, municipal, Indigenous) 
  3. Foreign IP offices 
    (e.g., United States Patent and Trademark Office, World Intellectual Property Organization)
  4. Trade commissioner services
  5. Business incubators or accelerators
  6. IP clinics
  7. Academic and research institutions
    (e.g., universities, technology transfer offices, research labs, innovation hubs)
  8. In-house legal counsel or legal departments 
    (exclude external law firms or lawyers)
  9. External law firms or lawyers
    (exclude in-house legal counsel or legal department)
  10. IP strategists
  11. Professional consulting or advisory firms (non-legal)
    (e.g., innovation consultants, IP advisory firms, accounting firms with IP expertise)
  12. In-house patent or trademark agents
  13. External patent or trademark agents
  14. Industry associations, chambers of commerce or business partner networks
  15. Online IP databases and tools
    (e.g., patent databases such as Espacenet, Google Patents, trademarks, databases)
  16. Standards organizations or industry consortia
    (e.g., standards bodies, sector-specific alliances)
  17. Financial institutions or funding agencies
    (e.g., venture capital firms, grant agencies, innovation funding bodies)
  18. Internal non-legal teams
    (e.g., research and development departments, innovation or commercialization teams)
  19. Other sources - Please specify other types of resources used for IP information, guidance or advice
    (e.g., friends, peers, mentors, word of mouth, other online sources, webinars, conferences, training programs)
    OR
  20. This Institution did not use any of the above noted resources for information, guidance or advice on IP matters 

35. Please provide any additional comments or clarifications regarding your responses to module 3: Intellectual property. Include any context that may help us interpret your responses (optional).

Text box:

Module 4: Support for advancing projects toward commercialization (Question 36 to Question 40)

36. In the 2025 fiscal year, did this institution engage in any of the following product, process or prototype validation, refinement or development activities? 


Help text

The response options are organized according to Technology Readiness Levels (TRL), which describe the maturity of a product, process or prototype.

Technology Readiness Levels (TRL)

  • TRL 1–3: Early-stage research, concept development, and proof-of-concept activities.
  • TRL 4–6: Prototype refinement and testing in operational or user environments.
  • TRL 7+: Final development, qualification, demonstration, and preparation for deployment, commercialization or operational use.

Please refer to the reporting guide for more detailed definitions.


Select all that apply.

  1. Research, concept development, and proof-of-concept of products, processes or prototypes in controlled or simulated environments (associated with TRL 3 and below)
  2. Refinement and testing of products, processes or prototypes in operational or user environments (associated with TRL 4, 5 or 6)
  3. Final development, qualification or market-ready preparation of products, processes or prototypes (associated with TRL 7 and above)
    OR 
  4. This institution did not engage in any of these activities in the 2025 fiscal year

37. In the 2025 fiscal year, to what extent were activities that advanced research outcomes toward commercialization tracked at this institution?


Help text

These are activities that involve final development, qualification or market-ready preparation of products, processes or prototypes (associated with technology readiness levels 7+).


Select one of the following.

  1. Fully and systematically tracked across the institution
  2. Tracked in some units or programs only
  3. Informally or inconsistently tracked
  4. Not tracked
  5. Don’t know 

38. In the 2025 fiscal year, how many new or improved products, processes or prototypes reached final development, demonstration, qualification or preparation for deployment, operational use or commercialization (associated with technology readiness levels 7 or higher)?


Help text

New or improved product: The introduction of a good that is new or significantly improved with respect to its characteristics or intended use. Improvements may include technical specifications, components, materials, software, user experience or other functional features.

Prototype: An early, functional version of a product, system or process developed to test, validate or refine a concept or design prior to full implementation or release.

Only include prototypes that are sufficiently developed to be tested or evaluated in practice during the reporting period. Prototypes may undergo multiple iterations as part of the development process.

Routine coursework, instructional exercises or conceptual projects are not considered prototypes unless they are used for formal testing, validation or advancement toward practical application.

New or improved process: Implementation of a new or significantly improved production or delivery method. This includes significant changes in techniques, equipment or software.

TRL 7+ refers to the final development, qualification or market-ready preparation of products, processes or prototypes.


  • Number of new or improved products:
  • Number of new or improved processes:
  • Number of new or improved prototypes:

39. Please provide any additional comments or details to help us understand your answer to the previous question (optional). 

Text box:

40. Please provide any additional comments or clarifications that may help us interpret or better understand your responses related to module 4: Support for advancing projects toward commercialization (optional). 

Text box:

Module 5: Business support (Question 41 to Question 47)

41.  In the 2025 fiscal year, did this institution support the creation of spin-offs?


Help text

Spin-off:

A spin-off is a new company created to commercialize intellectual property (IP), knowledge, technology or other research outputs developed at this institution where there is a formal and verifiable relationship to IP developed at this institution.

For the purpose of this survey, include only those companies where there is a formal and verifiable relationship to IP developed at the institution such as option and licensing agreements, invention disclosures or equity participation.

Please consider companies that registered as a legal entity within the 2025 fiscal year.

When answering this section, report only activities related to spin-offs. Information on supports provided to other external businesses will be collected in separate questions below.

Please refer to the reporting guide for detailed inclusion and exclusion instructions.


  • Yes
  • No

42. In the 2025 fiscal year, how many spin-offs were created from intellectual property generated from research and development activities originating at this institution? 

  1. Number of spin-offs:
  2. This institution does not track spin-offs

43. Please provide the legal name and business number for each spin-off company that was created from intellectual property generated from research and development activities originating at this institution and incorporated in the 2025 fiscal year.


Help text

To add a spin-off, enter the legal name and federal business number under the add spin-off heading. Then click the add this spin-off box.

To remove a spin-off, click on the Remove this spin-off button.

Providing a federal business number is optional. If a business number is not available, you may leave this field blank and continue adding spin-offs.

Link to search federal corporations: Search for a Federal Corporation - Online Filing Centre - Corporations Canada - Corporations - Innovation, Science and Economic Development Canada


Current number of spin-offs:

  • Remove spin-off
Legal nameFederal business number (nine digits) 
  + Add this spin-off

44. Which of the following types of resources or services did this institution provide to spin-offs that were created from intellectual property (IP) generated from research and development (R&D) activities originating at this institution?


Help text

Please indicate the resources or services that were offered to spin-offs that emerged from this institution.

Include resources, services or mentorship provided for any spin-off that emerged from this institution at any time and under any circumstance.

Exclude resources or services for any external business to this institution (this also includes any start-ups).


Select all that apply.

  1. Prototype or minimum viable product development, including mentorship or direct technical assistance
  2. Access to student internships or co-op placements 
  3. Market research
  4. Data analysis 
  5. Hosting of pitch competitions or hackathons 
  6. Access to R&D services
  7. Access to institutional facilities, physical space, equipment or research infrastructure
    (e.g., laboratories, testing facilities, workshops, office space, shared research facilities, specialized equipment or digital research infrastructure)
  8. Access to legal clinics  
  9. Faculty-supervised projects involving enterprise problems 
  10. Collaboration on grant writing or government funding applications 
  11. Support with preparing ventures for investment and facilitating engagement with investors
  12. Support with the adoption and implementation of technologies in practice 
    (e.g., developing adoption, training or integration plans for putting new technologies or techniques into operations)
  13. Company formation and governance support
  14. Provision of incubator or accelerator programs or services
  15. Provision of IP management or support
  16. Other support - Please specify the other type of support provided
    OR
  17. This institution did not provide any type of support to spin-offs that emerged from this institution

45. In the 2025 fiscal year, did this institution support the creation of start-up companies?


Help text

Start-up:

A start-up is a new company created to address a market need, typically built on a novel idea or technology and supported by a business plan and growth strategy.

For the purpose of this survey, start-up refers to a business that may receive support from this institution, but where there is no formal or verifiable relationship to IP developed at this institution.

Start-ups may include student-led ventures, incubator or accelerator-supported companies or external clients.

Please consider companies that registered as a legal entity within the 2025 fiscal year.

Please refer to the reporting guide for detailed inclusion and exclusion instructions.


  • Yes
  • No

46. Which of the following types of resources or services did this institution provide to start-ups or external businesses (at arm’s length to this institution; this excludes spin-offs that were created from intellectual property (IP) generated from research and development (R&D) activities originating at this institution)? 


Help text

Please indicate the resources or services that were offered to external businesses (arm’s-length businesses).

Include resources, services or mentorship provided to any external business to this institution.

Exclude resources or services for any spin-offs that were created from IP generated from R&D activities originating at this institution at any time and under any circumstance.


Select all that apply. 

  1. Prototype or minimum viable product development, including mentorship or direct technical assistance
  2. Access to student internships or co-op placements 
  3. Market research
  4. Data analysis 
  5. Hosting of pitch competitions or hackathons 
  6. Access to R&D services
  7. Access to institutional facilities, physical space, equipment or research infrastructure
    (e.g., laboratories, testing facilities, workshops, office space, shared research facilities, specialized equipment or digital research infrastructure)
  8. Access to legal clinics
  9. Faculty-supervised projects involving enterprise problems 
  10. Collaboration on grant writing or government funding applications 
  11. Support with preparing ventures for investment and facilitating engagement with investors
  12. Support with the adoption and implementation of technologies in practice
    (e.g., developing adoption, training or integration plans for putting new technologies or techniques into operations)
  13. Company formation and governance support
  14. Provision of incubator or accelerator programs or services
  15. Provision of IP management or support
  16. Other support - Please specify the other type of support provided
    OR
  17. This institution did not provide any type of support to start-ups or external businesses

47. Please provide any additional comments or clarifications regarding this institution’s responses to module 5: Business support, including any context that may help us interpret your responses (optional).

Text box:

Module 6: Survey feedback (Question 48 to Question 52)

48. How many persons were consulted or involved in completing this survey?

  1. 1
  2. 2 or 3
  3. 4 to 10
  4. 11 or more
  5. Don’t know

49. Please provide any additional comments or clarifications regarding this institution’s responses to the previous question, including any context that may help us interpret your responses (optional).

Text box:

50. Is respondent name the best person to contact?

  • Yes
  • No
    Who is the best person to contact about this questionnaire?
    • First name
    • Last name
    • Title
    • Email address
      (Example: user@exemple.gov.ca)
    • Telephone number (including area code)
      (Example: 123-123-1234)
    • Extension number (if applicable)
    • Fax number (including area code)
      (Example: 123-123-1234)

51. How long did it take to complete the questionnaire?

Hours:
Minutes: 

52. Do you have any comments about this questionnaire?

Text box:

Monthly Survey of Food Services and Drinking Places: CVs for Total Sales by Geography - July 2026

CVs for Total sales by geography
GeographyMonth
202507202508202509202510202511202512202601202602202603202604202605202606202607
percentage
Canada0.050.060.060.080.070.090.120.100.080.110.090.060.19
Newfoundland and Labrador0.200.200.280.310.320.450.530.460.440.660.510.361.51
Prince Edward Island0.400.340.450.591.171.171.701.441.021.351.130.611.29
Nova Scotia0.170.190.240.250.600.430.380.360.720.570.440.270.71
New Brunswick0.190.210.350.390.820.360.470.410.970.570.480.310.67
Quebec0.080.170.150.270.170.180.280.240.200.240.220.150.30
Ontario0.070.090.100.130.120.160.200.160.130.190.150.100.33
Manitoba0.230.220.340.370.590.520.690.610.690.700.540.320.82
Saskatchewan0.540.260.400.350.690.460.531.110.690.780.490.320.91
Alberta0.190.160.160.170.200.230.320.210.220.380.220.170.39
British Columbia0.160.120.120.130.170.190.250.200.200.230.180.130.35
Yukon Territory1.031.071.321.642.062.182.842.742.433.072.341.652.81
Northwest Territories1.181.291.171.292.172.342.842.602.3312.262.251.452.58
Nunavut2.6747.682.722.4064.641.902.852.593.363.543.233.076.34

Guidelines Financial Information of Universities Canadian Association of University Business Officers (CAUBO) 2025-2026

Skip to text

I. Preamble

II. General Information

III. Detailed Instructions for Institutions Reporting Financial Data

Text begins

I . Preamble

Financial Information of Universities is an annual publication prepared by Statistics Canada for the Canadian Association of University Business Officers (CAUBO). CAUBO obtains the financial data for the publication by undertaking an annual survey of its degree granting member institutions. Users have indicated that the publication is a comprehensive reference source for the financial data of universities and colleges in Canada.

The financial data in the publication is based on an annual return completed and submitted by each member institution. The hard copy of the publication reports the financial data individually, by institution, and in aggregate, by province, region and nationally.

A. General

These Guidelines are intended to assist both users and preparers of the financial data reported in the annual return; specifically, these Guidelines will assist

  • Users –
    • to understand the limitations of the financial data;
    • to understand the different and distinct purposes between an institution's audited financial statements, its internal management reports and its annual return; and,
    • to understand, in general terms, the prescribed reporting practices underlying the financial data in the annual return.
  • Preparers –
    • to understand, in general terms, the users of the annual return and their information requirements;
    • to appreciate the differences between accounting principles for audited financial statements, internal management reports and prescribed reporting practices; and,
    • to appreciate that the financial data in the annual return must be consistent from one year to the next, and comparable between institutions.

The Guidelines are organized as follows:

Section II provides general information for both users and preparers of the annual return. This section discusses financial reporting by institutions and identifies the users of the annual return and their needs, as well as the relationship of generally accepted accounting principles to the financial data and the prescribed reporting practices underlying that data.

This section will assist users and preparers of the annual return to appreciate the differences between accounting principles for audited financial statements and prescribed reporting practices for the annual return. In addition, by understanding the information requirements of the users of the annual return, preparers should be better able to complete the annual return form in a manner that encourages consistency in reported data for each institution over time and, in accordance with the Guidelines, facilitates comparability between institutions.

Section III provides detailed instructions for institutions reporting financial data. This is the "how-to" section for preparers to refer to when completing the annual return, and will be of interest to users who seek additional information on specific terms or particular line items used in the annual return.

B. Limitations

While users require financial data that are consistent from one year to the next and comparable between institutions, users must also appreciate that notwithstanding the use of detailed Guidelines to assist preparers, there are limitations in the comparability of the data. The data is most useful when aggregated and used for trend analysis. As users move from aggregated data to data that directly compares institutions, either individually or even between provinces or regions, the comparability of the data has limitations.

Limitations in the comparability of the data can result because of differences in the underlying accounting practices followed by institutions. Even the most stringent of reporting guidelines cannot eliminate differences resulting from different underlying accounting practices. Limitations can also result from other inherent differences. Institutional comparisons are subject to interpretation and clarification because of differences such as size, academic programs, structure, physical environment, management philosophy, and budgetary and accounting procedures. Interregional comparisons must also recognize differences such as various sources of funding, fiscal year-end dates varying from March 31st to June 30th, and variations in provincial policies and provincial funding responsibilities.

Specific examples where differences between institutions result in limitations in the comparability of financial data include:

  • Definition of research – The definition of research used by an institution will determine the income and expenditures that are reported in the Sponsored research fund. For example, clinical trials may or may not be defined as research and therefore may or may not be reported as sponsored research expenditures.
  • Hospitals and hospital based medical research – The amount and level of detail reported by institutions for hospitals and for hospital based medical research varies depending upon the corporate relationship between the institution and the hospital.
  • Canada Foundation for Innovation (CFI) – Provincial matching grants – while an institution separately reports certain specific provincial government grants that are earmarked as CFI matching grants, not all provincial CFI matching grants are separately reported because not all are specific and earmarked.
  • Internal sales and cost recoveries – Depending upon particular management information systems and business practices, an institution may report amounts by reducing offsetting expenditures or as internal cost recoveries.
  • Computing and communication costs – The amount reported by institutions for computing and for communication costs will vary depending upon whether an institution has a centralized or decentralized structure for computing and for communications.

In addition, comparisons of financial data over multiple years should be done with caution because of changes in generally accepted accounting principles that could alter the underlying data and changes in the Guidelines that govern the reporting of the data.

II . General Information

This section provides general information for both users and preparers of the annual return. It discusses financial reporting by institutions and identifies the users of the annual return and their needs, as well as the relationship of generally accepted accounting principles to the financial data and the prescribed reporting practices underlying that data.

This section will assist users and preparers of the annual return to appreciate the differences between accounting principles for audited financial statements and prescribed reporting practices for the annual return. In addition, by understanding the information requirements of the users of the annual return, preparers should be better able to complete the annual return in a manner that encourages consistency in reported data for each institution over time and, in accordance with the Guidelines, facilitates comparability between institutions.

A. Financial Reporting by Institutions

As previously stated, the CAUBO annual return is a comprehensive reference source for the financial data of universities and colleges in Canada. The annual return, however, is not the only source for financial information for individual institutions. An institution's primary financial report is its annual financial statements.

An institution's financial statements are prepared in accordance with generally accepted accounting principles and are subject to audit by external auditors. The financial statements are a public document and represent an accounting by the institution's Board of its financial stewardship of the institution as a whole.

An institution's annual return is prepared in accordance with prescribed reporting practices. An institution's annual return is not subject to audit, but is reconciled to its audited financial statements. The annual return is also available to the public, but rather than representing an accounting of financial stewardship, the annual return provides financial data for statistical comparisons among institutions and for trend analysis.

These two reports serve different and distinct purposes. Using audited financial statements, detailed comparisons of financial data between institutions are difficult, if not impossible. For statistical comparisons between institutions and for trend analysis, users of the financial data should refer to the CAUBO annual return. While the CAUBO annual return reports financial data that is more comparable between institutions and lends itself to validation, users should be aware of the limitations in the comparability of the data (see Section I .B).

B. Users of the Annual Return

Participating institutions submit the completed annual return to CAUBO for data verification and compilation by Statistics Canada. Once compiled and published, comparative statistics can be calculated and analyzed either for all institutions combined or for a group of institutions based on one or more characteristics common to the group. Examples of common characteristics include size, location, graduate programs and medicine.

The financial data is used for many and varied purposes. For example, at the aggregate level, the annual return is the principal source of financial data for the estimates of higher education research and development expenditures that are reported in Canada, and reported internationally, for Canada. At the institutional level, the financial data is used to establish the eligibility levels for funding under programs such as the Canada Foundation for Innovation (CFI).

The financial data is available to many and varied users. Common users include Statistics Canada and clients of Statistics Canada, associations such as AUCC (Association of Universities and Colleges of Canada), granting councils, other Federal and Provincial government departments and agencies, university analysts and other internal university constituencies, and the external research community.

By identifying users of the annual return and understanding their information requirements, reporting practices that best meet user needs can be determined. A point that cannot be overemphasized, however, is that the financial data reported by each institution will only be useful to users of the annual return when the data has been prepared consistently over time and has been prepared in accordance with the Guidelines to facilitate comparability between institutions.

C. Prescribed Reporting Practices

The audited financial statements of reporting institutions are prepared in accordance with generally accepted accounting principles (GAAP). For individual institutions, adherence to GAAP results in consistency of reported financial results from one year to the next.

In certain situations, however, GAAP permits individual institutions to choose between equally acceptable alternatives. To the extent institutions make different choices, the financial data, while consistent for one institution from one year to the next, may not be comparable between institutions. As an example, institutions can choose either the deferral or restricted fund method of revenue recognition, and reporting nuances of each method may make comparisons between institutions difficult.

In addition to the differences that exist between the financial data of institutions when they choose different practices from equally acceptable alternatives, the users of the annual return may require, in certain situations, financial data based on an accounting practice that deviates from GAAP . For example, users of capital expenditure data generally require line item reporting of income and expenditures based on the flow of funds, rather than on capitalized and amortized amounts.

By way of highlights, users and preparers of the financial data should note the following points that apply to the annual return, even though they may represent differences from the practices normally followed by individual institutions in reporting financial information:

  • Restricted funds include both external and internal restrictions, rather than external only.
  • Certain restricted income not expended in the year, such as income in the Sponsored research fund, is reported on the funds flow approach, rather than deferred (see Section II .E.4).
  • Capital expenditures are reported on the funds flow approach, rather than capitalized and amortized (see Section II .E.6).
  • Certain expenditures, such as vacation pay, pension costs and future benefits, are reported on the cash basis, rather than accrued (see Section II .E.7).
  • Institutions are encouraged to minimize interfund transfers by reporting income and the corresponding expenditures in the same fund (see Section II .E.9).
  • Users require income and expenditure data, only; therefore, a complete set of financial statements is not reported.

These Guidelines are not intended to conform an institution's annual return to its financial statements or its internal management reports. The prescribed practices, including the uniform reporting practices that follow, may or may not be in accordance with generally accepted accounting principles. These Guidelines are intended to promote comparability of financial data between institutions, while maintaining consistency.

D. Reconciliation to Audited Financial Statements

By following prescribed reporting practices, each institution will have one or more differences between its annual return and its audited financial statements. To ensure credibility of the financial data reported by an institution, each is required to reconcile the data in its annual return to its audited financial statements.

The reconciliation is reported in the Statement of Changes in Net Assets by Fund (Section III .C.4). While the types of items causing the differences between the two reports may vary among institutions, the number of such items is relatively few. The common reconciling items have been identified and can be reported on specified lines in the Statement of Changes in Net Assets by Fund.

E. Uniform Reporting Practices

For comparability of financial data between institutions, while maintaining consistency, reporting institutions and the preparers of the annual return within those institutions must comply with the Guidelines in general, and specifically with the uniform reporting practices. The uniform reporting practices, and the detailed instructions that follow in Section III , have been developed recognizing that balance is required between the information requirements of the users of the annual return and the response burden that is placed on the preparers. The uniform reporting practices are as follows:

1. Basis of Consolidation

For related and affiliated entities and except for certain research activities as noted below, each institution is to report financial data in the annual return on the same basis as that used for its consolidated financial statements. If the financial data for the entity is only reported in the notes to the consolidated financial statements, then the financial data is not reported in the annual return. To allow users to better understand the contents of the annual return and its limitations, each reporting institution is required to complete an affiliation report providing information for each legal entity that is consolidated with the annual return (see Section  III .C.6 – Part I ).

Sponsored research data are sometimes used for allocation purposes and users often look to the sponsored research reported by institutions as the main source of data for total funding of research activities of academic staff in Canada. As a result, institutions may wish to report separately certain additional research activities of their academic staff.  Therefore, as an exception to the above practice whereby financial data in the annual return is reported on the same basis as that used for the consolidated financial statements, institutions are permitted, under certain conditions, to report separately sponsored research that is granted to academic staff of the reporting institution, but conducted in entities that are not consolidated (see Section III .C.1 – Sponsored research). Institutions that report sponsored research data that is conducted in entities that are not consolidated are required to complete an affiliation report identifying each non-consolidated entity and the amount included in the annual return (see Section  III .C.6 – Part II ).

Given the different relationships existing across Canada between institutions and their affiliated hospitals, for example, this exception will also increase the comparability of research data across institutions.

For clarity, the financial data for a Charitable Foundation will only be included in the annual return if the Charitable Foundation is consolidated in the financial statements of the institution.

2. Funds

The financial data will be reported following a form of fund accounting. Fund accounting classifies resources for accounting and reporting purposes in accordance with activities or objectives as specified by donors, in accordance with regulations, restrictions, or limitations imposed by sources outside the institution, or in accordance with directions issued by the governing body of the institution.

A fund is an accounting entity with a self-balancing set of accounts for recording assets, liabilities, a fund balance, and changes in the fund balance. Funds have been identified as either unrestricted or restricted. Restricted funds, other than Endowment, account for resources that may be used for current purposes, but with some limitations imposed by external or internal sources.

For accounting and reporting purposes, institutions combine the funds with similar characteristics into distinct fund groups. The fund groups reported in the annual return, with a brief explanation of each, are as follows:

General operating is an unrestricted fund that accounts for the institution's primary operating activities of instruction and research, other than sponsored research.

Special purpose and trust is a restricted fund. The funds, including donations, may be restricted by external sources, or internally restricted by the institution's governing body, for purposes other than sponsored research (Sponsored research fund), or capital (Capital fund).

Sponsored research is a restricted fund that accounts for income and expenditures for all sponsored research. Amounts are separately reported for entities consolidated and entities not consolidated (see Section II .E.1).

Ancillary is an unrestricted fund that separately accounts for all "sales-producing" operations or "self-supporting" activities that are supplementary to the institution's primary operating activities of instruction and research.

Capital is a restricted fund that accounts for resources provided to the institution for capital purposes and not reported in any other fund.

Endowment is a restricted fund that accounts for the capitalization of externally or internally restricted amounts, primarily donations, which cannot be spent.

Section III .C.1 provides additional information and explanatory comments on each of the above funds.

3. Accrual Concept

As a general reporting practice, institutions follow the accrual, rather than the cash basis of accounting. The accrual concept refers to the method of recording transactions where income is reported in the period in which the income is considered to have been earned, rather than received; and expenditures, in the period in which the expenditures are considered to have been incurred, rather than disbursed. An example of the application of this concept to an income item is the accrual for interest earned, but not received; and, to an expenditure item, is the accrual for retroactive salary costs earned, but not paid.

Exceptions in the annual return to the accrual concept include –

  • the funds flow approach for reporting income in the Special purpose and trust, and Sponsored research funds (see Section II .E.4),
  • the funds flow approach for reporting income and expenditures for capital asset transactions (see Section II .E.4), and
  • the cash basis for reporting vacation pay, pension costs and future benefits (see Section II .E.7).

4. Funds Flow Approach

For specific types of activities, income will be reported in the annual return following a funds flow approach; that is, for both Special purpose and trust, and Sponsored research (see Section III .C.1), the funds are reported as income in the period in which the funds are received or receivable. The corresponding expenditures, on the other hand, are reported consistent with the accrual concept; that is, in the period in which the expenditures are incurred. For example, when an institution is awarded a research contract, the income is reported when the funds are received or receivable under the terms of the contract.

For CAUBO reporting purposes, income and the corresponding expenditures are to be reported in the same fund (see Section II .E.9).

Where an institution defers the income noted above in its audited financial statements, the difference between the funds flow approach and the deferral method must be a reconciling item in the Statement of Changes in Net Assets by Fund between the institution's annual return and its audited financial statements (see Section III .C.4 – line 11).

5. Guidance on Use of the Correct Fund

For all funds the matching principle applies; that is the revenue and related expenditure should be recorded in the same fund. it is not as straightforward to decide whether the revenue or expenditure source should dictate the fund where they are recorded. Depending upon the fund, there is not one method that says that expenditures should be recorded in the same fund as the revenue (expenditures follow revenues) or vice versa (revenues follow expenditures). Other reporting considerations have taken precedence over this consideration. However, while the applicable method may not be consistent across all funds, it is consistent within a given fund. The following shows the method to follow for each fund:

Operating Fund – expenditures follow revenues; Special Purpose & Trust Fund – expenditures follow revenues; Sponsored Research Fund – expenditures follow revenues; Ancillary Fund – expenditures follow revenues; Endowment Fund – revenues follow expenditures; Capital Fund – expenditures follow revenues.

6. Capital Assets

The uniform reporting practice in the annual return for capital expenditures is to follow the funds flow approach, rather than to capitalize and amortize. Funds received to acquire capital assets are reported as income in the period in which the funds are received or receivable. Funds used to acquire capital assets are reported as expenditures in the period in which the funds are paid or payable.

For CAUBO reporting purposes, capital expenditures are to be reported in the same fund as the corresponding income. Specifically, capital expenditures are only reported in the Capital fund when the corresponding income is reported in the Capital fund.

The difference between the funds flow approach and capitalized and amortized expenditures must be a reconciling item in the Statement of Changes in Net Assets by Fund between the institution's annual return and its audited financial statements (see Section III .C.4 – lines 9 and 10).

7.Vacation Pay, Pension Costs and Future Benefits

Vacation pay, pension costs and future benefits, including benefits arising as a result of early retirement, are to be reported on the cash basis. The cash basis refers to the method of recording transactions where expenditures are reported in the period in which cash is disbursed.

Where an institution accrues the expenditures noted above in its audited financial statements, the difference between the cash basis and the accrual basis must be a reconciling item in the Statement of Changes in Net Assets by Fund between the institution's annual return and its audited financial statements (see Section III .C.4 – lines 12 and 13).

8. Sales and Cost Recoveries

The practices followed by institutions in reporting sales and cost recoveries in their financial records vary significantly and, for the most part, are dependent upon the particular management information systems and business practices of the respective institutions.

For the annual return, as a general practice, sales and cost recovery amounts are to be reported at "gross", rather than "net". "Gross" means that the sales and the corresponding cost are reported as separate items. "Net" means that the sales and corresponding cost are combined, and the difference is reported as a separate item. Reporting amounts at "gross" provides users of the financial data with better information than reporting at "net".

Sales and cost recovery transactions can generally be classified as external sales, internal sales, external cost recoveries and internal cost recoveries.

  • (a) External sales and external cost recoveries – "third party" transactions, where the price to the external party is determined based on either the commercial value of the services or product, or the cost of the services or product. The price may or may not include a profit component.
  • (b) Internal sales – transactions between funds or functions, where the price to the internal party is determined based on either the commercial value of the services or product, or the cost of the services or product. The price includes a profit component. Internal sales exclude transactions based specifically on indirect or overhead costs. For the purposes of the annual return, internal sales will be categorized by those sales originating from ancillary services (see Section III .C.1 – Ancillary) and those sales originating from other funds or functions.
  • (c) Internal cost recoveries – the recovery, allocation, charge-out or transfer of costs between funds or functions. Internal cost recoveries refers specifically to indirect or overhead costs.

External sales, external cost recoveries and internal sales originating from ancillary services are to be reported as sale of services and products (see Section III .C.2 – line 25).

As an exception to reporting amounts at "gross", and also to avoid double counting of income and expenditures, the preferred method of reporting internal sales, other than those originating from ancillary services, is to report the amounts at "net". To report at "net", income in the fund or function selling the services or product is netted against the expenditures in that same fund or function. The fund or function purchasing the services or product reports the expenditure. Alternatively, where "netting" is not possible or feasible within a fund or function, the internal sales can be reported separately under an expenditure line item (a recovery) in both the fund or function selling the services or product and the fund or function purchasing the services or product (see Section  III .C.3 – line 20).

Internal cost recoveries are also to be reported in such a manner as to avoid double counting of expenditures. The preferred method is direct allocation – that is, by reducing the expenditure types in the fund or function from which the costs are allocated, offset with a corresponding increase in the same expenditure types in the fund or function to which the costs are allocated. This approach provides users with better functional comparisons of individual expenditure line items. Alternatively, where direct allocation is not possible or feasible, the internal cost recoveries can be reported separately under an expenditure line item (a recovery) in the fund or function from and to which the costs are allocated (see Section III .C.3 –line 20).

9. Interfund Transfers

Situations arise where in the normal course of operations, an institution reports income in one fund, but reports the corresponding expenditure in another fund. In such situations, the institution records a transfer from the fund in which the income was received, to the fund in which it is expended. This transfer is referred to as an interfund transfer.

These Guidelines encourage institutions to report, to the extent possible, income and the corresponding expenditure in the same fund. For example, capital expenditures are to be reported in the same fund as the corresponding income and investment income earned on trust and endowment funds is to be reported in the same fund as the corresponding expenditures. This approach provides users with better financial data to calculate statistics such as the relationship between income and expenditures, by fund.

The transfer of an operating surplus from the Ancillary fund to the General operating fund is an example of an interfund transfer. Other examples include interfund transfers approved by the institution's governing body. Interfund transfers are reported in the Statement of Changes in Net Assets by Fund (see Section III .C.4 – lines 5 and 8).

10. Gifts-In-Kind

Gifts-in-kind that are recorded in an institution's audited financial statements will be reported in the annual return as both an income and expenditure item. As an income and expenditure item, gifts-in-kind must be reported consistent with the CAUBO uniform reporting practices.

11. Internally Restricted Net Assets

Internally restricted net assets or fund balances are commonly referred to as appropriations or reserves. Changes in fund balances reported in an institution's financial statements occur in part as a result of approved transfers or the appropriation of funds for specific future purposes. For the annual return, an increase or transfer to appropriations should not be recorded as an expenditure, nor should a decrease or transfer from appropriations be recorded as income (see Section III .C.4 – line 19).

12. Borrowing and Principal Repayment

The borrowing and repayment of principal will not be reported as income or expenditure. Any such amounts, however, will be separately reported in the Statement of Changes in Net Assets by Fund (see Section III .C.4 – lines 6 and 7). However, interest payments will be reported as expenditures in the appropriate fund.

13. Full Costing of Ancillary Services

Ancillary services (see Section III .C.1 – Ancillary) should include all direct expenditures and cost allocations related to ancillary operations. Cost allocations, for example, should include a reasonable allocation for utility (unless the utility is an ancillary service) and plant maintenance, and for the institution's management and administrative support. Cost allocations to ancillary services are internal cost recoveries (see Section II .E.8) in the fund or function from which the costs are allocated.

14. Use of Estimates

To complete the annual return in accordance with these uniform reporting practices, costs may have to be allocated among funds and functions. Where cost allocations are required, the allocations can be based on best estimates.

15. Double Counting

In certain situations, an institution receives funds and subsequently disburses or transfers all or part of the funds to one or more related or affiliated entities that are included in the annual return. These entities could be included in the annual return for either reason noted in the uniform reporting practice on "Basis of Consolidation" (see Section II .E.1). In such situations, the institution submitting the annual return must ensure that total income and total expenditures are only reported once. The types of income to be reported should correspond to the original source of the funds. The types of expenditures to be reported should correspond to the final use of the funds. The intervening disbursements or transfers of funds between related or affiliated entities should not be reported. Furthermore, the institution must ensure that the income and expenditures are reported in the same fund (see Section II .E.9).

Also, care should be exercised in situations where a reporting institution receives funds and subsequently disburses or transfers all or part of the funds to other reporting member institutions of CAUBO . This is particularly important in the case of large research grants such as Networks of Centres of Excellence, where one institution, the administrative centre, is responsible for disbursing funds to other participating institutions. In such situations, the reporting institution should report the funds received "net" of the funds disbursed or transferred. This practice avoids double counting of income and expenditures when annual return data is aggregated for provincial, regional and national totals.

III . Detailed Instructions for Institutions Reporting Financial Data

This section provides detailed instructions for institutions reporting financial data. This is the "how-to" section for preparers to refer to when completing the annual return, and will be of interest to users who seek additional information on specific terms or particular line items used in the annual return. Preparers of the financial data should review the previous sections of the Guidelines before proceeding.

A. Comparable Financial Data

Normally, the criteria for placement of a particular income or expenditure item within a fund or function in the annual return is the same as that used by an institution in its financial statements or internal management reports. However, where the Guidelines specifically designate the placement of an item, the item must be shown under the designated heading regardless of the institution's practice. Consequently, the classification of activities or items of income and expenditure in the annual return may differ from the classification used by an institution in its financial statements or internal management reports. For example, health services and athletics are to be reported in the Student services function in the annual return (see Section III .C.5 – Student services) although they may be reported as ancillary services in the institution's financial statements or internal management reports.

The financial data reported by each institution will only be useful to users of the annual return when the data has been prepared consistently over time and is comparable to other institutions. In order to satisfy user information needs, preparers must comply with these Guidelines.

B. Annual Return

The detailed financial data requested in the annual return is reported in Tables 1 to 7. The contents of the annual return are as follows:

  • General Information and Instructions
  • Table 1. Income by Fund
  • Table 2. Expenditures by Fund
  • Table 3. Statement of Changes in Net Assets by Fund
  • Table 4. General Operating Expenditures by Function
  • Table 5. Affiliation Report
    • Part I : Separate Legal Entities Consolidated
    • Part II : Separate Legal Entities not Consolidated
  • Table 6. Other Federal Government Departments and Agencies – Grants and Contracts
  • Table 7. Provincial Government Departments and Agencies – Grants and Contracts

In certain situations, an institution may determine that while it has complied with the Guidelines, it has provided financial data that may not be comparable to other institutions. In such situations, the institution can provide either accompanying notes of explanation, or observations and comments in the space provided at the bottom of each Table. This additional information would be useful for Statistics Canada in its review of the annual return for reasonableness. Examples could be any "material" extraordinary or non-recurring income or expenditure item included in a fund and/or functional area.

An institution may also use the space provided at the bottom of each Table for any observations and comments that the institution wishes to make regarding items not covered in the annual return.

Preparers should recognize that users of the annual return are prepared to accept reasonable allocations where exact numbers are not available (see Section  II .E.14).

C. Definitions, Explanations and Examples

The funds are discussed first to assist the preparer to segregate the various income and expenditure items for reporting purposes. The financial data should be reported by fund in Tables 1, 2, 3, 6 and 7 of the annual return. Following the discussion of funds, the financial data to be reported on the applicable lines in each Table is discussed.

1. Funds

Fund accounting (see Section II .E.2) classifies resources for accounting and reporting purposes in accordance with activities or objectives as specified by donors, in accordance with regulations, restrictions, or limitations imposed by sources outside the institution (external restrictions) or in accordance with directions issued by the governing body (internal restrictions). Funds have been identified as either unrestricted or restricted. Restricted funds, other than Endowment, account for resources that may be used for current purposes, but with some limitations imposed by external or internal sources.

For accounting and reporting purposes, institutions combine the funds with similar characteristics into distinct fund groups. For the annual return, the fund groups are General operating, Special purpose and trust, Sponsored research, Ancillary, Capital, and  Endowment.

Preparers should note the following:

  • restricted funds include both external and internal restrictions,
  • income and expenditure within Sponsored research is separately reported for entities consolidated and entities not consolidated (see Section II .E.1),
  • interfund transfers should be minimized by reporting income and the corresponding expenditure in the same fund (see Section  II .E.9),
  • differences resulting from compliance with the uniform reporting practices in these Guidelines (see Section II .E) and the principles followed in the institution's financial statements will be reconciling items in the Statement of Changes in Net Assets by Fund (see Section III .C.4).

General operating is an unrestricted fund that accounts for the institution's primary operating activities of instruction and research, other than sponsored research. The general operating fund includes the costs of privately funded and non-credit programs.

Fund income includes provincial government grants (including research other than sponsored research), student tuition and other fees (for credit and non-credit courses), and income from private and other unrestricted sources. Fund income also includes investment income, if the corresponding expenditures are reported in the General operating fund.

Fund expenditures are for the general operating costs of the institution including instruction and research (other than sponsored research), academic support services, library, student services, administrative services, plant maintenance, external relations and other operating expenditures of the institution. Fund expenditures also include the purchase of capital assets, if the corresponding income is reported in the General operating fund.

Special purpose and trust is a restricted fund. The funds, including donations, may be restricted by external sources, or internally restricted by the institution's governing body, for purposes other than sponsored research (Sponsored research fund), or capital (Capital fund). Income is to be reported following the funds flow approach (see Section  II .E.4).

Fund income includes designated gifts, benefactions and grants. Fund income also includes investment income, if the corresponding expenditures are reported in the Special purpose and trust fund.

Fund expenditures include the purchase of capital assets, if the corresponding income is reported in the Special purpose and trust fund.

Sponsored research is a restricted fund that accounts for income and expenditures for all sponsored research. Amounts are separately reported for entities consolidated and entities not consolidated (see Section II .E.1). Income is to be reported following the funds flow approach (see Section II .E.4).

Fund income includes funds to support research paid either in the form of a grant or by means of a contract from a source external to the institution. Income sources include government, private industry and donors. The federal grant allocation for Indirect Costs of Research would be included here. The corresponding expenditures should be reported as an internal cost recovery between the Operating and Sponsored Research Funds, similar to the treatment of overheads. Fund income also includes investment income, if the corresponding expenditures are reported in the Sponsored research fund.

Fund expenditures include activity funded from Sponsored research income and exclude activity funded from the General operating fund. Fund expenditures include the purchase of capital assets, if the corresponding income is reported in the Sponsored research fund. Fund expenditures also include internal cost recoveries (see Section II .E.8).

Funds from Canada Foundation for Innovation, along with applicable matching funds, are to be reported as Sponsored research income. The corresponding expenditures, including the purchase of capital assets, are to be reported as Sponsored research expenditures.

Funding related to Canada Research Chairs are to be reported as Sponsored Research income. The corresponding expenditures, including the purchase of capital assets, are to be reported as Sponsored Research expenditures.

Within the Sponsored research fund, the first column in the applicable Tables is used to report income and expenditures for entities consolidated, and the second column, for entities not consolidated. Both columns combined represent the total Sponsored research reported by the institution. For the first column, "Entities Consolidated", reported amounts are based on the financial data of entities included in the consolidated financial statements of the institution.

For the second column, "Entities not Consolidated", institutions are permitted to separately report sponsored research, including hospital based medical research funding, that is granted to academic staff of the reporting institution, but conducted in entities that are not consolidated. Reporting of the sponsored research is permitted if all the following four conditions are met:

  • the entity not consolidated must be an affiliated institution as established by an affiliation agreement with the reporting institution. The term affiliated institution refers to all federated, affiliated and associated entities (see Section  III .C.6).
  • academic staff from the reporting institution lead the sponsored research project and conduct the research at the non-consolidated affiliated institution,
  • the financial data (income and expenditure) for the sponsored research are reported in the financial statements of the non-consolidated affiliated institution, and
  • the sponsored research would be reported in the Sponsored research fund had the research been conducted at the reporting institution, rather than at the affiliated institution.

In addition, for "Entities not Consolidated", the amounts reported as income (Table 1, line 27, column 4) must equal the amounts reported as expenditures (Table 2, line 24, column 4).

To provide financial data that is consistent and comparable, the income and expenditure items for sponsored research for entities not consolidated are to be reported in accordance with these Guidelines. Although this financial data has not been subject to audit by the reporting institution, there is an expectation that the data has adequately documented support.

Institutions that report sponsored research for such entities are required to

  • acknowledge and represent in the Transmittal Letter that the four conditions above have been met, and
  • complete Part II of Table 5 identifying each entity and the amounts reported in the annual return (see Section III .C.6).

Ancillary is an unrestricted fund that separately accounts for all "sales-producing" operations or "self-supporting" activities that are supplementary to the institution's primary operating activities of instruction and research. Ancillary services exist to provide goods and services to students, faculty, staff, and others. Ancillary services charge a fee directly related to, although not necessarily equal to, the cost of the goods or services.

Ancillary services typically include bookstores, food services (dining hall, cafeterias, vending machines), residences and housing, parking, university press, publishing, laundry services, property rentals, university facility rentals, theaters, and conference centers.

All sales, external and internal, from ancillary services are reported as income (see Section  II .E.8).

To report expenditures, full costing of ancillary services is required (see Section II .E.13). The preferred method of reporting internal cost recoveries or cost allocations is direct allocation, but where direct allocation is not possible or feasible, the internal cost recoveries can be reported under a separate expenditure line item (see Section II .E.8). Any capital items purchased directly from Ancillary income are to be reported in the Ancillary fund on the appropriate expenditure line.

Capital is a restricted fund that accounts for resources provided to the institution for capital purposes and not reported in any other fund. Income and expenditures are to be reported following the funds flow approach for capital assets (see Section II .E.6).

Fund income includes grants and related investment income, donations, and other resources made available to the institution by external funding sources, such as government and donors, specifically for capital purposes.

Fund expenditures include building programs, acquisitions of major equipment and furniture, major renovations and alterations, space rental and buildings, land and land improvements.

Because capital expenditures are to be reported in the same fund as the corresponding income, not all capital expenditures will be reported in the Capital fund. For example, funds from Canada Foundation for Innovation, along with applicable matching funds, are to be reported as Sponsored research income. The corresponding expenditures, including the purchase of capital assets, are to be reported as Sponsored research expenditures.

Endowment is a restricted fund that accounts for the capitalization of externally or internally restricted amounts, primarily donations, which cannot be spent.

Investment income generated by endowments may be used for various purposes, with these purposes often restricted by donors. Investment income should be reported in the same fund as the corresponding expenditures. Expenditures, excluding those incurred to earn investment income, are to be reported in an appropriate fund other than the Endowment fund.

Expenditures incurred to earn investment income are to be reported "net" of the investment income. Investment income that is used to preserve the capital value of the Endowment fund is reported as income in the Endowment fund.

2. Income by Fund (Table 1)

The funds described in Section III .C.1 are reported in columns 1, 2, 5, 6, 7 and 8 in Table 1, with the total of the funds reported in column 9. Column 5 reports the sub-total for the Sponsored research fund. Within Sponsored research, column 3 reports "Entities Consolidated" and column 4 reports "Entities not Consolidated".

The types of income to be reported in Table 1 are identified on the left-hand side of the Table. If there is uncertainty as to which line to use to report a type of income, report the income on the line best describing the activity. For example, government funds to pay tuition fees for participants in a non-credit program should be reported on line 13 (Non-credit tuition), rather than under government grants and contracts. Furthermore, where the designation of a particular type of income in this Table differs from that used by an institution in its financial statements or its internal management reports, the type of income must be shown per the Guideline instructions regardless of the institution's practice.

As a general reporting practice, institutions follow the accrual, rather than the cash basis of accounting (see Section II .E.3). For reporting income, exceptions to the accrual concept in the annual return include the funds flow approach for reporting funds received to acquire capital assets (see Section II .E.6) and for reporting income in the Special purpose and trust, and Sponsored research funds (see Section II .E.4).

Income includes gifts-in-kind that are recorded in an institution's audited financial statements (see Section II .E.10).

Borrowings will not be reported as income (see Section II .E.12). Any such amounts, however, will be separately reported on the Statement of Changes in Net Assets by Fund (see Section  III .C.4 – line 6).

The six major categories of income are –

  • government departments and agencies – grants and contracts,
  • tuition and other fees,
  • donations, including bequests
  • non-government grants and contracts,
  • investment, and
  • other (including sale of services and products, and miscellaneous).

(i)  Government departments and agencies – grants and contracts

Lines 1 to 11 include grants from, and contracts with, federal government departments and agencies, provincial government departments and agencies, and municipal governments. Grants and contracts from other provincial governments and from foreign governments are also reported in this category.

Government grants provide financial support to institutions and the grants may or may not be restricted.

Government contracts provide financial support to institutions under certain stipulations and conditions, including the provision of a deliverable product, such as a piece of equipment, a service, or a report. A contract normally includes provisions for institutions to recover certain indirect or overhead costs, with the contract specifying or documenting the basis for the calculation of the recoverable costs.

To avoid double counting of government grants and contracts, income must only be reported once. In other words, where an institution receives funds and subsequently disburses or transfers all or part of the funds to one or more related or affiliated entities that are included in the annual return, the transfers must be eliminated (see Section II .E.15).

Furthermore, and again to avoid double counting, where a reporting institution receives funds and subsequently disburses or transfers all or part of the funds to other reporting institutions of CAUBO , the funds received should be reported "net" of the funds disbursed or transferred (see Section II .E.15).

Federal

Lines 1 to 7 include all research grants, research contracts, grants and contributions from the Government of Canada and its departments and agencies, including the federal portion of capital and other grants that flow through a provincial government. Income received from the six major federal government agencies is reported on lines 1 to 6, as applicable.

The line items under "federal" are as follows:

Line 1 Social Sciences and Humanities Research Council (SSHRC)

Line 2 Health Canada

  • Income from Health Canada not reported under line 4 – Canadian Institutes of Health Research (CIHR) – should be reported in this line.

Line 3 Natural Sciences and Engineering Research Council (NSERC)

Line 4 Canadian Institutes of Health Research (CIHR)

Line 5 Canada Foundation for Innovation ( CFI )

  • CFI income is reported under the Sponsored Research fund.

Line 6 Canada Research Chairs

  • Funding for Canada Research Chairs is reported under the Sponsored Research Fund.

Line 7 Other federal (see Table 6)

  • Income from all other federal government departments and agencies is reported on this line with the details provided in Table 6 (see Section III .C.7). This would include grant allocations for the Indirect Costs of Research. A separate line is provided in Table 6 for Indirect Costs of Research.

Other

Lines 8 to 11 include all grants from, and contracts with, the province and its departments and agencies, municipal governments, other provinces, and foreign governments.

The line items under "other" are as follows:

Line 8 Provincial (see Table 7)

  • Income from provincial government departments and agencies, including provincial CFI matching grants, is reported on this line with the details provided in Table 7 (see Section III .C.8).
  • Provincial CFI matching income from the Ministry responsible for the institution is reported under the Sponsored research fund.

Line 9 Municipal

  • Examples of income to be reported on this line include grants from urban transit, communication and parking authorities.

Line 10 Other provinces

  • This line includes grants from, and contracts with, provinces other than the province with jurisdiction.

Line 11 Foreign

  • Examples of income to be reported on this line include grants from the National Endowment for Humanities, National Institutes of Health, and the National Science Foundation.

(ii) Tuition and other fees

The types of revenue (Lines 12 to 14) include credit course tuition, non-credit tuition and other fees.

Line 12 Credit course tuition

  • Credit courses are courses of instruction or programmed learning that are offered within a degree program; or, that may be granted status equivalent to a credit course within a degree program.
  • Credit courses are offered during the fall and winter sessions of a semester type operation, all three terms of a trimester operation and the year round operation of graduate schools and include intersession, spring session and summer session credit courses and credit extension.
  • Credit course tuition includes tuition and other mandatory fees related to the instruction of the courses, such as computer and laboratory fees.
  • Credit course tuition also includes fees for "make-up" or special courses that are related to the credit offerings of the institution, and fees for auditing in credit courses.
  • Credit course tuition should be reported on this line whether the cost of the credit course is subsidized or fully recoverable.

Line 13 Non-credit tuition

  • Non-credit programs are courses of instruction or programmed learning that are not credit courses (see line 12).
  • Non-credit tuition includes fees for lectures, courses and similar activities that are not recognized by the institution for the purpose of granting credit. Non-credit programs are usually offered through continuing education units.
  • Government funds to pay tuition for participants in a non-credit program should be reported as non-credit tuition, rather than as government grants and contracts.

Line 14 Other fees

  • Other fees include all compulsory and non-compulsory fees charged to students such as health services, athletics, library, applications, late registrations, lockers and transcripts. These fees would be reported under the General operating fund.
  • Other fees exclude fees collected by the institution acting in an agency capacity. An example would be student fees collected on behalf of student controlled and administered activities such as student councils or federations.

(iii) Donations, including bequests

Donations are a voluntary transfer of cash or negotiable instruments made without expectation of return or benefits of any kind to the donor. Bequests flow from wills. Donations, including bequests, are considered to be gifts for tax purposes. Amounts received that are eligible to be receipted as charitable donations for federal income tax purposes are to be reported on lines 15 to 17, as applicable.

Lines 15 to 17 categorize "donations, including bequests" by individuals, business enterprises, foundations and not-for-profit organizations.

In addition, donations designated for specific purposes and donations that cannot be spent are reported in the Endowment fund (see Section III .C.1 – Endowment). Donations also include gifts-in-kind that are recorded in an institution's audited financial statements (see Section II .E.10).

With the exception of circumstances outlined in the preceding paragraph, donations are to be reported in the same fund as the corresponding expenditures (see Section II .E.9).

Line 15 Individuals

  • This line includes families.

Line 16 Business enterprises

  • Business enterprises include unincorporated businesses as well as privately or publicly incorporated companies that are operated for profit and derive revenue mainly from the sale of goods and services. The common forms of unincorporated businesses are sole proprietorships and partnerships, and examples include farmers and professional practitioners.

Line 17 Not-for-profit organizations

This includes foundations and other not-for-profit organizations.

  • A foundation is an entity that can either be a corporation or a trust constituted and operated exclusively for charitable purposes. Funds contributed to an institution by a non-consolidated charitable foundation would be reported here.
  • Not-for-profit organizations include associations or societies, and examples include religious organizations, labour unions, professional organizations and fraternal societies.

(iv) Non-government grants and contracts

Non-government grants and contracts provide financial support under certain specific stipulations and conditions, including the provision of a deliverable product, such as a piece of equipment, a service, or a report. The amounts received by an institution are not considered as charitable donations for tax purposes and therefore are ineligible to be receipted as charitable donations for federal income tax purposes.

Lines 18 to 20 categorize "non-government grants and contracts" by individuals, business enterprises, foundations and not-for-profit organizations.

Line 18 Individuals

  • This line includes families.

Line 19 Business enterprises

  • Business enterprises include unincorporated businesses as well as privately or publicly incorporated companies that are operated for profit and derive revenue mainly from the sale of goods and services. The common forms of unincorporated businesses are sole proprietorships and partnerships, and examples include farmers and professional practitioners.

Line 20 Not-for-profit organizations

This includes foundations and other not-for-profit organizations.

  • A foundation is an entity that can either be a corporation or a trust constituted and operated exclusively for charitable purposes.
  • Not-for-profit organizations include associations or societies, and examples include religious organizations, labour unions, professional organizations and fraternal societies.

(v) Investment income

Investment income includes income from dividends, bonds, mortgages, short-term notes and bank interest. Bond interest would include an accrual for stripped bonds (see Section II .E.3). Investment income also includes realized and unrealized gains and losses on investment transactions, if the gains and losses are reported in the audited financial statements, regardless of how investments have been designated by the institution (held for trading or not).

Investment income excludes income from a non-consolidated charitable foundation. Income from a non-consolidated charitable foundation should be reported on line 17 (Not-for-profit organizations).

Included in this section are endowment and other investment income (Lines 21 and 22).

Line 21 Endowment

  • Investment income earned on endowment funds is reported on this line under the same fund as the corresponding expenditures.
  • Investment income earned on endowment funds and used to preserve the capital value of the Endowment fund is reported on this line under the Endowment fund.
  • Expenditures incurred to earn investment income, such as the cost of an investment manager(s) to manage the endowment funds, are to be reported "net" of the investment income.

Line 22 Other investment

  • Investment income earned on all funds other than endowment funds is reported on this line under the same fund as the corresponding expenditures.
  • Other investment income also includes charges for deferred or installment payments and for unpaid student tuition and other fees.
  • Any significant non-recurring items should be explained by way of accompanying notes or in the observations and comments section at the bottom of Table 1.

(vi) Other

  • Other income (Lines 23 and 24) includes sale of services and products, and miscellaneous.

Line 23 Sale of services and products

  • This line includes external sales and external cost recoveries (see Section II .E.8).
  • External sales and external cost recoveries include sales to outside organizations, such as those for laboratory tests, space rental, utilities and incidental income (including athletic gate receipts, parking fees, conferences and various medical clinics).
  • This line also includes rental income from residences and parking.
  • Payments received from non-consolidated federated or affiliated entities for the provision of instructional, administrative or other services are reported as sale of services and products.
  • For ancillary services (see Section III .C.1 – Ancillary), this line includes both external and internal sales (see Section II .E.8).
  • Internal sales, other than those originating from ancillary services, and internal cost recoveries are not reported as income.

Line 24 Miscellaneous

  • Miscellaneous income includes commissions, royalties and fees from the use of institution owned rights or properties, or fees for services rendered. Miscellaneous also includes library and other similar fines, rentals, net gain or loss on sale of fixed assets and any type of income not identified in the other categories of income.
  • Payments received from non-consolidated federated or affiliated entities for the provision of instructional, administrative or other services are reported as sale of services and products (line 23).

3. Expenditures by Fund (Table 2)

The funds described in Section III .C.1 are reported in columns 1, 2, 5, 6, 7 and 8 in Table 2, with the total of the funds reported in column 9. Column 5 reports the sub-total for the Sponsored research fund. Within Sponsored research, column 3 reports "Entities Consolidated" and column 4 reports "Entities not Consolidated".

The types of expenditures to be reported in Table 2 are identified on the left-hand side of the Table. Where the designation of a particular expenditure in this Table differs from that used by an institution in its financial statements or its internal management reports, the expenditure must be shown under the designated Table heading regardless of the institution's practice.

As a general reporting practice, institutions follow the accrual, rather than the cash basis of accounting (see Section II .E.3). For reporting expenditures, exceptions to the accrual concept in the annual return include the funds flow approach for reporting funds used to acquire capital assets (see Section  II .E.6) and the cash basis for reporting vacation pay, pension costs and future benefits (see Section II .E.7).

Expenditures include gifts-in-kind that are recorded in an institution's audited financial statements (see Section II .E.10).

The repayment of principal will not be reported as an expenditure (see Section II .E.12). Any such amounts, however, will be separately reported in the Statement of Changes in Net Assets by Fund (see Section III .C.4 – line 7).

Lines 1 to 20 report expenditures that are generally recurring, with a sub-total for lines 1 to 20 reported on line 21. Lines 22 and 23 report significant periodic expenditures such as those for buildings, land and land improvements (line 22) and unusual or non-recurring expenditures, referred to as lump sum payments (line 23), such as those for special assisted early retirement programs. The total of all expenditures is reported on line 24.

The types of expenditures to be reported in Table 2, by line, are as follows:

Salaries and wages

Salaries and wages are categorized as academic salaries (lines 1 and 2) and other salaries and wages (line 3). Academic salaries are reported by academic ranks (line 1) and by other instruction and research (line 2).

The following types of payments are to be reported as salary and wage expenditures:

  • compensation payments, such as payments for salary continuance during sick leave or maternity leave,
  • severance payments as a result of terminations in the normal course of business, and
  • vacation pay (see Section II .E.7).

Certain lump sum payments for current and future fiscal periods to employees who have terminated employment with the institution are reported on an accrual basis as lump sum payments (line 23).

With the exception of vacation pay, the amounts to be reported as salaries and wages in the annual return are to be calculated following the same practices as those used by the institution for its audited financial statements.

Academic salaries

Academic salaries are reported by academic ranks and by other instruction and research.

Line 1 Academic ranks

  • This line includes payments to both full and part time staff members who hold an academic rank at the reporting institution and are engaged in instruction and research activities.
  • The academic ranks include deans, professors, associate professors, assistant professors and lecturers.
  • Academic salaries also include payments to staff members in the academic ranks for various types of leave such as administrative, academic or sabbatical.

Line 2 Other instruction and research

  • This line includes payments to both full and part time staff and non-staff members without academic rank at the reporting institution, but who are engaged in instruction and research activities.
  • The staff and non-staff members include instructors, tutors, markers, laboratory demonstrators, teaching assistants, research assistants, invigilators, clinical assistants, post-doctoral fellows, and others.
  • Other instruction and research salaries also include payments made to graduate and undergraduate students undertaking instruction and research activities.

Line 3 Other salaries and wages

  • This line includes salaries and wages not reported on lines 1 and 2. Specifically, other salaries and wages includes payments to all full and part time non-instructional (support) staff including among others, technicians, teaching and research laboratory technicians, clerical and secretarial, professional and managerial, janitorial, trades and maintenance.
  • Other salaries and wages also includes payments to individuals who may hold an academic rank, or equivalent thereto, but are engaged in activities other than instruction and research. Examples of such individuals include the president, vice-presidents, certain professional librarians and computing center personnel.

Line 4 Benefits

  • Pension costs and future benefits, including benefits arising as a result of early retirement, are to be reported on the cash basis (see Section  II .E.7). Otherwise, the amounts to be reported as benefits in the annual return are to be calculated following the same practices as those used by the institution for its audited financial statements.
  • Benefits include the cost of an institution's contributions (with respect to salaries) for pensions (including payments for actuarial deficiencies and past service liability), group life insurance, salary continuance insurance, dental plans, workers' compensation, health taxes, tuition remission, employment insurance and other costs of an employee benefit programs.
  • Benefits also include the cost of benefits paid during early retirement periods, as well as the cost of post retirement benefits.
  • Whenever an institution pays a premium or sets aside a negotiated amount for an employee, these amounts should be included as Benefits.
  • Memberships or other perquisites of employment are not reported as Benefits.

Line 5 Travel

  • Travel includes expenditures on recruitment, travel, moving and relocation of staff, field trips and all other types of travel necessary for the operation of the institution.

Line 6 Library acquisitions

  • Library acquisitions include all purchases of, and access to (including electronic access), books, periodicals and other reference materials for the institution's main branch and faculty or departmental libraries.
  • Cost of binding may also be included if normally considered part of the acquisition cost.

Line 7 Printing and duplicating

  • This line includes expenditures that would normally be consumed in the fiscal year such as printing, duplicating, photocopying, reproductions, illustrations, publishing and the related supplies.

Line 8 Materials and supplies

  • Materials and supplies include expenditures that would normally be consumed in the fiscal year such as sports supplies, stationery, computer and other office supplies.
  • Also included are material and supplies for teaching and laboratories. Laboratory supplies include chemicals, instruments, animals, feed and seed.
  • Small dollar value equipment and computer software items should be reported under furniture and equipment purchase (line 18).

Line 9 Communications

  • Communications includes telephone, data communications, mailing and courier, but excludes expenditures reported as equipment rental and maintenance (line 19).
  • Telephone includes watts lines, line services, long distance and other charges.

Line 10 Other operational expenditures

  • This line includes space rental, property taxes, institutional membership fees, insurance, meals, advertising and promotion, and doubtful accounts.
  • Space rental includes the cost of renting space and land on a long-term basis.
  • Property taxes include all taxes paid directly to municipalities by the institution, whether assessed on property values or based on student population.
  • Institutional membership fees include fees paid by the institution to organizations such as AUCC and CAUBO .
  • This line includes all other expenditures that are not reported elsewhere.

Line 11 Utilities

  • Utilities include expenditures for items such as electricity, water, natural gas, fuel and sewer.
  • Utilities also include the generating costs for electricity, steam, water, and natural gas.

Line 12 Renovations and alterations

  • This line includes expenditures for renovations and alterations to the existing space of the institution, whether the expenditures are internally performed or external contracted.

Line 13 Scholarships, bursaries and prizes

  • This line includes payments to students (except those for which the student is required to perform service for the payment) such as those for fee remission, prizes and awards.
  • Payments for which the student is required to perform service for the payment are reported as other instruction and research (line 2), and include payments to graduate and undergraduate students who are instructors, tutors, markers, laboratory demonstrators, teaching assistants, research assistants, invigilators, clinical assistants, postdoctoral fellows, and others.

Line 14 Externally contracted services

  • This line includes all expenditures for services contracted to external agencies except for renovations and alterations (line 12), professional fees (line 15), equipment rental and maintenance (line 19), and buildings, land and land improvements (line 22).
  • Examples of expenditures to be included are cleaning contracts, security services, snow removal and similar time and material contracts, and food services.
  • Where food services are contracted, the contract amount in total should be shown on this line and not as cost of goods sold (line 16) or any other expenditure types, even though the contractor may provide a breakdown of costs.

Line 15 Professional fees

  • Professional fees include all fees paid to legal counselors (including retainers for the negotiations of collective agreements), auditors, and computer, human resource and other consultants.
  • This line excludes consulting fees for renovations and alterations (line 12), equipment rental and maintenance (line 19), and buildings, land and land improvements (line 22).

Line 16 Cost of goods sold

  • Cost of goods sold is to be used where an inventory method of accounting is normally employed, (e.g. bookstore, food services) and should include the laid down cost of goods purchased for resale only. The remaining costs of operating the service, such as salaries and supplies, are to be shown in their respective expenditure types.
  • Where a service is externally contracted, particularly for ancillary services, the total costs of the contract should be included in externally contracted services (line 14). For example, contracted food services are to be reported on line 14, under the Ancillary fund.
  • The cost of goods sold is to be reported under the same fund as the income from the sale of the product (see Section III .C.2 – line 25).

Line 17 Interest

  • This line includes all interest expenditures to service debts of the institution. Examples include bank interest, mortgage or debenture interest and related charges, and the interest component of installment or lease payments.
  • Repayments of principal such as principal reductions on loans, mortgages, debentures or repayable grants are not reported as expenditures (see Section II .E.12).

Line 18 Furniture and equipment purchase

  • This line includes laboratory equipment (other than consumables), computing equipment and computer software packages, administrative equipment and furnishings (including carpets and drapery), copying and duplicating equipment, and maintenance equipment. Installation expenditures for the above items are to be included as part of their cost.
  • This line also includes installment payments and payments under lease purchase contracts, where the lease is a capital lease for accounting purposes. The interest component of any such payments should be reported on line 17.
  • This line includes small dollar equipment and computer software items that would normally be expensed in the accounting records of the institution.
  • Furniture and equipment purchases are reported under the same fund as the corresponding income (see Section II .E.6). For example, purchases made from CFI grants are reported under Sponsored research (see Section III .C.1 – Sponsored research). Purchases made or to be made from current or future ancillary services income are to be reported under Ancillary (see Section III .C.1 – Ancillary).
  • Amortization is not reported as an expenditure, but is included as a reconciling item in the Statement of Changes in Net Assets by Fund (see Section III .C.4 – line 10).
  • Provisions for the replacement of furniture and equipment are considered to be transfers to appropriation or reserve accounts; consequently, such provisions are not to be reported as expenditures (see Section II .E.11).

Line 19 Equipment rental and maintenance

  • This line includes all rental and maintenance expenditures for furniture and equipment including laboratory equipment (other than consumables), administrative equipment and furnishings (including carpets and drapery), copying and duplicating equipment, computing equipment, maintenance equipment and telephone equipment.
  • This line also includes lease purchase contracts, where the lease is an operating lease for accounting purposes.
  • This line also includes expenditures for equipment repairs and maintenance contracted to external agencies.

Line 20 Internal sales and cost recoveries

  • The preferred method of reporting internal sales, other than those originating from ancillary services, is to report the amounts at "net" (see Section II .E.8). The preferred method of reporting internal cost recoveries is direct allocation (see Section II .E.8). Where the preferred method is not possible or feasible, this expenditure type can be used, but when it is used, the internal sales and cost recoveries for all funds, when added together, must equal zero.
  • This line includes internal sales, other than those originating from ancillary services, and internal cost recoveries (see Section II .E.8).
  • Internal sales originating from ancillary services are to be reported as sale of services and product (see Section III .C.2 – line 25).
  • Common examples of internal cost recoveries include the overhead recovery of administrative costs and the indirect costs of research between the General Operating fund and the Ancillary and Sponsored research funds, and the overhead recovery of utility (unless the utility is an ancillary service) and maintenance costs between the General operating fund and the Ancillary fund.
  • To provide better functional comparisons of types of expenditures, institutions are asked to minimize the use of this line to the extent possible.

Line 21 Sub-total

  • This line is the sub-total of all expenditures reported on lines 1 to 20.

Line 22 Buildings, land and land improvements

  • Buildings include all expenditures that are normally considered part of the construction cost as well as costs incurred during the construction period such as utilities. Land and land improvements include acquisition costs and site preparation such as landscaping, sewers, tunnels and roads. All fees and planning costs related to buildings, land and land improvements are also included.
  • Furniture and equipment purchases are reported on line 18.
  • The expenditures for buildings, land and land improvements are reported under the same fund as the corresponding income (see Section II .E.6). For example, purchases made from CFI grants are reported under Sponsored research (see Section III .C.1 – Sponsored research). Purchases made or to be made from current or future ancillary services income are to be reported under Ancillary (see Section III .C.1 – Ancillary).
  • Amortization is not reported as an expenditure, but is included as a reconciling item in the Statement of Changes in Net Assets by Fund (see Section III .C.4 – line 10).
  • Provisions for the replacement of buildings are considered to be transfers to appropriation or reserve accounts; consequently, such provisions are not to be reported as expenditures (see Section II .E.11).

Line 23 Lump sum payments

  • This line includes certain lump sum payments for current and future fiscal periods to employees who have terminated employment with the institution. The characteristics of the payments are such that similar transactions or events are not expected to occur frequently over several years, or do not typify normal business activities of the institution.
  • Lump sum payments are reported on an accrual basis.
  • Examples of lump sum payments include payments under downsizing or special assisted early retirement programs.
  • Severance payments as a result of terminations in the normal course of business are reported as salary and wage expenditures (lines 1 to 3).

4. Statement of Changes in Net Assets by Fund (Table 3)

The Statement of Changes in Net Assets by Fund identifies, for each fund in the annual return, the changes between the net asset balances at the beginning of the year and the net asset balances at the end of the year. The changes between the beginning and ending net asset balances are more than the difference between total income (Table 1, line 27) and total expenditures (Table 2, line 24). The changes also result from the addition and deduction of transactions that are neither income nor expenditures. These transactions are reported on lines 4 to 7 and include prior year adjustments, interfund transfers, borrowings, and the principal portion of debt repayments.

In addition, the statement identifies the uniform reporting practices that cause differences between the institution's annual return and its audited financial statements (see Section II .D). While the specific types of items causing the differences may vary among institutions, the number of such items is relatively few. These items are reported on lines 8 to 15. The uniform reporting practices that cause the differences include funds flow (see Section II .E.4), capital assets (see Section II .E.6), and vacation pay, pension costs and future benefits (see Section II .E.7).

The Statement of Changes in Net Assets by Fund, then, reconciles the net asset balances at the beginning of the year with the net asset balances at the end of the year. As more clearly indicated in the details for lines 16 to 21, both the beginning and ending net asset balances are based on information reported in the institution's audited financial statements.

The details of each line in the statement are as follows:

Line 1 Net asset balances, beginning of year

  • The net asset balances, by fund, at the beginning of the year must equal line 16 of the prior year's return.

Line 2 Income (Table 1, line 27)

  • This line must equal the total reported in Table 1 (Income by Fund), line 27.

Line 3 Expenditures (Table 2, line 24)

  • This line must equal the total reported in Table 2 (Expenditures by Fund), line 24.

Line 4 Prior year adjustments

  • This line should be used infrequently and generally only when the net asset balances reported in the audited financial statements at the end of the prior year have been subsequently adjusted.
  • An example of a prior year adjustment includes a retroactive change in accounting policies.

Line 5 Interfund transfers

  • Institutions have been encouraged to minimize interfund transfers in the annual return by reporting income and the corresponding expenditures under the same fund (see Section  II .E.9). For example, capital expenditures are to be reported under the same fund as the corresponding income. Investment income earned on trust and endowment funds is to be reported under the same fund as the corresponding expenditures.
  • Where the amount of an interfund transfer is not material to an institution's reported financial data, the amount should be restated to an appropriate fund.
  • After following the above guidelines, any remaining interfund transfers would be reported on this line. An example would be the transfer of an operating surplus from the Ancillary fund to the General operating fund. Other examples include transfers approved by the institution's governing body.
  • The total in column 9 on line 5 must equal 0.

Line 6 Add: borrowings

  • This line reports debt borrowings (see Section II .E.12).

Line 7 Deduct: principal portion of debt repayments

  • This line reports repayment of principal (see Section II .E.12).
  • Repayments of principal include principal reductions on loans, mortgages, debentures or repayable grants.
  • Interest to service debts of the institution is reported as an expenditure (see Section III .C.3 – line 17).

Line 8 Interfund reallocations

  • Normally, the criteria for placement of a particular income or expenditure item within a fund in the annual return is the same as that used by an institution in its financial statements or internal management reports. However, where the Guidelines specifically designate the placement of an item, the item must be shown under the designated heading regardless of the institution's practice. Consequently, items may be classified under one fund for the purposes of an institution's annual return, but a different fund in its audited financial statements or internal management reports (see Section III .A).
  • In addition, institutions have been encouraged to minimize interfund transfers in the annual return by reporting income and the corresponding expenditures under the same fund (see Section II .E.9). For example, capital expenditures are to be reported under the same fund as the corresponding income. Investment income earned on trust and endowment funds is to be reported under the same fund as the corresponding expenditures. To the extent interfund transfers have been minimized, items may be classified under one fund for the purposes of the institution's annual return, but a different fund in its audited financial statements.
  • Differences in ending net asset balances, by fund, between the annual return and audited financial statements resulting from the above guidelines, can be adjusted on line 8. Column 9, the total for all interfund reallocations reported on line 8, must equal 0.

Line 9 Add: capital expenditures

  • Funds used to acquire capital assets have been reported as expenditures in the annual return based on the funds flow approach (see Section  II .E.6). This line reports the difference between capital asset expenditures as reported in the annual return and the same amounts that have been capitalized during the year in the audited financial statements.
  • This line also includes differences that result from installment payments and payments under lease purchase contracts where the lease is a capital lease for accounting purposes (see Section III .C.3 – line 18).
  • The differences that result from amortizing capital assets are reported on line 10.

Line 10 Deduct: amortization

  • Funds used to acquire capital assets have been capitalized in the audited financial statements and amortized on an annual basis (see Section  II .E.6). This line reports the amortization expense that has been recorded in the audited financial statements.
  • The differences that result upon the acquisition of capital assets are reported on line 9.

Line 11 Add or deduct: deferred income

  • Certain restricted income not expended in the year is reported in the annual return following a funds flow approach (see Section II .E.4). This line reports the difference between amounts that have been reported as income in the annual return following a funds flow approach and the same amounts that have been reported as income in the audited financial statements following the deferral method.

Line 12 Add or deduct: pension costs and vacation pay accrual

  • Vacation pay and pension costs are reported in the annual return on a cash basis (see Section  II .E.7). This line reports the difference between amounts that have been reported as expenditures in the annual return on a cash basis and the same amounts that have been reported as expenditures in the audited financial statements on an accrual basis.

Line 13 Add or deduct: future cost of employee benefits

  • Future cost of employee benefits are reported on this line and represent employee benefit costs not already reported in the annual return on a cash basis. An example would be the cost of future benefits on early retirement programs.

Line 14 Add or deduct: related or affiliated entities

  • In certain situations, the reporting institution may report financial data for a related or affiliated entity in its audited financial statements, but not report the same data in its annual return (see Section III .C.6 – Part I ). In such situations, the change in the net asset balances of the related or affiliated entity between the beginning of the year and the end of the year should be reported on this line.

Line 15 Add or deduct: other

  • This line reports any other amounts such as the net book value of asset disposals where there are differences between the institution's annual return and its audited financial statements.
  • For amounts reported on this line, provide details in the "Observations and Comments" space at the bottom of the Table.

Line 16 Net asset balances, end of year

  • For a number of institutions, the audited financial statements may not specifically disclose net asset balances, by fund, in a format similar to the annual return. As a minimum, total net asset balances reported in column 9 should equal the total net assets reported in the institution's audited financial statements.
  • In certain situations, the reporting institution will report sponsored research in Column 4 that is attributable to the institution, but conducted through entities that are not consolidated. In such situations, the amount reported for column 4, on line 16, must equal 0 (see Section III .C.1 – Sponsored research).
  • The net asset balances, by fund, reported on this line, should equal the net asset balances, by fund, reported on line 21.
  • The net asset balances, by fund, reported on this line, should also equal the net asset balances, by fund, at the beginning of the next year; that is, line 16 of the current year's annual return must equal line 1 of next year's annual return.

Net asset balances are comprised of:

The net asset balances reported on lines 17, 18, 19 and 20 agree with certain net asset balances in the institutions audited financial statements.

Line 17 Unrestricted net assets

  • The net asset balance in column 9 should equal the accumulated surplus or deficit reported in the institution's audited financial statements.

Line 18 Investment in capital assets

  • Investment in capital assets represents the funds expended to acquire capital assets, less accumulated amounts amortized over the estimated useful lives of the related capital assets. The funds expended are reduced by amounts financed by long term debt and, where applicable, deferred capital contributions. These funds are not available for other purposes since they have been invested in capital assets.
  • The net asset balance in column 9 should equal the investment in capital assets reported in the institution's audited financial statements.

Line 19 Internally restricted net assets

  • An increase or transfer to appropriations should not be recorded as an expenditure, nor should a decrease or transfer from appropriations be recorded as income (see Section II .E.11).
  • The net asset balance in column 9 should equal the internally restricted appropriations, including internal endowments, reported in the institution's audited financial statements.

Line 20 Externally restricted net assets

  • The net asset balance in column 9 should equal the externally restricted funds, including external endowments, reported in the institution's audited financial statements.

Line 21 Net asset balances, end of year

  • The net asset balances, by fund, reported on this line, should equal the net asset balances, by fund, reported on line 16.

5. General Operating Expenditures by Function (Table 4)

Expenditures by Fund (see Section III .C.3) and this section of the Guidelines are very similar in that types of expenditures are identified on the left-hand side of both Tables. Table 2, however, is organized by fund, and Table 4 is organized by operational or functional areas, within the General operating fund, that represent the major areas of institutional activity. The functions are Instruction and non-sponsored research, Non-credit instruction, Library, Computing and communications, Administration and academic support, Student services, Physical plant and External relations. These functions are reported in columns 1 to 8, with the total of the functions reported in column 9. The amounts in Column 9 should be identical to the amounts in Table 2, Column 1 (General operating).

This section provides details to assist preparers to segregate, by function, the various activities and types of expenditures under the General operating fund. Unless otherwise indicated, the definitions, explanations and examples presented in Section  III .C.3 for types of expenditures also apply to this section. In addition, as noted previously, where the designation of a particular expenditure in this Table differs from that used by an institution in its financial statements or its internal management reports, the expenditure must be shown under the designated Table heading regardless of the institution's practice. For example, health services and intramural and intercollegiate athletics are to be reported under the Student services function although they may be reported as ancillary services in the institution's financial statements or its internal management reports.

In reporting General operating fund expenditures by function, preparers should be familiar with the uniform reporting practices (see Section II .E). In particular, preparers should be familiar with the practices on internal and external cost recoveries (see Section II .E.8) and use of estimates (see Section II .E.14).

The functions in the General operating fund are as follows:

(i) Instruction and non-sponsored research

The Instruction and non-sponsored research function in the General operating fund includes all direct costs of faculties, academic departments (including salaries of academic deans and their offices), graduate school, summer school, credit extension, and other academic functions and expenditures attributable to this function.

(ii) Non-credit instruction

The Non-credit instruction function in the General operating fund includes lectures, courses and similar activities that are not recognized by the institution for the purpose of granting credit. Non-credit programs are usually offered through continuing education units. Normally where there is non-credit tuition income reported on line 13 under the General operating fund in Table 1, the corresponding expenditures (not necessarily equal to the income) will be reported under this function.

(iii) Library

The Library function in the General operating fund includes the institution's Archives and other activities related to the institution's main branch and faculty or departmental libraries. The expenditures include the salary and wage costs of providing the library services as well as the cost of books and periodicals.

(iv) Computing and communications

The Computing and communications function in the General operating fund includes only the activities of centralized computing and communication facilities.

A centralized computing facility refers to computer related activities and resources that have been organized under the management of a central administration. The computing facility is usually seen as an institutional resource that is available on an institution-wide basis and is the most effective way of providing certain services supportive of the institution's research and administrative activities. Such a facility usually results from factors including economies of scale, a large number of users who require a wide variety of services, and a high degree of technical expertise required in computer operations.

This function does not include the activities of local or decentralized stand-alone computer installations that are under the management of, and were established for the main purpose of providing services to, a single division or department. The expenditures for decentralized computing facilities are to be included under the related functions and funds, as appropriate.

A centralized communications facility includes the costs of telephone equipment rental, service, acquisition and switchboard, including related personnel and other costs. The expenditures for decentralized communications facilities are to be included in the related functions and funds, as appropriate.

If an institution employs a charge-out system for central computing time or communications equipment usage, expenditures should be combined and reported under this function.

Any sales to, or recoveries from, other functional areas or funds, or outside users, are considered to be either an internal or external cost recovery and are to be reported according to the uniform reporting practice for internal and external cost recoveries (see Section II .E.8).

(v) Administration and academic support

The Administration and academic support function in the general operating fund covers expenditures in the two broad areas of academic support and other support services. Other support services include administration. These areas are combined and reported in Table 4 under Administration and academic support.

The academic support area of the Administration and academic support function includes all activities provided by an institution in direct support of Instruction and non-sponsored research. This area includes the following types of activities:

  • the positions of vice-president academic and research (or their equivalents) and their offices
  • faculty and instructional support services
  • research administration (including grants and contracts administration)
  • registrar's and graduate students office (including calendars, admissions, student records and related reporting)
  • convocation and ceremonies
  • co-op program administration
  • central animal services
  • central shops for instruction and research (machine shop, glass blowing, electronics shop)
  • distance education support
  • instructional technology and audio visual services
  • academic class scheduling

The administration area of the Administration and academic support function includes the following activities:

  • administration, planning and information costs and activities associated with the positions of president and vice-president (or their equivalents) and their offices, except for the positions of vice-president academic and research (or their equivalents) and their offices, which are included in the academic support area. Administrative costs for activities such as fundraising, development, alumni and external communications are included in the external relations area.
  • finance, including investment management, internal audit and accounting
  • human resources (personnel)
  • institutional research
  • board and senate secretariat
  • printing and duplicating services

Specific types of expenditures in the administration area include the following:

  • professional fees including legal, audit, human resource and other consulting fees that are not specifically attributable to another function. Computer consulting fees are included if the computing facilities are decentralized.
  • general university memberships including AUCC and CAUBO
  • liability and E & O insurance (fire, boiler and pressure vessel, and property insurance are reported under the Physical plant function).

The appropriate reporting for computing, communications, purchasing, receiving and stores will depend upon whether the institution operates with centralized or decentralized facilities. If the institution has centralized facilities for computing and communications, the activities should be reported under the Computing and communications function. If the institution has centralized facilities for purchasing, receiving and stores, the activities should be included in the administration area of the Administration and academic support function. If any of computing, communications, purchasing, receiving or stores is decentralized, then these activities should be included under the related functions and funds, as appropriate.

(vi) Student services

The Student services function in the General operating fund includes the cost of services (other than direct teaching, research and administrative services) provided to students by the institution. Generally, these services will include:

  • the dean of students and the dean's office
  • counseling and chaplaincy services
  • career guidance and placement services
  • intramural and intercollegiate athletics (not physical education)
  • student health services
  • student accommodation services (not residences)
  • student transportation services
  • student financial aid administration
  • bursaries, scholarships and prizes
  • grants to student organizations, including the student union
  • student programs, including music, drama and student center
  • student day care center
  • any other student services, social or cultural activities funded by the institution

These services may be provided from General operating fund income in whole, or in part by a specific fee included in the student incidental fee structure. Where an institution acts in an agency capacity, however, and collects student fees on behalf of student controlled and administered activities such as student councils or federations, the fees collected by the institution are to be excluded from income of the institution. The amount turned over to the benefit of the student council or federation is to be excluded from expenditures of the institution.

(vii) Physical plant

The Physical plant function in the General operating fund includes expenditures related to the physical facilities of the institution. The expenditures include the physical plant office, space planning, maintenance of buildings and grounds, custodial services, utilities, vehicle operations, security and traffic, repairs and furnishings, renovations and alterations, mail delivery services, long-term space and property rental, and municipal taxes (including those for which compensatory grants are received from government).

Physical plant also includes fire, boiler and pressure vessel, and property insurance. All other insurance is reported in the administration area of the Administration and academic support function.

(viii) External relations

The external relations area includes all activities provided by an institution in support of ongoing external relations. These activities include fundraising, development, alumni, public relations and public information or external communications. The related administrative costs from the office of the vice-president(s), or equivalent, responsible for one or more of these activities should be included in this area.

6. Affiliation Report (Table 5)

For each reporting institution, there could be one or more separate legal entities that are related or affiliated to the reporting institution and for which financial data is included in the annual return (see Section II .E.1).

To allow users to better understand the contents of the annual return and its limitations, each reporting institution is required to identify and provide additional information in Table 5 for each such entity.

Depending upon an institution's circumstances, two parts of the affiliation report may be required. The first part is for entities consolidated in the institution's audited financial statements; the second is for entities not consolidated in the institution's audited financial statements, but for which some data is nevertheless included in the annual return.

(i) Part I : Separate Legal Entities Consolidated

Normally, an institution will report financial data in the annual return on the same basis as that used for its consolidated financial statements. This means that the financial data for a separate legal entity that is consolidated in the audited financial statements will be included in the annual return.

As an exception, there could be financial data for an affiliated entity that is included in the institution's consolidated financial statements, but not reported in the annual return. This exception could arise where an affiliated entity is also submitting an annual return as a member institution of CAUBO .

Information to be provided in the affiliation report for "entities consolidated" is based on the separate legal entities consolidated in the institution's financial statements and includes –

  • Legal name of affiliated institution
  • Category of affiliation – columns 1 to 7. Indicate the category of affiliation with an "x" in the appropriate column. For further information see the section below on Categories of Affiliation.
  • Basis of reporting – columns 8 and 9. Indicate with an "x" in the appropriate column whether the separate legal entity is included ( I ) in the annual return (the norm) or excluded (E) from the annual return (the exception).

(ii) Part II : Separate Legal Entities not Consolidated

Under certain conditions, institutions are permitted to report separately sponsored research that is granted to academic staff of the reporting institution, but conducted in entities that are not consolidated (see Section III .C.1 – Sponsored research). This sponsored research data must be reported under column 4 (Entities not Consolidated) in the applicable Tables in the annual return. Part II of the affiliation report requests additional information on this data.

For clarity, financial data for a Charitable Foundation is only included in the annual return if the Charitable Foundation is consolidated in the financial statements of the institution.

Separate legal "entities not consolidated" are individually identified on lines 11 to 18 in the affiliation report when the amount reported in the annual return is over $100,000. For the entities individually identified, information to be provided includes –

  • Legal name of affiliated institution
  • Category of affiliation – columns 1 to 7. Indicate the category of affiliation with an "x" in the appropriate column. For further information see the section below on Categories of Affiliation.
  • Amount included in annual return – column 10. The amount for the separate legal entity must be over $100,000.

All other separate legal entities with amounts under $100,000 are to combined and reported on line 19.

The total amount reported on line 20 in column 10 must agree with the amount reported in Table 1, line 27, column 4 and with the amount reported in Table 2, line 24, column 4.

(iii) Categories of Affiliation

For the purposes of the affiliation report in Table 5, a parent institution is defined as a university with federated, affiliated or associated institutions, research institutes or hospitals. In the Guidelines and the affiliation report, the term affiliates and affiliatedinstitutions are used to simplify the text and refer to all federated, affiliated and associated entities. For the same reason, the term institution may refer to universities, university-colleges, colleges, institutes and hospitals.

An affiliatedinstitution is responsible for its own administration but does not have the power to grant degrees. An associated institution is a public or private education, health, or research oriented, legal entity that is neither federated nor affiliated with the parent institution, yet has academic, research, or administrative ties to that parent institution. A federated institution is responsible for its own administration and has the power to grant degrees, but during the term of federation agreement it suspends some or all of its degree-granting powers.

Please note that in the cases of affiliated and federated institutions, the parent institution supervises instruction in the programs covered by the federation or affiliation agreement, and grants degrees to the students who successfully complete those programs.

7. Other Federal Government Departments and Agencies – Grants and Contracts (Table 6)

Table 6 reports grants and contracts by federal government departments and agencies, other than the grants and contracts reported on lines 1 to 6 in Table 1. In section A in Table 6, a separate line is provided for reporting the federal government allocation for the Indirect Costs of Research. The column totals in Table 6 must agree with the amounts reported on line 7 (Other federal) in Table 1.

In section B in Table 6, where the aggregate grants and contracts provided by a separate federal government department or agency is in excess of $100,000, identify the department or agency and report the amount, by fund.

On line C in Table 6, where the aggregate grants and contracts provided by a separate federal government department or agency is less than $100,000, combine the departments and agencies and report the total amount, by fund.

Please note that double counting of government grants and contracts is to be avoided and in certain situations grants or contracts received should be reported "net" of the funds disbursed or transferred (see Section II .E.15).

For additional information on the funds and on federal government grants and contracts, preparers should refer to Section III .C.1 (Funds) and Section  III .C.2 (Income by Fund), with particular emphasis in Section III .C.2 on the details in the government departments and agencies – grants and contracts category.

8. Provincial Government Departments and Agencies – Grants and Contracts (Table 7)

Table 7 reports grants and contracts, including certain specific and earmarked provincial CFI matching grants, by provincial government departments and agencies. The column totals in Table 7 must agree with the amounts reported on line 8 in Table 1.

Grants and contracts from provincial government departments and agencies only include those from the province with jurisdiction. Grants and contracts from other provinces are reported on line 10 (Other provinces) in Table 1.

In section A (Ministry responsible) in Table 7, please report the following information on lines 1 and 2:

  • Line 1: identify the primary provincial government department or agency responsible for the institution and report, by fund, the total of the grants and contracts received from that department or agency, excluding the CFI matching funds reported on line 2. The types of grants might include funding formula operating grants.
  • Line 2: under column 3 or 4, as appropriate, for sponsored research, report the total of the specific grants received, if any, from the "Ministry responsible" that are earmarked as CFI matching funds.

In section B (Other) in Table 7, where the aggregate grants and contracts provided by a separate provincial government department or agency is in excess of $100,000, identify the department or agency and report the amount, by fund.

On line C in Table 7, where the aggregate grants and contracts provided by a separate provincial government department or agency is less than $100,000, combine the departments and agencies and report the total amount, by fund. These types of departments and agencies are primarily funded by the provincial government and include Councils, Grants Commissions, and commissions and boards that perform various functions delegated to them by public authorities.

Please note that double counting of government grants and contracts is to be avoided and in certain situations grants or contracts received should be reported "net" of the funds disbursed or transferred (see Section II .E.15).

For additional information on the funds and on provincial government grants and contracts, preparers should refer to Section III .C.1 (Funds) and Section III .C.2 (Income by Fund), with particular emphasis in Section III .C.2 on the details in the government departments and agencies – grants and contracts category.
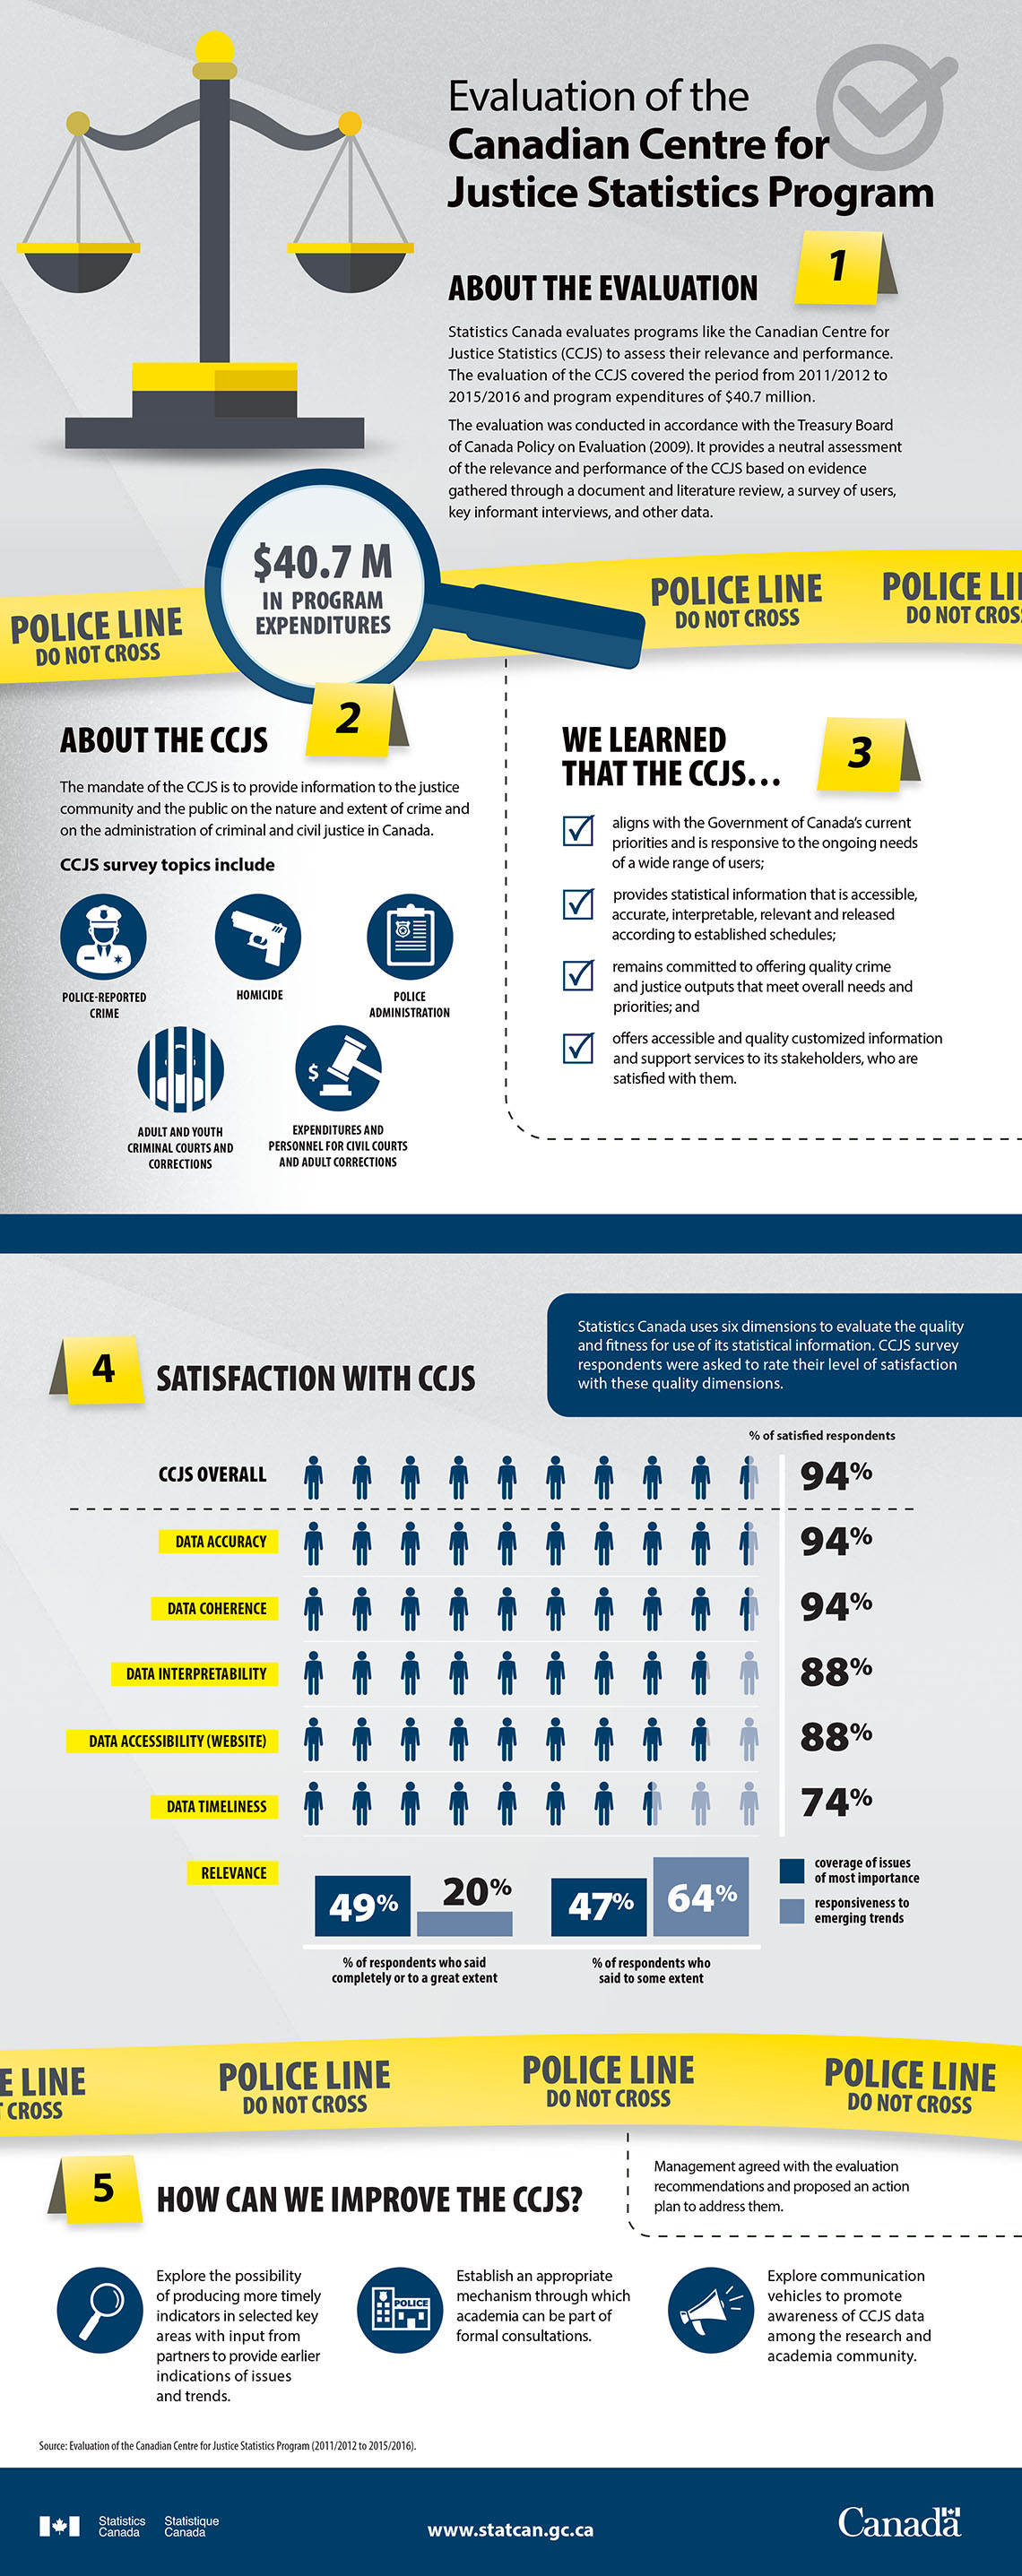
 

Canadian Health Survey on Children and Youth - 2026

Getting started

Why are we conducting this survey?

Statistics Canada is conducting a survey about the health and well-being of Canadian children and youth and you have been selected for this survey. The Canadian Health Survey on Children and Youth explores issues that have an impact on the physical and mental health of children and youth aged 1 to 17 years old such as use and availability of health care services, health conditions, mental health and substance use.

This survey also gives young people and their parents or guardians the opportunity to share their experiences, in complete confidentiality, to reflect a true picture of what affects youth's health and well-being today. The data will be used to develop programs and policies to better serve Canadian youth.

The questionnaire for parents or guardians of children of all ages contains two sections: a short preliminary section and the health section.

In addition, youth between the ages of 12 and 17 years old as of [August 31, 2026] have their own health questionnaire to complete.

Your information may also be used by Statistics Canada for other statistical and research purposes.

Although voluntary, your participation is important so that the information collected is as accurate and complete as possible.

Other important information

Authorization and confidentiality

Your data is collected under the authority of the Statistics Act. The information you provide will be kept strictly confidential. If you give your opinion about another person, that person has the right to ask us for any information we have about them. However, we have the right not to tell them what you have told us, if we think that sharing this information might not be safe for you. If there is any doubt at all, we will not share your information.

Record linkages

To enhance the data from this survey and to reduce the response burden, Statistics Canada will combine the information you provide with information from the tax data of all members of your household. Your provincial or territorial ministry of health or the Institut de la statistique du Québec for Quebec respondents may also combine the information you provide with other surveys or administrative sources.

Statistics Canada may also combine the information you provide with other survey or administrative data sources.
Contact us if you have any questions or concerns about record linkage:

Email: infostats@statcan.gc.ca

Telephone: 1-877-949-9492

Mail:
Chief Statistician of Canada
Statistics Canada
Attention of Director, Centre for Population Health Data
150 Tunney's Pasture Driveway
Ottawa, Ontario K1A 0T6

Respondent Verification

Is there a child in this household born in [birth year]?

  • Yes
  • No

What is this child's first and last name?

If more than one child was born in [birth year], please report for the [young/old]est child born during the year.

  • First name
  • Last name

May I speak with [First name of selected child] [Last name of selected child]'s parent or legal guardian?

  • Yes, parent or legal guardian available
  • No, parent or legal guardian not available at this time
  • No, parent or legal guardian not available to complete this survey

This survey should be completed by the parent, guardian or person who is the most knowledgeable about [First name of selected child]'s health and day-to-day activities.

Are you the parent or guardian of [First name of selected child] [Last name of selected child]?

  • Yes
  • No

What is [First name of selected child]'s date of birth?

  • Day
  • Month
  • Year (prefilled with [BIRTHYEAR])

In which province or territory do you currently live?

  • Province or territory
    • Alberta
    • British Columbia
    • Manitoba
    • New Brunswick
    • Newfoundland and Labrador
    • Northwest Territories
    • Nova Scotia
    • Nunavut
    • Ontario
    • Prince Edward Island
    • Quebec
    • Saskatchewan
    • Yukon

Parent or legal guardian consent

For youth 12 to 17 years old, the Canadian Health Survey on Children and Youth consists of two questionnaires: one questionnaire to be completed by you and another to be completed by your child. Please note that your child's questionnaire is just as important as yours, as it includes different questions.

Since [First name of selected child] was less than 15 years old when [First name of selected child] was selected to participate in this survey, your permission is needed before contacting [First name of selected child] to complete the youth questionnaire.

Do we have your permission to contact [First name of selected child] to complete the other portion of the Canadian Health Survey on Children and Youth?

  • Yes
  • No
    • To help us improve our survey, please specify why you do not grant permission to contact [First name of selected child] to complete the other portion of the Canadian Health Survey on Children and Youth

Confirm the date that consent was provided by clicking the Next button.

  • Date

An invitation to participate in the Canadian Health Survey on Children and Youth will be sent to your child. What email address and telephone number could we use to contact [First name of selected child]?

If your child cannot be contacted at an email address and/or phone number of their own, you may provide your own email address and/or phone number and pass on the invitation to your child.

  • Email address to contact [First name of selected child]
  • Please confirm the email address to contact [First name of selected child]
  • Telephone number to contact [First name of selected child]

Household composition

List all persons that usually live at this address, including yourself.
[First name of selected child] has already been listed.

Include all persons who have their main residence at this address, even if they are temporarily away, such as joint custody, students, persons staying at a secondary residence or cottage.

People usually living or staying at this address.

  • First name
  • Last name
  • Age

Enter the information for the first person to add and then press the Add this person button. Repeat for each person who lives at this address.

Once every member of the household has been added, press the Next button to continue.

What is the relationship of the following people to [FNAME]?

Please note that the dropdown list of possible responses is the same for everyone. Some relationship options may not be applicable to all members of your household.

Relationship to [FNAME]

> [HHC_Q001A] [HHC_Q001B], age [HHC_Q001D]

  • Birth parent
  • Step parent
  • Adoptive parent
  • Foster parent
  • Full brother or sister
  • Half brother or sister
  • Stepbrother or sister
  • Adopted brother or sister
  • Foster brother or sister
  • Grandparent
  • Boyfriend or girlfriend
  • Common-law partner or spouse
  • Son or daughter
  • Other related
  • Unrelated

Who is the parent, guardian or person completing this survey about [FNAME]?

This survey should be completed by the parent, guardian or person who is the most knowledgeable about [FNAME]'s health and day-to-day activities.

  • [HHC_Q001A] [HHC_Q001B], age [HHC_Q001]

What is the relationship of the following people to you?

Relationship to you

> [HHC_Q001A] [HHC_Q001B], age [HHC_Q001D]

  • Your husband or wife
  • Your common-law partner
  • Your father or mother
  • Your son or daughter (birth, adopted or step)
  • Your brother or sister
  • Your foster father or mother
  • Your foster son or daughter
  • Your grandfather or grandmother
  • Your grandson or granddaughter
  • Your in-law
  • Other related
  • Unrelated

Does [FNAME] have any brothers or sisters not already listed and living elsewhere?

Include step, half and adopted brothers and sisters.

  • Yes
    How many?
    • 1
    • 2
    • 3
    • 4
    • 5 or more
  • No

Contact information

Statistics Canada may contact you in the future to follow-up on this survey.

What is your telephone number?

  • Telephone number

What email address could we use to contact your household, if applicable?

  • Email address

Please confirm your email address.

  • Email address

Please verify your mailing address and correct it if it is not accurate.

  • Street address, including apartment or unit number (if applicable)
  • City, municipality, town, village, Indian reserve
  • Province or territory
    • Alberta
    • British Columbia
    • Manitoba
    • New Brunswick
    • Newfoundland and Labrador
    • Northwest Territories
    • Nova Scotia
    • Nunavut
    • Ontario
    • Prince Edward Island
    • Quebec
    • Saskatchewan
    • Yukon
  • Postal code

Gender and sex at birth – pmk

The following questions are about gender and sex at birth.

What is [FNAME]'s gender?

Gender refers to an individual's personal and social identity as a [man, a woman or a person who is not exclusively a man or a woman/boy, a girl or a person who is not exclusively a boy or a girl], for example, non-binary, agender, gender fluid, queer or Two-Spirit.

Is it:

  • [Man/Boy]
  • [Woman/Girl]
  • Or please specify
    • Specify [FNAME]'s gender

What was [FNAME]'s sex at birth?

Sex at birth refers to the sex recorded on a person's first birth certificate. It is typically observed based on a person's reproductive system and other physical characteristics.

  • Male
  • Female

What is your gender?

Gender refers to an individual's personal and social identity as a man, a woman or a person who is not exclusively a man or a woman, for example, non-binary, agender, gender fluid, queer or Two-Spirit.

Is it:

  • Man
  • Woman
  • Or please specify
    • Specify your gender

What was your sex at birth?

Sex at birth refers to the sex recorded on a person's first birth certificate. It is typically observed based on a person's reproductive system and other physical characteristics.

  • Male
  • Female

What is [First name of PMK spouse/your spouse or partner]'s gender?

Gender refers to an individual's personal and social identity as a man, a woman or a person who is not exclusively a man or a woman, for example, non-binary, agender, gender fluid, queer or Two-Spirit.

Is it:

  • Man
  • Woman
  • Or please specify
    • Specify [First name of PMK spouse/your spouse or partner]'s gender

What was [First name of PMK spouse/your spouse or partner]'s sex at birth?

Sex at birth refers to the sex recorded on a person's first birth certificate. It is typically observed based on a person's reproductive system and other physical characteristics.

  • Male
  • Female

Please verify that all of the information is correct.

If all the information is correct, then press the Next button.
To make changes, please press the Previous button.

> [FNAME]'s information 
Gender: [Man/Boy/Man (or boy)/Woman/Girl/Woman (or girl)/[RRS4_S030]/Information not provided]
Sex at birth: [Male/Female/Information not provided]

> Your information 
Gender: [Man/Woman/[RRS4_S050]/Information not provided]
Sex at birth: [Male/Female/Information not provided]

> [First name of PMK spouse/Your spouse or partner]'s information
Gender: [Man/Woman/[RRS4_S070]/Information not provided]
Sex at birth: [Male/Female/Information not provided]

[For reasons of text length and without discrimination, the masculine pronouns are used throughout the questionnaire for respondents whose gender was reported using the write-in option.]

Youth respondent verification

Are you [First name of selected child] [Last name of selected child]?

  • Yes
  • No

What is your date of birth?

  • Day
  • Month
  • Year

In which province or territory do you currently live?

  • Province or territory
    • Alberta
    • British Columbia
    • Manitoba
    • New Brunswick
    • Newfoundland and Labrador
    • Northwest Territories
    • Nova Scotia
    • Nunavut
    • Ontario
    • Prince Edward Island
    • Quebec
    • Saskatchewan
    • Yukon

Gender and sex at birth - youth

The following questions are about gender and sex at birth.

What is your gender?

Gender refers to an individual's personal and social identity as a [man, a woman or a person who is not exclusively a man or a woman/boy, a girl or a person who is not exclusively a boy or a girl], for example, non-binary, agender, gender fluid, queer or Two-Spirit.

Is it:

  • [Man/Boy]
  • [Woman/Girl]
  • Or please specify
    • Specify your gender

What was your sex at birth?

Sex at birth refers to the sex recorded on a person's first birth certificate. It is typically observed based on a person's reproductive system and other physical characteristics.

  • Male
  • Female

Please verify that all of the information is correct.

Gender: [Man/Boy/Man (or boy)/Woman/Girl/Woman (or girl)/[SBG_S010]/Information not provided]
Sex at birth: [Male/Female/Information not provided]

[For reasons of text length and without discrimination, the masculine pronouns are used throughout the questionnaire for respondents whose gender was reported using the write-in option./" "]

Marital status

What is your marital status?

Is it:

  • Married
    For Quebec residents only, select the "Married" category if your marital status is "civil union".
  • Living common law
    Two people who live together as a couple but who are not legally married to each other.
  • Never married (not living common law)
  • Separated (not living common law)
  • Divorced (not living common law)
  • Widowed (not living common law)

General health

The following questions are about health. By health, we mean not only the absence of disease or injury but also physical, mental and social well-being.

In general, how is [FNAME]'s health?

Would you say:

  • Excellent
  • Very good
  • Good
  • Fair
  • Poor

In general, how is your health?

Would you say:

  • Excellent
  • Very good
  • Good
  • Fair
  • Poor

In general, how is [FNAME]'s mental health?

Would you say:

  • Excellent
  • Very good
  • Good
  • Fair
  • Poor

In general, how is your mental health?

Would you say:

  • Excellent
  • Very good
  • Good
  • Fair
  • Poor

Using a scale of 0 to 10, where 0 means "very dissatisfied" and 10 means "very satisfied", how do you feel about your life as a whole right now?

  • 0 - Very dissatisfied
  • 1
  • 2
  • 3
  • 4
  • 5
  • 6
  • 7
  • 8
  • 9
  • 10 - Very satisfied

Thinking about the amount of stress in your life, how would you describe most of your days?

Would you say:

  • Not at all stressful
  • Not very stressful
  • A bit stressful
  • Quite a bit stressful
  • Extremely stressful

The following questions are about health. By health, we mean not only the absence of disease or injury but also physical, mental and social well-being.

In general, how is your health?

Would you say:

  • Excellent
  • Very good
  • Good
  • Fair
  • Poor

In general, how is your mental health?

Would you say:

  • Excellent
  • Very good
  • Good
  • Fair
  • Poor

Using a scale of 0 to 10, where 0 means "very dissatisfied" and 10 means "very satisfied", how do you feel about your life as a whole right now?

  • 0 - Very dissatisfied
  • 1
  • 2
  • 3
  • 4
  • 5
  • 6
  • 7
  • 8
  • 9
  • 10 - Very satisfied

Thinking about the amount of stress in your life, how would you describe most of your days?

Would you say:

  • Not at all stressful
  • Not very stressful
  • A bit stressful
  • Quite a bit stressful
  • Extremely stressful

How would you usually describe yourself?

Would you say:

  • Happy and interested in life
  • Somewhat happy
  • Somewhat unhappy
  • Unhappy with little interest in life
  • So unhappy that life is not worthwhile

Height and weight

How tall [is [FNAME]/are you] without shoes on?

  • Feet
  • Inches
    OR
  • Centimetres

How much [does [FNAME]/do you] weigh without shoes on?

  • Weight
  • Pounds or kilograms
    • Pounds
    • Kilograms

Long-term health conditions

The following questions are about certain long-term health conditions which [FNAME] may have. We are interested in long-term conditions which are expected to last, or have already lasted 6 months or more and that have been diagnosed by a health professional.

Has [FNAME] been diagnosed with any of the following long-term health conditions?

Select all that apply.

  • Asthma
  • Diabetes
    Include type 1 or type 2 diabetes.
    Exclude prediabetes.
  • Allergies diagnosed as a result of allergy test
  • Epilepsy
    Exclude a one-time, non-recurring seizure.
  • An anxiety disorder, such as a phobia, a panic disorder or generalized anxiety disorder
  • A mood disorder such as depression, bipolar disorder, mania or dysthymia
  • An eating disorder such as anorexia nervosa, bulimia or binge eating disorder
  • A learning disability or learning disorder
    Learning disabilities or learning disorders are difficulties in the ability to learn or use specific academic skills e.g., reading, writing or arithmetic.
  • Attention deficit disorder or attention deficit hyperactivity disorder, also known as ADD or ADHD
  • Autism spectrum disorder, also known as autism, autistic disorder, Asperger's disorder or pervasive developmental disorder
  • Fetal Alcohol Spectrum Disorder, also known as FASD
  • Post-traumatic stress disorder, also known as PTSD
  • Chronic pain
  • Obsessive-compulsive disorder, also known as OCD
  • Oppositional defiant disorder, also known as ODD
  • Substance use disorder such as alcohol use disorder, cannabis dependence, or opioid dependence
  • Any other long-term physical, mental, developmental or intellectual conditions that are expected to last or have already lasted 6 months or more and that have been diagnosed by a health professional

    • Specify other condition 1
    • Specify other condition 2
    • Specify other condition 3
    • Specify other condition 4
    • Specify other condition 5

    OR

  • None of the above

How often do the following conditions limit [his/her] daily activities?

  1. Asthma
    • Never
    • Rarely
    • Sometimes
    • Often
    • Always
  2. Diabetes
    • Never
    • Rarely
    • Sometimes
    • Often
    • Always
  3. Allergies diagnosed as a result of allergy test
    • Never
    • Rarely
    • Sometimes
    • Often
    • Always
  4. Epilepsy
    • Never
    • Rarely
    • Sometimes
    • Often
    • Always
  5. An anxiety disorder, such as a phobia, a panic disorder or generalized anxiety disorder
    • Never
    • Rarely
    • Sometimes
    • Often
    • Always
  6. A mood disorder such as depression, bipolar disorder, mania or dysthymia
    • Never
    • Rarely
    • Sometimes
    • Often
    • Always
  7. An eating disorder such as anorexia nervosa, bulimia or binge eating disorder
    • Never
    • Rarely
    • Sometimes
    • Often
    • Always
  8. A learning disability or learning disorder
    • Never
    • Rarely
    • Sometimes
    • Often
    • Always
  9. Attention deficit disorder or attention deficit hyperactivity disorder, also known as ADD or ADHD
    • Never
    • Rarely
    • Sometimes
    • Often
    • Always
  10. Autism spectrum disorder, also known as autism, autistic disorder, Asperger's disorder or pervasive developmental disorder
    • Never
    • Rarely
    • Sometimes
    • Often
    • Always
  11. Fetal Alcohol Spectrum Disorder, also known as FASD
    • Never
    • Rarely
    • Sometimes
    • Often
    • Always
  12. Post-traumatic stress disorder, also known as PTSD
    • Never
    • Rarely
    • Sometimes
    • Often
    • Always
  13. Chronic pain
    • Never
    • Rarely
    • Sometimes
    • Often
    • Always
  14. Obsessive-compulsive disorder, also known as OCD
    • Never
    • Rarely
    • Sometimes
    • Often
    • Always
  15. Oppositional defiant disorder, also known as ODD
    • Never
    • Rarely
    • Sometimes
    • Often
    • Always
  16. Substance use disorder such as alcohol use disorder, cannabis dependence, or opioid dependence
    • Never
    • Rarely
    • Sometimes
    • Often
    • Always
  17. [LTC_Q006A]
    • Never
    • Rarely
    • Sometimes
    • Often
    • Always
  18. [LTC_Q006C]
    • Never
    • Rarely
    • Sometimes
    • Often
    • Always
  19. [LTC_Q006E]
    • Never
    • Rarely
    • Sometimes
    • Often
    • Always
  20. [LTC_Q006G]
    • Never
    • Rarely
    • Sometimes
    • Often
    • Always
  21. [LTC_Q006I]
    • Never
    • Rarely
    • Sometimes
    • Often
    • Always
  22. Other long-term condition
    • Never
    • Rarely
    • Sometimes
    • Often
    • Always

How old was [FNAME] when [he/she] was first diagnosed with the following conditions?

  1. Asthma
    • Age in years
  2. Diabetes
    • Age in years
  3. Allergies diagnosed as a result of allergy test
    • Age in years
  4. Epilepsy
    • Age in years
  5. An anxiety disorder, such as a phobia, a panic disorder or generalized anxiety disorder
    • Age in years
  6. A mood disorder such as depression, bipolar disorder, mania or dysthymia
    • Age in years
  7. An eating disorder such as anorexia nervosa, bulimia or binge eating disorder
    • Age in years
  8. A learning disability or learning disorder
    • Age in years
  9. Attention deficit disorder or attention deficit hyperactivity disorder, also known as ADD or ADHD
    • Age in years
  10. Fetal Alcohol Spectrum Disorder, also known as FASD
    • Age in years
  11. Post-traumatic stress disorder, also known as PTSD
    • Age in years
  12. Chronic pain
    • Age in years
  13. Obsessive-compulsive disorder, also known as OCD
    • Age in years
  14. Oppositional defiant disorder, also known as ODD
    • Age in years
  15. Substance use disorder such as alcohol use disorder, cannabis dependence, or opioid dependence
    • Age in years
  16. [LTC_Q006A]
    • Age in years
  17. [LTC_Q006C]
    • Age in years
  18. [LTC_Q006E]
    • Age in years
  19. [LTC_Q006G]
    • Age in years
  20. [LTC_Q006I]
    • Age in years
  21. Other long-term condition
    • Age in years

Has [FNAME] had any asthma symptoms or asthma attacks in the past 12 months?

  • Yes
  • No

When [FNAME] was first diagnosed with diabetes, how long was it before [he/she] started on insulin?

  • Less than 1 month
  • 1 month to less than 2 months
  • 2 months to less than 6 months
  • 6 months to less than a year
  • 1 year or more
  • Never

Does [FNAME] use any of the following medication?

  1. Any medicine for asthma such as inhalers (pumps), nebulizers, pills, liquids or injections in the past 12 months
    • Yes
    • No
  2. Currently takes insulin for [his/her] diabetes
    • Yes
    • No
  3. Pills to control [his/her] blood sugar in the past month
    • Yes
    • No
  4. Medication for an anxiety disorder in the past 12 months
    • Yes
    • No
  5. Medication for a mood disorder such as depression, bipolar disorder, mania or dysthymia in the past 12 months
    • Yes
    • No
  6. Medication for ADD or ADHD In the past 12 months
    • Yes
    • No

The following questions are about the time prior to [FNAME]'s autism spectrum disorder diagnosis.

What were the initial concerns about [FNAME]'s health or development?

Select all that apply.

Would you say:

  • Language or communication
    e.g., speech delay, difficulty having a back-and-forth conversation
  • Social interaction
    e.g., difficulty playing with others, making friends
  • Sensory
    e.g., sensitivity to sounds, textures, light
  • Emotions or behaviour
    e.g., emotional outbursts, difficulty coping with change
  • Motor skills
    e.g., difficulty manipulating objects, picking up small objects, holding a pen, coordination issues
  • Learning or concentration
    e.g., difficulty learning a new task
  • Sleep
    e.g., difficulty falling and staying asleep
  • Eating habits
    e.g., avoidance of certain types of food
  • Self-care
    e.g., difficulty dressing
  • Other

How old was [FNAME] when these initial concerns were first observed?

  • Years
  • Months

Who observed these initial concerns?

Select all that apply.

Would you say:

  • Parent, guardian or family member
  • Physician
    e.g., family doctor, general practitioner, pediatrician
  • Other health care professional
    e.g., nurse, social worker, speech-language therapist or pathologist
  • Child care provider, teacher or school staff
  • Friend, neighbour or community member
  • Other

Now we'd like to ask about [FNAME]'s autism spectrum disorder diagnosis.

Which one of the following professionals diagnosed [FNAME]'s autism spectrum disorder?

Would you say:

  • Family doctor or general practitioner
  • Developmental pediatrician
  • Psychiatrist or child psychiatrist
  • Psychologist or child psychologist
  • General pediatrician
  • Neurologist
  • Nurse Practitioner
  • Other

How old was [FNAME] when [he/she] was first diagnosed with autism spectrum disorder?

Indicate [FNAME's] age in years and months, e.g., 4 years and 6 months.

  • Years
  • Months

Did you experience any of the following challenges in obtaining an autism spectrum disorder diagnosis for [FNAME]?

Select all that apply.

Would you say:

  • Initial concerns did not seem related to autism
  • Did not have a regular health care provider
  • Did not know who or where to seek professional help
  • Concerns about stigma associated with an autism diagnosis
    e.g., being treated differently or discriminated against
  • Health professionals were hesitant to make a referral for a diagnostic assessment
  • Child was not initially diagnosed with autism despite having a diagnostic assessment
  • Long waitlist
  • Cost
  • Distance to professional help
  • Difficulty accessing health professionals during the COVID-19 pandemic
  • Other
    OR
  • No challenges experienced

Preterm birth status

Was [FNAME] born pre-term?

Preterm births are live births with a gestational age less than 37 weeks.

  • Yes
    What was the gestational age of [FNAME] at birth?
    Was it:
    • Less than 28 weeks
    • 28 to less than 32 weeks
    • 32 to less than 37 weeks
  • No
  • Don't know

Child functioning

Now some questions about difficulties your child may have.

Does [FNAME] wear glasses[ or contact lenses]?

  • Yes
  • No

When wearing [his/her] glasses[ or contact lenses], does [FNAME] have difficulty seeing?

Would you say [FNAME] has:

  • No difficulty
  • Some difficulty
  • A lot of difficulty
  • Cannot do at all

Does [FNAME] have difficulty seeing?

Would you say [FNAME] has:

  • No difficulty
  • Some difficulty
  • A lot of difficulty
  • Cannot do at all

Does [FNAME] use a hearing aid?

  • Yes
  • No

When using [his/her] hearing aid, does [FNAME] have difficulty hearing sounds like people's voices or music?

Would you say [FNAME] has:

  • No difficulty
  • Some difficulty
  • A lot of difficulty
  • Cannot do at all

Does [FNAME] have difficulty hearing sounds like people's voices or music?

Would you say [FNAME] has:

  • No difficulty
  • Some difficulty
  • A lot of difficulty
  • Cannot do at all

Does [FNAME] use any equipment or receive assistance for walking?

  • Yes
  • No

Without [his/her] equipment or assistance, does [FNAME] have difficulty walking?

Would you say [FNAME] has:

  • Some difficulty
  • A lot of difficulty
  • Cannot do at all

With [his/her] equipment or assistance, does [FNAME] have difficulty walking?

Would you say [FNAME] has:

  • No difficulty
  • Some difficulty
  • A lot of difficulty
  • Cannot do at all

Compared with children of the same age, does [FNAME] have difficulty walking?

Would you say [FNAME] has:

  • No difficulty
  • Some difficulty
  • A lot of difficulty
  • Cannot do at all

Compared with children of the same age, does [FNAME] have difficulty picking up small objects with [his/her] hand?

Would you say [FNAME] has:

  • No difficulty
  • Some difficulty
  • A lot of difficulty
  • Cannot do at all

Does [FNAME] have difficulty understanding you?

Would you say [FNAME] has:

  • No difficulty
  • Some difficulty
  • A lot of difficulty
  • Cannot do at all

When [FNAME] speaks, do you have difficulty understanding [him/her]?

Would you say you have:

  • No difficulty
  • Some difficulty
  • A lot of difficulty
  • Cannot do at all

Without [his/her] equipment or assistance, does [FNAME] have difficulty walking 100 yards/metres on level ground? That would be about the length of 1 football field.

Would you say [FNAME] has:

  • Some difficulty
  • A lot of difficulty
  • Cannot do at all

Without [his/her] equipment or assistance, does [FNAME] have difficulty walking 500 yards/metres on level ground? That would be about the length of 5 football fields.

Would you say [FNAME] has:

  • Some difficulty
  • A lot of difficulty
  • Cannot do at all

With [his/her] equipment or assistance, does [FNAME] have difficulty walking 100 yards/metres on level ground? That would be about the length of 1 football field.

Would you say [FNAME] has:

  • No difficulty
  • Some difficulty
  • A lot of difficulty
  • Cannot do at all

With [his/her] equipment or assistance, does [FNAME] have difficulty walking 500 yards/metres on level ground? That would be about the length of 5 football fields.

Would you say [FNAME] has:

  • No difficulty
  • Some difficulty
  • A lot of difficulty
  • Cannot do at all

Compared with children of the same age, does [FNAME] have difficulty walking 100 yards/metres on level ground? That would be about the length of 1 football field.

Would you say [FNAME] has:

  • No difficulty
  • Some difficulty
  • A lot of difficulty
  • Cannot do at all

Compared with children of the same age, does [FNAME] have difficulty walking 500 yards/metres on level ground? That would be about the length of 5 football fields.

Would you say [FNAME] has:

  • No difficulty
  • Some difficulty
  • A lot of difficulty
  • Cannot do at all

Does [FNAME] have difficulty with self-care such as feeding or dressing [himself/herself]?

Would you say [FNAME] has:

  • No difficulty
  • Some difficulty
  • A lot of difficulty
  • Cannot do at all

When [FNAME] speaks, does [he/she] have difficulty being understood by people inside of this household?

Would you say [FNAME] has:

  • No difficulty
  • Some difficulty
  • A lot of difficulty
  • Cannot do at all

When [FNAME] speaks, does [he/she] have difficulty being understood by people outside of this household?

Would you say [FNAME] has:

  • No difficulty
  • Some difficulty
  • A lot of difficulty
  • Cannot do at all

Compared with children of the same age, does [FNAME] have difficulty learning things?

Would you say [FNAME] has:

  • No difficulty
  • Some difficulty
  • A lot of difficulty
  • Cannot do at all

Compared with children of the same age, does [FNAME] have difficulty playing?

Would you say [FNAME] has:

  • No difficulty
  • Some difficulty
  • A lot of difficulty
  • Cannot do at all

Compared with children of the same age, how much does [FNAME] kick, bite, or hit other children or adults?

Would you say:

  • Not at all
  • The same or less
  • More
  • A lot more

Compared with children of the same age, does [FNAME] have difficulty remembering things?

Would you say [FNAME] has:

  • No difficulty
  • Some difficulty
  • A lot of difficulty
  • Cannot do at all

Does [FNAME] have difficulty concentrating on an activity that [he/she] enjoys doing?

Would you say [FNAME] has:

  • No difficulty
  • Some difficulty
  • A lot of difficulty
  • Cannot do at all

Does [FNAME] have difficulty accepting changes in [his/her] routine?

Would you say [FNAME] has:

  • No difficulty
  • Some difficulty
  • A lot of difficulty
  • Cannot do at all

Compared with children of the same age, does [FNAME] have difficulty controlling [his/her] behaviour?

Would you say [FNAME] has:

  • No difficulty
  • Some difficulty
  • A lot of difficulty
  • Cannot do at all

Does [FNAME] have difficulty making friends?

Would you say [FNAME] has:

  • No difficulty
  • Some difficulty
  • A lot of difficulty
  • Cannot do at all

How often does [FNAME] seem very anxious, nervous or worried?

Would you say:

  • Daily
  • Weekly
  • Monthly
  • A few times a year
  • Never

How often does [FNAME] seem very sad or depressed?

Would you say:

  • Daily
  • Weekly
  • Monthly
  • A few times a year
  • Never

Emotional behavioural scale

Below is a list of statements that describes some of the feelings and behaviours of children and youth. For each statement, please select the response that best describes [you/[FNAME]] now or within the past 6 months. You may only select one response.

  1. [A/I am a]ngry and resentful
    • Never or not true
    • Sometimes or somewhat true
    • Often or very true
  2. [A/I am a]nxious or on edge
    • Never or not true
    • Sometimes or somewhat true
    • Often or very true
  3. [A/I a]rgue[/s] a lot with adults
    • Never or not true
    • Sometimes or somewhat true
    • Often or very true
  4. [B/I b]lame[/s] others for [his/her/my] own mistakes
    • Never or not true
    • Sometimes or somewhat true
    • Often or very true
  5. [Can't concentrate, can't pay attention for long/I have trouble concentrating or paying attention]
    • Never or not true
    • Sometimes or somewhat true
    • Often or very true
  6. [C/I c]an't stay seated when required to do so
    • Never or not true
    • Sometimes or somewhat true
    • Often or very true
  7. [Distractible, has trouble sticking to any activity/I am easily distracted, have difficulty sticking to any activity]
    • Never or not true
    • Sometimes or somewhat true
    • Often or very true
  8. [Easily/I am easily] annoyed by others
    • Never or not true
    • Sometimes or somewhat true
    • Often or very true
  9. [F/I f]ail[/s] to finish things [[he/she]/I] start[/s]
    • Never or not true
    • Sometimes or somewhat true
    • Often or very true
  10. [F/I f]eel[/s] worthless or inferior
    • Never or not true
    • Sometimes or somewhat true
    • Often or very true
  11. [F/I f]idget[/s]
    • Never or not true
    • Sometimes or somewhat true
    • Often or very true
  12. [F/I f]ind[/s] it hard to stop worrying
    • Never or not true
    • Sometimes or somewhat true
    • Often or very true
  13. [Has/I have] difficulty awaiting turn in games or groups
    • Never or not true
    • Sometimes or somewhat true
    • Often or very true
  14. [Has/I have] trouble enjoying [[him/her]/my]self
    • Never or not true
    • Sometimes or somewhat true
    • Often or very true
  15. [Impulsive or acts without thinking/I act without thinking or stopping to think]
    • Never or not true
    • Sometimes or somewhat true
    • Often or very true
  16. [Loses your/I lose my] temper
    • Never or not true
    • Sometimes or somewhat true
    • Often or very true
  17. [Nervous, high-strung or tense/I am nervous or tense]
    • Never or not true
    • Sometimes or somewhat true
    • Often or very true
  18. [Talks about killing self/I think about killing myself]
    • Never or not true
    • Sometimes or somewhat true
    • Often or very true
  19. [T/I am t]oo fearful or anxious
    • Never or not true
    • Sometimes or somewhat true
    • Often or very true
  20. [U/I am u]nhappy, sad or depressed
    • Never or not true
    • Sometimes or somewhat true
    • Often or very true

Pediatric symptom checklist

For the following questions, please think about [FNAME]'s overall behaviour in general.

These questions are about your child's behavior. Think about what you would expect of other children the same age and tell us how much each statement applies to your child.

  1. Does your child seem nervous or afraid?
    • Not at all
    • Somewhat
    • Very much
  2. Does your child seem sad or unhappy?
    • Not at all
    • Somewhat
    • Very much
  3. Does your child get upset if things are not done in a certain way?
    • Not at all
    • Somewhat
    • Very much
  4. Does your child have a hard time with change?
    • Not at all
    • Somewhat
    • Very much
  5. Does your child have trouble playing with other children?
    • Not at all
    • Somewhat
    • Very much
  6. Does your child break things on purpose?
    • Not at all
    • Somewhat
    • Very much
  7. Does your child fight with other children?
    • Not at all
    • Somewhat
    • Very much
  8. Does your child have trouble paying attention?
    • Not at all
    • Somewhat
    • Very much
  9. Does your child have a hard time calming down?
    • Not at all
    • Somewhat
    • Very much
  10. Does your child have trouble staying with one activity?
    • Not at all
    • Somewhat
    • Very much
  11. Is your child aggressive?
    • Not at all
    • Somewhat
    • Very much
  12. Is your child fidgety or unable to sit still?
    • Not at all
    • Somewhat
    • Very much
  13. Is your child angry?
    • Not at all
    • Somewhat
    • Very much
  14. Is it hard to take your child out in public?
    • Not at all
    • Somewhat
    • Very much
  15. Is it hard to comfort your child?
    • Not at all
    • Somewhat
    • Very much
  16. Is it hard to know what your child needs?
    • Not at all
    • Somewhat
    • Very much
  17. Is it hard to keep your child on a schedule or routine?
    • Not at all
    • Somewhat
    • Very much
  18. Is it hard to get your child to obey you?
    • Not at all
    • Somewhat
    • Very much

Regular health care provider

Now, here are some questions about primary health care. This type of health care is often delivered by family doctors, pediatricians or nurse practitioners.

Does [FNAME] have a regular health care provider?

By this, we mean a primary health care professional that you or [FNAME] can consult with when [FNAME] needs care or advice for [his/her] health.

Select "Yes, another health professional" if [he/she] receive[s] regular care from locums.

  • Yes, a family doctor or pediatrician
  • Yes, a nurse practitioner
  • Yes, another health professional
    • Specify the other health professional
  • No

When [FNAME] consults with [this family doctor or paediatrician/this nurse practitioner/this other health professional], do you have to pay out-of-pocket for the consultation because they work in a private pay model?

Exclude any fees associated with medical notes for work or school, expedited blood work, prescription renewals, cosmetic procedures, travel medicine advice and vaccines, tests requested by employers or insurance companies, and other services that are not covered by the universal health care system.

  • Yes
  • No
  • Don't know

Some patients receive primary health care from a team of health professionals working together to provide coordinated services and care. In addition to family doctors and nurses, these teams could include social workers, dieticians and pharmacists, but do not include medical specialists (e.g., cardiologists, oncologists).

Is [FNAME] a patient of a team of health professionals that work together to provide [him/her] with coordinated services or care?

Exclude care provided by teams of medical specialists (e.g., cardiologists, oncologists).

Depending on where you live, these teams might be called a Family Health Team, Family Medicine Group, Integrated Care Network or Primary Care Network.

  • Yes
  • No
  • Don't know

Do you have to pay out-of-pocket for any of the services provided by the team of health professionals?

Exclude any fees associated with medical notes for work or school, expedited blood work, prescription renewals, cosmetic procedures, travel medicine advice and vaccines, tests requested by employers or insurance companies, and other services that are not covered by the universal health care system.

  • Yes
  • No
  • Don't know

Why does [FNAME] not have a regular health care provider?

Select all that apply.

Would you say:

  • Currently on a waitlist
  • Does not need one in particular
  • No one in the area is taking new patients
  • There are no health care providers in the area
  • Have not tried to find one
  • [FNAME] had one who left, retired, or changed their practice
  • [FNAME] moved to a new area
  • Other
    • Specify the other reason [he/she] does not have a regular health care provider

The following questions are about consultations [FNAME] may have had in the past 12 months with a primary health care provider when [he/she] was sick or you were concerned about [his/her] health.

In the past 12 months, did [FNAME] consult a primary health care provider when [he/she] was sick or you were concerned about [his/her] health?

Exclude visits to the emergency department, scheduled check-ups or routine testing, and consultations with optometrists, dentists, or medical specialists (e.g., cardiologists, oncologists).

Include both in-person and virtual consultations, such as over the telephone, by video, or by written correspondence.

  • Yes
  • No

Thinking about the most recent consultation when [FNAME] was sick or you were concerned about [his/her] health, was this consultation with [his/her] [family doctor or pediatrician/nurse practitioner/other health professional who is [his/her] regular health care provider]?

Exclude consultations with medical specialists (e.g., cardiologists, oncologists).

Include both in-person and virtual consultations, such as over the telephone, by video, or by written correspondence.

  • Yes
  • No

Thinking about the most recent consultation when [FNAME] was sick or you were concerned about [his/her] health, was this consultation with a member of the team of health professionals who provides [FNAME] with coordinated services or care?

Exclude consultations with medical specialists (e.g., cardiologists, oncologists).

Include both in-person and virtual consultations, such as over the telephone, by video, or by written correspondence.

  • Yes
  • No

Thinking about the most recent consultation when [FNAME] was sick or you were concerned about [his/her] health, did you have to pay out-of-pocket because this primary health care provider works in a private pay model?

Exclude any fees associated with medical notes for work or school, expedited blood work, prescription renewals, cosmetic procedures, travel medicine advice and vaccines, tests requested by employers or insurance companies, and other services that are not covered by the universal health care system.

  • Yes
  • No
  • Don't know

Still thinking about this most recent consultation, how long did you have to wait between the time you requested care and when [FNAME] consulted [this primary health care provider/[his/her] family doctor/[his/her] nurse practitioner/[his/her] other health professional who is [his/her] regular health care provider/a member from [his/her] team of health professionals]?

Would you say:

  • The same day
  • The next day
  • 2 to 3 days
  • 4 to 6 days
  • 1 week to less than 2 weeks
  • 2 weeks to less than 1 month
  • 1 month to less than 3 months
  • 3 months to less than 6 months
  • 6 months or more

Still thinking about this most recent consultation, how satisfied were you with the time you had to wait between requesting care and when [FNAME] consulted with [this primary health care provider/[his/her] family doctor/[his/her] nurse practitioner/[his/her] other health professional who is [his/her] regular health care provider/a member from [his/her] team of health professionals]?

Woud you say:

  • Very satisfied
  • Satisfied
  • Neither satisfied nor dissatisfied
  • Dissatisfied
  • Very dissatisfied

Still thinking about this most recent consultation, indicate to what extent you agree or disagree with the following statement.

[FNAME] received health care that was sensitive to [his/her] cultural background and identity from [this primary health care provider/[his/her] family doctor/[his/her] nurse practitioner/[his/her] other health professional who is [his/her] regular health care provider/this member of [his/her] team of health professionals].

This is health care that makes the patient feel they are respected, safe and can trust the health care provider.

Include how [FNAME] was treated based on age, sex, gender, sexual orientation, ethnicity, Indigenous identity, race, language, accent, religion or spirituality, disability, or other factors.

Would you say:

  • Strongly agree
  • Agree
  • Neither agree nor disagree
  • Disagree
    For which reasons do you feel [FNAME] did not receive health care that was sensitive to [his/her] cultural background and identity?
    Select all that apply.
    • Ethnicity or culture
    • Indigenous identity
    • Race or skin colour
    • Language
    • Accent
    • Religion or spirituality
    • Age
    • Sex
      Refers to sex assigned at birth.
    • Gender
      Refers to an individual's personal and social identity as a man, woman, or non-binary person.
    • Sexual orientation
      Refers to how a person describes their sexuality.
    • Disability
    • Other reason

      • Specify the other reason you disagree

      OR

    • Don't know
  • Strongly disagree
    For which reasons do you feel [FNAME] did not receive health care that was sensitive to [his/her] cultural background and identity?
    Select all that apply.
    • Ethnicity or culture
    • Indigenous identity
    • Race or skin colour
    • Language
    • Accent
    • Religion or spirituality
    • Age
    • Sex
      Refers to sex assigned at birth.
    • Gender
      Refers to an individual's personal and social identity as a man, woman, or non-binary person.
    • Sexual orientation
      Refers to how a person describes their sexuality.
    • Disability
    • Other reason

      • Specify the other reason you disagree

      OR

    • Don't know

Electronic health information

The following questions are about whether you can access [FNAME]'s health information online through websites, applications or portals.

This information may be provided by health authorities, hospitals, doctors, laboratories, pharmacies or other health professionals.

Which of the following types of information about [FNAME]'s health do you have access to through websites, applications, or portals?

Select a category even if you have access to some, but not all of this type of health information electronically.

e.g., select "Laboratory test results" if you can access some, but not all of [FNAME]'s laboratory test results electronically

Select all that apply.

Would you say:

  • Laboratory test results
  • COVID-19 vaccine records
  • Vaccine or immunization records other than for COVID-19
  • Current medications and medication history
    Include requests for prescription renewals
  • Patient visit summaries
  • Specialist consultation notes or records
  • Upcoming appointments
  • Forms and questionnaires
  • Progress notes
  • Discharge summaries
  • Medical imaging reports
  • Other health information

    • Specify the other health information you have access to

    OR

  • None of the above

Perceived need for care

The following questions deal with the different kinds of professional help [[FNAME]/you] received, or thought were needed, for [his/her/your] emotions[ or mental health/, mental health or use of alcohol or drugs].

During the past 12 months, did [[FNAME]/you] receive any form of professional help for [his/her/your] emotions[ or mental health/, mental health or use of alcohol or drugs]?

This could include counseling or therapy, help with interpersonal relationships, or prescription medication.

  • Yes
  • No

Which type of professional help did [[FNAME]/you] receive?

Select all that apply.

Was it:

  • Counseling or therapy
  • Prescription medication
  • Other
    • Specify other professional help

You mentioned that [[FNAME]/you] received professional help for [his/her/your] emotions[ or mental health/, mental health or use of alcohol or drugs]. Do you think [you/he/she] received all the help needed during the past 12 months?

  • Yes
  • No

Why do you think [[FNAME]/you] did not receive all the help [you/he/she] needed during the past 12 months?

Select all that apply.

Would you say:

  • Preferred to self-manage
  • Didn't know how or where to get help
  • Too busy
  • Job interfered
    e.g., workload, hours of work or no cooperation from supervisor
  • Help was not readily available
    e.g., long wait lists
  • Help was not available where you live
  • Had trouble finding or affording transportation
  • Help did not meet [his/her/your] needs
  • Didn't have confidence in health care system or social services
  • Couldn't afford to pay
  • Afraid of what others would think
  • Language or cultural barriers
  • Other
    • Specify other reason

You mentioned that [[FNAME]/you] did not receive professional help for [his/her/your] emotions[ or mental health/, mental health or use of alcohol or drugs]. Do you think [you/he/she] needed this kind of help during the past 12 months?

  • Yes
  • No

Why do you think [you/he/she] did not receive the help [you/he/she] needed during the past 12 months?

Select all that apply.

Would you say:

  • Preferred to self-manage
  • Didn't know how or where to get help
  • Too busy
  • Job interfered
    e.g., workload, hours of work or no cooperation from supervisor
  • Help was not readily available
    e.g., long wait lists
  • Help was not available where you live
  • Had trouble finding or affording transportation
  • Help did not meet [his/her/your] needs
  • Didn't have confidence in health care system or social services
  • Couldn't afford to pay
  • Afraid of what others would think
  • Language or cultural barriers
  • Other
    • Specify other reason

Accessing mental health care

In the past 12 months, did you consult a professional from any of the following places about concerns with your emotions, mental health or use of alcohol or drugs?

Include in-person, telephone and virtual appointments.

Select all that apply.

  • Family doctor or pediatrician's office
  • School
  • Mental health professional's office, such as a psychologist, psychiatrist, social worker or other counselor
  • Community mental health or addictions agency or clinic
  • Walk-in clinic
  • Urgent care clinic or emergency room
  • Hospital
  • Phone helpline or crisis hotline (Include chat and text.)
  • Other

    • Specify other location

    OR

  • None of the above

Earlier, you mentioned that in the past 12 months, you [received professional help for your emotions, mental health or use of alcohol or drugs, but did not receive all the help needed/did not receive professional help for your emotions, mental health or use of alcohol or drugs, but you think you needed this kind of help].

Is there a place that you would have preferred to get the help you needed for your emotions, mental health or use of alcohol or drugs?

Include in-person, telephone and virtual appointments.

Places to consider include the following:

  • Family doctor or pediatrician's office
  • School
  • Mental health professional's office, such as a psychologist, psychiatrist, social worker or other counselor
  • Community mental health or addictions agency or clinic
  • Walk-in clinic
  • Urgent care clinic or emergency room
  • Hospital
  • Phone helpline or crisis hotline
  • Other locations where you could have received the help you needed for your emotions, mental health or use of alcohol or drugs.
  • Yes
  • No

Which of the following places would you have preferred to get the help you needed for your emotions, mental health or use of alcohol or drugs?

Select all that apply.

  • Family doctor or pediatrician's office
  • School
  • Mental health professional's office, such as a psychologist, psychiatrist, social worker or other counselor
  • Community mental health or addictions agency or clinic
  • Walk-in clinic
  • Urgent care clinic or emergency room
  • Hospital
  • Phone helpline or crisis hotline (Include chat and text.)
  • Other
    • Specify other reason

Oral health care

Now some questions about oral health care.

In the past 12 months, how often did [FNAME] experience any persistent or on-going mouth pain?

Include pain in teeth, gums, tongue, jaw, jaw joints.

Would you say:

  • Often
  • Sometimes
  • Rarely
  • Never
  • Don't know

In the past 12 months, how often did [FNAME] avoid eating particular foods because of problems with [his/her] mouth?

Exclude avoiding certain foods because of allergies, orthodontic treatments, and normal tooth processes such as teething and loose baby teeth.

Would you say:

  • Often
  • Sometimes
  • Rarely
  • Never
  • Don't know

Does [FNAME] have any untreated mouth problems?

Mouth problems are defined as any condition that causes pain or discomfort.

For example:

  • abscesses
  • gum issues such as pain and bleeding
  • jaw pain; temporomandibular joints (TMJ)
  • untreated cavities, fillings needing to be replaced
  • tooth pain
  • injuries
  • mouth sores.

Exclude braces or other orthodontic treatments.

  • Yes
  • No
  • Don't know

When was the last time [FNAME] saw a dentist, denturist, dental hygienist or any other dental specialist?

Services may have been provided in any setting where the oral health professional is licensed to practice.

Would you say:

  • Less than one year ago
  • 1 year to less than 3 years ago
  • 3 years ago or more
  • Never seen an oral health professional
  • Don't know

In the past 12 months, have you avoided taking [FNAME] to an oral health professional for dental care due to the cost of care?

An oral health professional may include a dentist, denturist, dental hygienist or any other dental specialist.

  • Yes
  • No
  • Don't know

In the past 12 months, were there any other reasons that [FNAME] did not get dental care or treatment?

Select all that apply.

Would you say:

  • Did not feel it was necessary
  • Indirect costs (e.g., childcare, transportation)
  • Service not available in our area
  • There was a waitlist
  • Oral health professional office was not open at a convenient time
  • Afraid or anxious or do not like receiving oral health care
  • Too busy
  • Health related reasons
  • Language barriers
  • Did not know where to where to do to get treatment
  • I feel that [FNAME] is too young
  • Other reason

    • Specify other reason

    OR

  • No, none of the above
    OR
  • Don't know

Are [FNAME]'s dental expenses fully or partially covered by any insurance plan or government program?

  • Yes
    What type of insurance plan or government program?
    Select all that apply.

    • A plan through an employer
      Include plans that are partially paid or sponsored by an employer.
    • A private plan
      Include personally purchased plans.
    • The Canadian Dental Care Plan
    • A government paid plan other than the Canadian Dental Care Plan
      e.g., children's dental program, Régie de l'assurance maladie du Québec (RAMQ), Non-insured Health Benefits (NIHB) for First Nations and Inuit
    • A plan through college or university

    OR

  • Don't know
  • No
  • Don't know

Injury and poisoning

The following questions are about poisonings that [FNAME] may have had during the past 12 months that were serious enough to limit [his/her] normal activities.

In the past 12 months, did [FNAME] have any poisonings?

Include poisoning by alcohol, cannabis, pharmaceuticals, illicit drugs, and chemicals, including pesticides, heavy metals, gases or vapors, and common household substances, such as bleach and ammonia.

Exclude food poisoning, poison ivy, allergies and skin inflammations caused by an allergic reaction.

  • Yes
    Was it by:
    Select all that apply.
    • Alcohol
    • Cannabis
    • A medicine or drug
    • A chemical
    • Other
  • No

Was a health care professional consulted for [this poisoning/any of these poisonings]?

Include health care professionals from poison centres, paramedics, emergency rooms, family doctor clinic, walk-in clinic, etc.

  • Yes
  • No

The following questions are about injuries that [FNAME] may have had during the past 12 months that were serious enough to limit [his/her] normal activities.

In the past 12 months, did [FNAME] have any of the following types of injuries that were serious enough to limit [his/her] normal activities?

Exclude repetitive strain injuries and chronic back pain.

Select all that apply.

Was it:

  • Head injury
    Include concussions and other traumatic brain injuries, skull or facial fracture.
    Exclude superficial head injuries such as a cut or scrape.
  • Broken or fractured bones
    Exclude skull or facial fracture.
  • Burn, scald or chemical burn
  • Dislocation
  • Sprain or strain
    e.g., torn ligaments or muscles, back strain
  • Cut or puncture
  • Scrape, bruise or blister
  • Animal or human bite
  • Injury to internal organs
  • Other

    • Specify the type of injury

    OR

  • No, none of the above

In the past 12 months, did [FNAME] sustain any of the previously mentioned injuries as a result of a fall?

Include events where [FNAME] came into contact with the ground or any surface at a lower level than where [he/she] was previously, for example by falling from furniture, playground equipment, a window, or a balcony, or by losing his balance.

  • Yes
  • No

In the past 12 months, what was the most serious injury that [FNAME] had as a result of a fall?

The most serious injury was the one that imposed the greatest restriction on normal activities.

Was it:

  • Head injury
    Include concussions and other traumatic brain injuries, skull or facial fracture.
    Exclude superficial head injuries such as a cut or scrape.
  • Broken or fractured bones
    Exclude skull or facial fracture.
  • Burn, scald or chemical burn
  • Dislocation
  • Sprain or strain
    e.g., torn ligaments or muscles, back strain
  • Cut or puncture
  • Scrape, bruise or blister
  • Animal or human bite
  • Injury to internal organs
  • Other
  • [Another injury/[IAP_S15]/Not applicable]

The next questions refer to [FNAME]'s most serious fall-related injury that occurred in the past 12 months.

Which option best describes how this fall happened?

Was it:

  • Playing on playground equipment
    Include indoor or outdoor gym or playground, jungle gym, bouncy castles, trampoline, falls from height on playground equipment
  • Riding or being a passenger on a bike or small wheeled device
    Include non-motorized or motorized: bike, scooter, skateboard, hoverboard.
    Exclude mobility devices such as wheelchair, mobility scooter.
  • Doing a sport or recreational activity
    Exclude playing on playground equipment, riding a bike or small wheeled device.
  • Falling from furniture
    Include bed, bunk bed, chair, sofa, table, counter, crib, change table, highchair.
  • Going up or down stairs or steps
  • Tripping or slipping
    Exclude while doing a sport or recreational activity, playing on playground equipment, while going up or down stairs.
  • Other falls from a height
    Include balcony, window, roof, ladder, tree.
    Exclude playground equipment, furniture, stairs.
  • Other
    • Specify how this fall happened

Was a health care professional consulted for the injury resulting from this fall?

  • Yes
  • No

Earlier, you mentioned that [FNAME] had a head injury. How many times did [he/she] have a head injury in the past 12 months?

Include concussions and other traumatic brain injuries, skull, or facial fracture.

Exclude superficial head injuries such as a cut or scrape.

  • Number of times

The next questions refer to the most serious head injury that occurred in the past 12 months. The most serious head injury was the one that imposed the greatest restriction on normal activities.

It is possible that the event where [FNAME]'s most serious head injury occurred is the same event as the fall you described earlier in question 104. If so, please report the same activity again.

What was [FNAME] doing when [his/her] most serious head injury occurred?

Include concussions and other traumatic brain injuries, skull or facial fracture.

Exclude superficial head injuries such as a cut or scrape.

Was it:

  • Playing on playground equipment
    Include indoor or outdoor gym or playground, jungle gym, bouncy castles, trampoline, falls from height on playground equipment
  • Riding or being a passenger on a bike or small wheeled device
    Include non-motorized or motorized: bike, scooter, skateboard, hoverboard.
    Exclude mobility devices such as wheelchair, mobility scooter.
  • Doing a sport or recreational activity
    Exclude playing on playground equipment, riding a bike or small wheeled device.
  • Falling from furniture
    Include bed, bunk bed, chair, sofa, table, counter, crib, change table, highchair.
  • Going up or down stairs or steps
  • Tripping or slipping
    Exclude while doing a sport or recreational activity, playing on playground equipment, while going up or down stairs.
  • Other falls from a height
    Include balcony, window, roof, ladder, tree.
    Exclude playground equipment, furniture, stairs.
  • Riding or driving a motor vehicle
    Include on-road and off-road motor vehicles, being a passenger.
  • Being assaulted or victimized
    Include if on purpose by another person to cause injuries (e.g., being hit, kicked, attacked, harassed, abused, bullied).
  • Other activity
    • Specify the activity

Was a health professional consulted for this most serious head injury?

Include concussions and other traumatic brain injuries, skull, or facial fracture.

Exclude superficial head injuries such as a cut or scrape.

  • Yes
  • No

School, home and friends

We are interested in how you feel about yourself and how you think other people see you. For each of the following statements, please use "really false for me, sort of false for me, sort of true for me, really true for me" to describe your feelings and ideas in the past week.

  1. I feel I do things well at school
    • Really false for me
    • Sort of false for me
    • Sort of true for me
    • Really true for me
  2. My teachers like me and care about me
    • Really false for me
    • Sort of false for me
    • Sort of true for me
    • Really true for me
  3. I feel free to express myself at home
    • Really false for me
    • Sort of false for me
    • Sort of true for me
    • Really true for me
  4. I feel my teachers think I am good at things
    • Really false for me
    • Sort of false for me
    • Sort of true for me
    • Really true for me
  5. I like to spend time with my parents
    • Really false for me
    • Sort of false for me
    • Sort of true for me
    • Really true for me
  6. I feel free to express myself with my friends
    • Really false for me
    • Sort of false for me
    • Sort of true for me
    • Really true for me
  7. I feel I do things well at home
    • Really false for me
    • Sort of false for me
    • Sort of true for me
    • Really true for me
  8. My parents like me and care about me
    • Really false for me
    • Sort of false for me
    • Sort of true for me
    • Really true for me
  9. I feel I have a choice about when and how to do my school work
    • Really false for me
    • Sort of false for me
    • Sort of true for me
    • Really true for me
  10. I feel my parents think that I am good at things
    • Really false for me
    • Sort of false for me
    • Sort of true for me
    • Really true for me
  11. I like to be with my teachers
    • Really false for me
    • Sort of false for me
    • Sort of true for me
    • Really true for me
  12. I feel I have a choice about which activities to do with my friends
    • Really false for me
    • Sort of false for me
    • Sort of true for me
    • Really true for me
  13. I feel I do things well when I am with my friends
    • Really false for me
    • Sort of false for me
    • Sort of true for me
    • Really true for me
  14. My friends like me and care about me
    • Really false for me
    • Sort of false for me
    • Sort of true for me
    • Really true for me
  15. I feel free to express myself at school
    • Really false for me
    • Sort of false for me
    • Sort of true for me
    • Really true for me
  16. I feel my friends think I am good at things
    • Really false for me
    • Sort of false for me
    • Sort of true for me
    • Really true for me
  17. I like to spend time with my friends
    • Really false for me
    • Sort of false for me
    • Sort of true for me
    • Really true for me
  18. I feel like I have a choice about when and how to do my household chores
    • Really false for me
    • Sort of false for me
    • Sort of true for me
    • Really true for me

Weight, shape and muscles

The next questions ask about your thoughts and behaviours over the past 4 weeks, including how you may have felt about your weight, shape, or muscles, and your eating habits.

In the last 4 weeks, how often did you worry so much about your weight, shape, or muscles that you couldn't get it out of your head?

  • Never
  • Rarely
  • Sometimes
  • Often
  • Always

In the last 4 weeks, how often did you...

  1. not eat, or eat in a way to change your weight, shape, or muscles?
    • Never
    • Once or twice
    • Once or twice each week
    • 3 or 4 times each week
    • 5 or 6 times each week
    • Daily or almost daily
  2. binge on food?
    i.e., eaten what other people would say is an unusually large amount of food such as a whole litre of ice cream, in a few hours.
    • Never
    • Once or twice
    • Once or twice each week
    • 3 or 4 times each week
    • 5 or 6 times each week
    • Daily or almost daily
  3. feel like you couldn't stop eating or couldn't control how much you ate?
    • Never
    • Once or twice
    • Once or twice each week
    • 3 or 4 times each week
    • 5 or 6 times each week
    • Daily or almost daily
  4. vomit or take laxatives to control your weight, shape or muscles?
    • Never
    • Once or twice
    • Once or twice each week
    • 3 or 4 times each week
    • 5 or 6 times each week
    • Daily or almost daily
  5. take any pills, powders, or liquids without a doctor's advice to control your weight, shape or muscles?
    • Never
    • Once or twice
    • Once or twice each week
    • 3 or 4 times each week
    • 5 or 6 times each week
    • Daily or almost daily

Substance use

The following questions are about your experience with several types of substances.

Again, Statistics Canada would like to remind you that all your answers will remain strictly confidential.

Not counting small sips, have you ever had a drink of alcohol?

A "drink" refers to:

  • a small bottle, draft or can of beer, cider or cooler
  • a glass of wine
  • a cocktail or glass containing 1.5 ounces of liquor.
​
  • Yes
  • No

Not counting small sips, how old were you when you had your first drink of alcohol?

  • Age

In the past 12 months, how often did you drink alcohol - liquor (rum, whisky, etc.), wine, beer, or coolers?

Would you say:

  • Never
  • Less than once a month
  • Once a month
  • 2 to 3 times a month
  • Once a week
  • 2 to 3 times a week
  • 4 to 5 times a week
  • Daily or almost daily

How often in the past 12 months have you had [4/5] or more drinks on one occasion?

Would you say:

  • Never
  • Less than once a month
  • Once a month
  • 2 to 3 times a month
  • Once a week
  • More than once a week

In the past 30 days, how often did you drink alcoholic beverages?

Would you say:

  • Never
  • Less than once a week
  • Once a week
  • 2 to 3 times a week
  • 4 to 5 times a week
  • Daily or almost daily

The following questions are about your experiences with smoking cigarettes.

Exclude cigars, little cigars, cigarillos, water-pipes and e-cigarettes.

Have you ever smoked a whole cigarette?

  • Yes
  • No

In your lifetime, have you smoked a total of 100 or more cigarettes (about 4 packs)?

  • Yes
  • No

In the past 30 days, how often did you smoke cigarettes?

Would you say:

  • Never
  • Less than once a week
  • Once a week
  • 2 to 3 times a week
  • 4 to 6 times a week
  • Daily

Now questions about electronic cigarettes (e-cigarettes) or vaping devices.

Have you ever tried an e-cigarette or vaping device, also known as a vape?

Include vaping e-liquid with nicotine and without nicotine i.e., just flavouring.

Exclude vaping cannabis.

  • Yes
  • No

At what age did you first use an e-cigarette or vaping device?

  • Age

In the past 30 days, how often did you use an e-cigarette or vaping device?

Would you say:

  • Never
  • Less than once a week
  • Once a week
  • 2 to 3 times a week
  • 4 to 6 times a week
  • Daily

The last time you used an e-cigarette or vaping device, also known as a vape, what did it contain?

  • An e-cigarette or a vaping device with nicotine
  • An e-cigarette or a vaping device without nicotine
    e.g., just flavouring
  • An e-cigarette or a vaping device but you did not know what it contained

The next few questions are about the use of cannabis for medical and non-medical purposes. The term "cannabis" refers to marijuana, hashish, hash oil or any other product of the cannabis plant.

Have you ever used or tried cannabis?

  • Yes
  • No

At what age did you first try cannabis?

  • Age

How often did you use cannabis in the past 12 months?

Report the average use in the last 12 months.

Would you say:

  • Never
  • Less than once a month
  • 1 to 3 times a month
  • Once a week
  • More than once a week
  • Daily or almost daily

In the past 12 months, which of the following cannabis products have you used?

Select all that apply.

Would you say:

  • Dried flower or leaf
  • Hashish
    e.g., hash, hash oil
  • Cannabis oil for oral use
    e.g., capsules, spray, tincture
  • Cannabis vape pens or cartridges
  • Cannabis concentrates
    e.g., shatter, budder, butane honey oil
  • Cannabis edible food products
    e.g., baked goods, candy, other foods
  • Cannabis beverages
    e.g., cola, tea, coffee
  • Topicals
    e.g., lotion, ointment, creams applied to skin
  • Other
    e.g., seeds
  • Specify other product

In the past 30 days, how often did you use cannabis?

Would you say:

  • Never
  • Less than once a week
  • 1 to 2 days a week
  • 3 to 4 days a week
  • 5 to 6 days a week
  • Daily

How easy or difficult would it be for you to get cannabis or marijuana if you wanted some?

Would you say:

  • Very difficult
  • Fairly difficult
  • Fairly easy
  • Very easy
  • Don't know

Tobacco products alternatives

The following questions are about your use of tobacco and nicotine products other than cigarettes and e-cigarettes.

In the past 30 days, did you use any of the following tobacco products other than cigarettes and e-cigarettes?

  • Nicotine pouch
    These products are sometimes called "white pouches". These products do not contain tobacco; they are smokeless and spit-free.
    e.g., Zonnic®, Zyn®, On!®, Lyft®,  Velo®, Nordic Spirit®, Sesh® or Shiro®
    • Yes
    • No
  • Nicotine gum, nicotine lozenge, nicotine patch, nicotine mouth spray, nicotine nasal spray, or nicotine inhaler
    e.g., Thrive lozenge, Nicoderm patch, Nic-Hit spray, Nicorette gum or Nicorette inhalers
    • Yes
    • No
  • Cigars, cigarillos, or little cigars, a pipe, chewing tobacco, or a tobacco water-pipe
    Include snuff, pinch, hookah, shisha, nargeelay, hubble-bubble or gouza.
    • Yes
    • No
  • A heated tobacco product, also known as a "heat-not-burn" product 
    e.g., iQOS™ or Glo™
    • Yes
    • No

In the past 30 days, how often did you use a nicotine pouch that you put in your mouth?

  • Every day
  • At least once a week
  • At least once in the past month

Drug and medication use

The following questions are about other drugs and medications used to get high or to improve performance and not to follow any health care provider recommendations or prescriptions.

In the past 12 months, have you used or tried any of these drugs or medications to get high or to improve performance?

Exclude any drugs or medications used for a medical reason or prescribed by a health care professional.

Select all that apply.

  • Amphetamines
    Also called speed, crystal meth or ice, meth, crank
  • Cocaine
    Also called crack, blow, snow, rock, freebase
  • Heroin
    Also called smack, junk, horse
  • MDMA or 3-4 methylenedioxymethamphetamine
    Also called ecstasy, E, X, molly
  • Opioid or fentanyl painkillers
    Also called dillies, oxy, percs, hydro, greenies, Apache, China White
    e.g., codeine, oxycodone, fentanyl or fent, morphine, T3, Dilaudid, Percocet
    Exclude over-the-counter medications such as Aspirin®, Tylenol®, Advil® or Motrin®.
  • Hallucinogens
    Also called LSD or lysergic acid diethylamide, acid, magic mushrooms or "shrooms", mesc, tryptamines, DMT, "psychosis", AMT, foxy
  • ADD or ADHD medicine
    e.g., Ritalin®, Concerta®, Adderall®, Dexedrine®, Vyvanse®
    Also called addys, bennies, dexies
  • Sedatives or anti-anxiety medicine
    e.g., Benzodiazepine or "benzos", Ativan®, Xanax®, Valium®, Rivotril®, Ambien®, Lunesta®, Sublinox®
    Also called roofies, xans, tranks
  • Diet pills
  • Performance enhancing drugs for sports and muscle size
    e.g., Depo-Testosterone®, muscle, roids, anabolic steroids
  • Other drugs or medications not used for medical reasons nor prescribed by a health care professional

    • Specify other drugs or medications

    OR

  • None of the above

Moderate physical activity

Thinking of the past 7 days, we would like to record [[FNAME]'s/your] total time spent doing various types of physical activities. Please do not report the same physical activity in more than one of the following questions.

In the past 7 days, did [[FNAME]/you] use active transportation like walking or cycling to get to places?

Active transportation is using non-motorized, human-powered movement to get from one place to another.

Exclude walking, cycling or other activities done purely for leisure. These activities will be asked about later.

Include using active transportation to go to school, daycare or childcare, shopping centres or to visit friends.

  • Yes
  • No

In the past 7 days, how much time in total, did [you/[he/she]] spend using active transportation to get to places?

  • Hours per week
  • Minutes per week

In the past 7 days, did [[FNAME]/you] do physical activities while at school as part of physical education classes, lunch hour, recess, school teams or clubs?

Exclude physical activity you have already reported in this questionnaire.

Include activities organized by the school, regardless of location and whether they take place before or after regular school hours.

  • Yes
    Did any of these physical activities make [[him/her]/you] sweat at least a little or breathe harder?
    • Yes
    • No
  • No

In the past 7 days, how much time in total did [[FNAME]/you] spend doing physical activity while at school that made [[him/her]/you] sweat at least a little or breathe harder?

  • Hours per week
  • Minutes per week

In the past 7 days, did [[FNAME]/you] do physical activities outside of school as part of [[his/her]/your] leisure time?

Exclude physical activity you have already reported in this questionnaire.

Include exercising, playing an organized or non-organized sport or actively playing with friends.

e.g., dance, hockey, martial arts, soccer, pick-up game of basketball, playing at the park, walking or cycling for leisure, hiking.

  • Yes
    Did any of these physical activities make [[him/her]/you] sweat at least a little or breathe harder?
    • Yes
    • No
  • No

In the past 7 days, how much time in total did [[FNAME]/you] spend doing physical activities outside of school that made [[him/her]/you] sweat at least a little or breathe harder?

  • Hours per week
  • Minutes per week

In the past 7 days, did [[FNAME]/you] do tasks that involved being physically active as part of household chores, volunteering, paid or unpaid work?

e.g., cutting grass or yard work, vacuuming or mopping, washing windows.

Exclude physical activity you have already reported in this questionnaire.

  • Yes
    Did any of these physical activities make [[him/her]/you] sweat at least a little or breathe harder?
    • Yes
    • No
  • No

In the past 7 days, how much time in total did [[FNAME]/you] spend doing tasks that involved being physically active as part of household chores, volunteering, paid or unpaid work and that made [[him/her]/you] sweat at least a little or breathe harder?

  • Hours per week
  • Minutes per week

In the past 7 days, how many hours per day did [FNAME] actively play?

Include: energetic play indoors or outdoors, for example, playing tag or ball games, crawling or running around, riding a bike or scooter, and swinging, climbing, or sliding on play structures.

Exclude: light intensity activities such as standing up, walking around, or playing with toys or in the sand or snow while seated.

  • Never
  • Less than 30 minutes per day
  • 30 minutes to less than 1 hour per day
  • 1 to less than 2 hours per day
  • 2 to less than 3 hours per day
  • 3 or more hours per day

In the previous questions, [[FNAME]/you] recorded a total time spent doing various types of physical activities of: [Sum of hours and minutes] in the past 7 days.

This includes active transportation and physical activities that made [[him/her]/you] sweat at least a little or breathe harder.

If this is correct, please click "Next" to continue. If not, please return and correct.

Parent-child interaction

How often…

  1. do you praise [FNAME] by saying something like "Good for you!" or "What a nice thing you did!" or "That's good going!"?
    • Never
    • About once a week or less
    • A few times a week
    • One or two times a day
    • Many times a day
  2. do you and [FNAME] talk or play with each other, focusing attention on each other for five minutes or more, just for fun?
    • Never
    • About once a week or less
    • A few times a week
    • One or two times a day
    • Many times a day
  3. do you and [FNAME] laugh together?
    • Never
    • About once a week or less
    • A few times a week
    • One or two times a day
    • Many times a day
  4. do you do something special with [FNAME] that [he/she] enjoys?
    • Never
    • About once a week or less
    • A few times a week
    • One or two times a day
    • Many times a day
  5. do you play sports, hobbies or games with [FNAME]?
    • Never
    • About once a week or less
    • A few times a week
    • One or two times a day
    • Many times a day

Eating Habits

The next questions are about some of [[FNAME]'s/your] eating and drinking habits.

In the past 30 days, how many meals did [[FNAME]/you] eat that were prepared away from home in places such as restaurants, fast-food places, grocery stores, or delivery?

Exclude meals provided as part of a daycare meal plan, school-provided lunch or breakfast program.

Include fast-food, take-out, sit-down restaurants, prepared food from grocery stores, and paid school lunches where restaurant food was brought in (e.g., pizza days)

Frequency can be reported per month, per week or per day.

  • Number of times
  • Per month, per week or per day
    • Per month
    • Per week
    • Per day

How many of those meals did [[FNAME]/you] eat from a fast-food restaurant (e.g., burgers, pizza, hot dogs, fried potatoes, fried chicken, submarines or sandwiches, tacos, etc.)?

Frequency can be reported per month, per week or per day.

  • Number of times
  • Per month, per week or per day
    • Per month
    • Per week
    • Per day

In the past 30 days, how many times did [[FNAME]/you] drink the following beverages?

Please note that some of the foods listed are regional and may not be available where you live.

Frequency can be reported per month, per week or per day.

  1. 100% pure fruit juice
    • Number of times
    • Per month, per week or per day
      • Per month
      • Per week
      • Per day
  2. Fruit flavoured drinks or sports drinks
    e.g., Fruité™, fruit punch, Gatorade™
    Exclude artificially sweetened drinks.
    • Number of times
    • Per month, per week or per day
      • Per month
      • Per week
      • Per day
  3. Regular soft drinks
    Exclude diet soft drinks.
    • Number of times
    • Per month, per week or per day
      • Per month
      • Per week
      • Per day
  4. Sweetened coffee drinks or iced tea
    e.g., Starbucks™ Macchiato, Tim Hortons Ice Capp™, Nestea™, coffee or tea with sugar added
    • Number of times
    • Per month, per week or per day
      • Per month
      • Per week
      • Per day
  5. Energy drinks
    e.g., Red Bull™, Monster™
    • Number of times
    • Per month, per week or per day
      • Per month
      • Per week
      • Per day
  6. Sweetened flavoured milk or sweetened plant-based beverage
    e.g., Chocolate, strawberry or vanilla Milk2Go™, Earth's Own original oat milk™, Silk almond vanilla™, Neilson CARAMILK ™or Crispy Crunch milkshake™, Nesquik™
    Exclude yogurt drinks.
    • Number of times
    • Per month, per week or per day
      • Per month
      • Per week
      • Per day

In the past 30 days, how many times did [[FNAME]/you] eat the following fruits and vegetables?  

Please note that some of the foods listed are regional and may not be available where you live.

Include fresh, frozen, canned or dried.

Include only foods that [[FNAME]/you] actually consumed.

Frequency can be reported per month, per week or per day.

  1. Fruits
    Exclude fruit juices.
    • Number of times
    • Per month, per week or per day
      • Per month
      • Per week
      • Per day
  2. Dark green vegetables
    e.g., broccoli, green beans, dark lettuce, spinach
    • Number of times
    • Per month, per week or per day
      • Per month
      • Per week
      • Per day
  3. Orange-coloured vegetables
    e.g., carrots, orange bell peppers, sweet potatoes
    • Number of times
    • Per month, per week or per day
      • Per month
      • Per week
      • Per day
  4. Starchy vegetables
    e.g., white potatoes, corn 
    Exclude deep fried potatoes.
    • Number of times
    • Per month, per week or per day
      • Per month
      • Per week
      • Per day
  5. Other vegetables
    e.g., cucumber, celery, cabbage, tomatoes, cauliflower
    • Number of times
    • Per month, per week or per day
      • Per month
      • Per week
      • Per day

Canada's Food Guide use

[Has/Have] [FNAME/you] ever seen or heard of Canada's Food Guide?

  • Yes
  • No
  • Don't know

Have you ever used information from Canada's Food Guide?

  • Yes
  • No

What did you use the information for?

Select all that apply.

Would you say:

  • To choose foods
  • To determine how much to eat every day
  • To plan meals or to help with grocery shopping
  • To assess how well you are eating
  • Other

Food advertising

The following questions are about advertisements on food and drinks.

How often does [FNAME] ask you to buy food or drinks [he/she] has seen advertised?

e.g., soda or pop, sports and energy drinks; juice and flavoured milks; fast food; sugary cereals; chips, crackers and granola bars; desserts and treats

Advertisements include those on tv, social media, on food packages, on billboards, etc.

Would you say:

  • Very frequently
  • Frequently
  • Occasionally
  • Rarely
  • Very rarely
  • Never

In general, how often do you buy these foods or beverages requested by [FNAME]?

e.g., soda or pop, sports and energy drinks; juice and flavoured milks; fast food; sugary cereals; chips, crackers and granola bars; desserts and treats

Would you say:

  • Very frequently
  • Frequently
  • Occasionally
  • Rarely
  • Very rarely
  • Never

Healthy living and electronic devices

Now a few questions about [[FNAME]'s/your] sleep habits in the past 7 days.

On a typical day, how much time in total did [[FNAME]/you] sleep, [including/excluding] any time spent napping?

  1. Weekday
    • Hours per day
    • Minutes per day
  2. Weekend day
    • Hours per day
    • Minutes per day

In the past 7 days, how often did [FNAME] have trouble sleeping?

Would you say:

  • Never
  • Rarely
  • Sometimes
  • Most of the time
  • All the time

In the past 7 days, how often did [[FNAME]/you] have trouble going to sleep or staying asleep?

Would you say:

  • Never
  • Rarely
  • Sometimes
  • Most of the time
  • All the time

For the next question, think about all the time [[FNAME]/you] used any electronic device in [his/her/your] free time in the past 7 days.

In the past 7 days, how much time on a typical day did [[FNAME]/you] spend using any electronic device such as a mobile device, computer, tablet, video game console or television while [he/she/you] [was/were] sitting or lying down?

Exclude time spent in class, doing homework, or reading for enjoyment.

  1. Weekday
    • Hours per day
    • Minutes per day
  2. Weekend day
    • Hours per day
    • Minutes per day

Food Security

The following statements may describe the food situation for your household in the past 12 months. Please indicate if the statement was often true, sometimes true, or never true for [you/you and other household members].

  1. [You/You and other household members] worried that food would run out before you got money to buy more
    • Often true
    • Sometimes true
    • Never true
  2. The food that [you/you and other household members] bought just didn't last and there wasn't any money to get more
    • Often true
    • Sometimes true
    • Never true
  3. [You/You and other household members] couldn't afford to eat balanced meals
    • Often true
    • Sometimes true
    • Never true
  4. [You/You or other adults in your household] relied on only a few kinds of low-cost food to feed [[FNAME]/the children] because you were running out of money to buy food
    • Often true
    • Sometimes true
    • Never true
  5. [You/You or other adults in your household] couldn't feed [[FNAME]/the children] a balanced meal because you couldn't afford it
    • Often true
    • Sometimes true
    • Never true

[[FNAME] was/The children were] not eating enough because [you/you or other adults in your household] just couldn't afford enough food.

Would you say:

  • Often true
  • Sometimes true
  • Never true

The following few questions are about the food situation in the past 12 months for you or any other adults in your household.

In the past 12 months, since last [January/February/March/April/May/June/July/August/September/October/November/December], did [you/you or other adults in your household] ever cut the size of your meals or skip meals because there wasn't enough money for food?

  • Yes
    How often did this happen?
    Was it:
    • Almost every month
    • Some months but not every month
    • Only 1 or 2 months
  • No

In the past 12 months, did you (personally) ever eat less than you felt you should because there wasn't enough money to buy food?

  • Yes
  • No

In the past 12 months, were you (personally) ever hungry but didn't eat because you couldn't afford enough food?

  • Yes
  • No

In the past 12 months, did you (personally) lose weight because you didn't have enough money for food?

  • Yes
  • No

In the past 12 months, did [you/you or other adults in your household] ever not eat for a whole day because there wasn't enough money for food?

  • Yes
    How often did this happen?
    Was it:
    • Almost every month
    • Some months but not every month
    • Only 1 or 2 months
  • No

Now, a few questions on the food experiences for children in your household.

In the past 12 months, did [you/you or other adults in your household] ever cut the size of [[FNAME]'s/any of the children's] meals because there wasn't enough money for food?

  • Yes
  • No

In the past 12 months, did [[FNAME]/any of the children] ever skip meals because there wasn't enough money for food?

  • Yes
    How often did this happen?
    Was it:
    • Almost every month
    • Some months but not every month
    • Only 1 or 2 months
  • No

In the past 12 months, [was [FNAME]/were any of the children] ever hungry but you just couldn't afford more food?

  • Yes
  • No

In the past 12 months, did [[FNAME]/any of the children] ever not eat for a whole day because there wasn't enough money for food?

  • Yes
  • No

School attendance

In a typical week, does [FNAME] attend school?

e.g., any level of kindergarten, primary, secondary, post-secondary

Exclude online learning, homeschooling and any child care such as daycare and preschool.

  • Yes
  • No

What is the main reason that [FNAME] is not currently attending school?

Is it:

  • [FNAME] is too young to attend school
  • [FNAME] is homeschooled
  • Illness
  • Dropped out
  • Graduated from high school and planning to attend post-secondary school
  • Graduated from high school and not currently planning to attend post-secondary school
  • Graduated from both high school and post-secondary school
  • Other
    • Specify other reason

School food programs

The next few questions are about school food programs. These programs regularly provide meals or snacks to children to help children have access to nutritious food. These programs are typically free or offered at a lower cost.

Thinking about this definition, would you say [[FNAME]'s/your] school has a school food program that offers snacks or meals at a lower cost or free?

Include breakfast, lunch and snack programs that provide foods such as cereal, fruits, sandwiches, pasta, yogurt, granola bars, etc. 
Do not count food paid for at full cost from a canteen, cafeteria or ordered from a restaurant, and occasional lunches such as "pizza days".

  • Yes
  • No
  • Does not apply to me
    e.g., I don't go to school, I attend home-school, I attend school online
  • Don't know

[Has/Have] [[FNAME]/you] ever used the school food program at [his/her/your] current school?

  • Yes
  • No
  • Don't know

How often [does/do] [[FNAME]/you] usually eat meals or snacks from the school food program?

Would you say:

  • Less than once a week
  • Once a week
  • A few days a week
  • Every school day

What type of meal or snack from the school food program [does/do] [[FNAME]/you] usually eat?

Select all that apply.

Would you say:

  • Breakfast
  • Lunch
  • Snack
  • Other
    • Specify other type of meal or snack

What are the benefits of [[FNAME]'s/your] participation in the school food program?

Select all that apply.

Would you say:

  • It saves money on food and groceries
  • It saves time and energy on preparing food
  • [He/She/You] [is/are] less hungry while at school
  • [He/She/You] eat[s/] healthy food
  • [He/She/You] [is/are] more motivated to go to school
  • [He/She/You] [is/are] better able to focus in class
  • [He/She/You] feel[s/] included with other children
  • [He/She/You]  learn[s/] about healthy food, where food comes from, or reducing food waste
  • The program serves food aligned with [[FNAME]'s/your] culture or religion
  • [He/She/You] explore[s/] new foods that [he/she/you] might not normally try
  • Other

    • Specify other benefit

    OR

  • There is no benefit

Child Care Services

The following questions are about [FNAME] and [his/her] usual child care arrangements.

By child care arrangements, we mean any care provided to children by someone other than the parent or guardian, including formal and informal arrangements, licensed and unlicensed arrangements, full-time and part-time arrangements as well as paid and unpaid arrangements.

In the past three months, did [FNAME] usually attend any child care arrangements?

Include:

  • use of daycare facilities, home-based child care providers, or before or after school programs, pre-school programs
  • child care provided by a relative other than a parent or guardian, for example, a grandparent or sibling
  • child care provided by a non-relative in the child's home, for example, a nanny.

Exclude:

  • parents or guardians looking after their own children, including homeschooling
  • child care provided by the child's own parent or guardian operating a home-based child care business
  • school attendance, for example, any level of kindergarten, pre-primary, grade primary, primary and elementary school
  • school lunch supervision
  • occasional babysitting.
  • Yes
  • No

In the past three months, which of the following child care arrangements did you usually use for [FNAME]?

Select all that apply.

  • Before or after school program
    e.g., a program located in a school, a community centre, a library, etc.
  • Daycare centre, preschool or centre de la petite enfance (CPE)
  • Child care by a relative other than a parent or guardian
    e.g., a grandparent or sibling
  • Child care by a non-relative in the child's home
    e.g., a nanny
  • Home-based child care provider
    e.g., family child care home or home-based daycare service
  • Other child care arrangement
    • Specify other child care arrangement

Family History

The following questions are about [[FNAME]'s/your] family.

[Has [FNAME]/Have you] experienced the separation or divorce of a parent?

  • Yes
  • No

Does [FNAME] have a living parent or guardian who does not reside in this household?

  • Yes
  • No

In the past 12 months, what type of contact has [FNAME] had with the other parent or guardian?

Would you say:

  • Lives equally with both parents or guardians
  • Overnight visits
  • In-person visits, but did not stay overnight
  • Video call or chat, telephone, letter or email contact only
  • No contact
  • Other

In the past 12 months, how often did the other parent or guardian contact [FNAME] when [he/she] was not living at the other parent or guardian's household?

Include phone calls, text messages, emails or video chats.

  • Daily
  • At least once a week
  • At least once a month
  • Less than once a month
  • Not at all

Sexual orientation

This question collects information on sexual orientation to inform programs that promote equal opportunity for everyone living in Canada to share in its social, cultural, and economic life.

What is your sexual orientation?

Sexual orientation refers to how a person describes their sexuality.

Would you say:

  • Heterosexual (i.e., straight)
  • Lesbian or gay
  • Bisexual or pansexual
  • Or please specify
    • Specify your sexual orientation

Language

The following sections consist of demographic questions about the identified individual or individuals. Please answer each question to the best of your knowledge.

Can [this person/you] speak English or French well enough to conduct a conversation?

For a child who has not yet learned to speak, report the language(s) that the child is learning to speak at home.

> [FNAME] :

  • English only
  • French only
  • Both English and French
  • Neither English nor French

> You:

  • English only
  • French only
  • Both English and French
  • Neither English nor French

> [First name of PMK spouse/Your spouse or partner]:

  • English only
  • French only
  • Both English and French
  • Neither English nor French

What language [does this person/do you] speak most often at home?

For a child who has not yet learned to speak, report the language spoken most often to this child at home.

> [FNAME] :

  • English
  • French
  • Other
    • Specify other language

> You:

  • English
  • French
  • Other
    • Specify other language

> [First name of PMK spouse/Your spouse or partner]:

  • English
  • French
  • Other
    • Specify other language

Place of birth, immigration and citizenship

Where was this person born?

Specify place of birth according to present boundaries.

> [FNAME] :

  • Born in Canada
  • Born outside Canada
    • Select the country
      To search for a country, type the first few letters to narrow down the choices.
      Note: If the country is not listed, select "Other".
      • Specify other country

> You:

  • Born in Canada
  • Born outside Canada
    • Select the country
      To search for a country, type the first few letters to narrow down the choices.
      Note: If the country is not listed, select "Other".
      • Specify other country

> [First name of PMK spouse/Your spouse or partner]:

  • Born in Canada
  • Born outside Canada
    • Select the country
      To search for a country, type the first few letters to narrow down the choices.
      Note: If the country is not listed, select "Other".
      • Specify other country

In what year did this person first come to Canada to live?

If exact year is not known, enter best estimate.

> [FNAME] :

  • Year of arrival

> You:

  • Year of arrival

> [First name of PMK spouse/Your spouse or partner]:

  • Year of arrival

Is this person now, or has this person ever been a landed immigrant?

A "landed immigrant" (permanent resident) is a person who has been granted the right to live in Canada permanently by immigration authorities.

> [FNAME] :

  • Yes
    In what year did [[FNAME]/you] first become a landed immigrant?
    If exact year is not known, enter best estimate.
    • Year of immigration
  • No

> You:

  • Yes
    In what year did you first become a landed immigrant?
    If exact year is not known, enter best estimate.
    • Year of immigration
  • No

> [First name of PMK spouse/Your spouse or partner]:

  • Yes
    In what year did this person first become a landed immigrant?
    If exact year is not known, enter best estimate.
    • Year of immigration
  • No

Of what country is this person a citizen?

Indicate more than one citizenship, if applicable.

> Is [FNAME] a citizen of:
Select all that apply.

  • Canada
    Is it:
    • By birth
    • By naturalization
      i.e., the process by which an immigrant is granted citizenship of Canada, under the Citizenship Act.
  • Another country

> Are you a citizen of :
Select all that apply.

  • Canada
    Is it:
    • By birth
    • By naturalization
      i.e., the process by which an immigrant is granted citizenship of Canada, under the Citizenship Act.
  • Another country

> Is [First name of PMK spouse/your spouse or partner] a citizen of:
Select all that apply.

  • Canada
    Is it:
    • By birth
    • By naturalization
      i.e., the process by which an immigrant is granted citizenship of Canada, under the Citizenship Act.
  • Another country

Indigenous identity

Is this person First Nations, Métis or Inuk (Inuit)?

First Nations (North American Indian) includes Status and Non-Status Indians.
If "Yes", select the responses that best describes this person now.

> [FNAME] :

  • No, not First Nations, Métis or Inuk (Inuit)
    OR
  • Yes, First Nations (North American Indian)
  • Yes, Métis
  • Yes, Inuk (Inuit)

> You:

  • No, not First Nations, Métis or Inuk (Inuit)
    OR
  • Yes, First Nations (North American Indian)
  • Yes, Métis
  • Yes, Inuk (Inuit)

> [First name of PMK spouse/Your spouse or partner]:

  • No, not First Nations, Métis or Inuk (Inuit)
    OR
  • Yes, First Nations (North American Indian)
  • Yes, Métis
  • Yes, Inuk (Inuit)

Sociodemographic characteristics

The following question collects information to support programs that promote equal opportunity for everyone to share in the social, cultural and economic life of Canada.

Which population group or groups best describe this person?

Select all groups that apply, or specify another group, if applicable.

> [FNAME] :

  • White
  • South Asian
    For example, Indian, Pakistani, Sri Lankan
  • Chinese
  • Black
  • Filipino
  • Arab
  • Latin American
  • Southeast Asian
    For example, Vietnamese, Cambodian, Laotian, Thai
  • West Asian
    For example, Iranian, Afghan
  • Korean
  • Japanese
  • Or please specify
    • Specify another group

> You:

  • White
  • South Asian
    For example, Indian, Pakistani, Sri Lankan
  • Chinese
  • Black
  • Filipino
  • Arab
  • Latin American
  • Southeast Asian
    For example, Vietnamese, Cambodian, Laotian, Thai
  • West Asian
    For example, Iranian, Afghan
  • Korean
  • Japanese
  • Or please specify
    • Specify another group

> [First name of PMK spouse/Your spouse or partner]:

  • White
  • South Asian
    For example, Indian, Pakistani, Sri Lankan
  • Chinese
  • Black
  • Filipino
  • Arab
  • Latin American
  • Southeast Asian
    For example, Vietnamese, Cambodian, Laotian, Thai
  • West Asian
    For example, Iranian, Afghan
  • Korean
  • Japanese
  • Or please specify
    • Specify another group

Education

What is the highest certificate, diploma or degree that this person has completed?

> You:

  • Less than high school diploma or its equivalent
  • High school diploma or a high school equivalency certificate
  • Trades certificate or diploma
  • College, CEGEP or other non-university certificate or diploma (other than trades certificates or diplomas)
  • University certificate or diploma below the bachelor's level
  • Bachelor's degree
    e.g., B.A., B.A. (Hons), B.Sc., B.Ed., LL.B.
  • University certificate, diploma or degree above the bachelor's level

> [First name of PMK spouse/Your spouse or partner]:

  • Less than high school diploma or its equivalent
  • High school diploma or a high school equivalency certificate
  • Trades certificate or diploma
  • College, CEGEP or other non-university certificate or diploma (other than trades certificates or diplomas)
  • University certificate or diploma below the bachelor's level
  • Bachelor's degree
    e.g., B.A., B.A. (Hons), B.Sc., B.Ed., LL.B.
  • University certificate, diploma or degree above the bachelor's level

Labour market activities

Many of the following questions concern work activities last week.

Last week is from last [day of interview] to yesterday.

Last week, did this person work at a job or business?

Select "Yes" if this person worked at least one hour:

  • for pay (wages, salary, etc.)
  • in self-employment.

Select "No" if this person:

  • was away from work for the entire week for a reason such as vacation, illness, work schedule or layoff
  • did not have a job or business.

> You:

  • Yes
  • No

> [First name of PMK spouse/Your spouse or partner]:

  • Yes
  • No

Last week, did this person have a job or business from which he or she was absent?

Select "Yes" if this person:

  • was away from work for the entire week for a reason such as vacation, illness, parental leave or work schedule
  • was self-employed with a business, but no work was available.

Select "No" if this person:

  • did not have a job or business
  • had a casual job, but no work was available.

> You:

  • Yes
  • No

> [First name of PMK spouse/Your spouse or partner]:

  • Yes
  • No

What was the main reason this person was absent from work last week?

> You:

  • Vacation
  • Own illness or disability
  • Caring for own children
  • Caring for elder relative
    60 years of age or older
  • Maternity or parental leave
  • Other personal or family responsibilities
  • Labour dispute (strike or lockout)
    Employees only
  • Temporary layoff due to business conditions
    Employees only
  • Seasonal layoff
    Employees only
  • Casual job, no work available
    Employees only
  • Work schedule
    e.g., 10 days on, 10 days off, employees only
  • Self-employed, no work available
    Self-employed only
  • Seasonal business
    Excluding employees
  • Other, specify
    • Specify the main reason you were absent from work last week

> [First name of PMK spouse/Your spouse or partner]:

  • Vacation
  • Own illness or disability
  • Caring for own children
  • Caring for elder relative
    60 years of age or older
  • Maternity or parental leave
  • Other personal or family responsibilities
  • Labour dispute (strike or lockout)
    Employees only
  • Temporary layoff due to business conditions
    Employees only
  • Seasonal layoff
    Employees only
  • Casual job, no work available
    Employees only
  • Work schedule
    e.g., 10 days on, 10 days off, employees only
  • Self-employed, no work available
    Self-employed only
  • Seasonal business
    Excluding employees
  • Other, specify
    • Specify the main reason

Administrative information

To enhance the data from this survey and to minimize the reporting burden for respondents, [Statistics Canada and your provincial ministry of health and the Institut de la statistique du Québec/Statistics Canada and your ministry of health] may combine [your responses and [FNAME]'s/your responses] with information from other surveys or administrative sources.

[Does [FNAME]/Do you] have [a Newfoundland and Labrador/a Prince Edward Island/a Nova Scotia/a New Brunswick/a Quebec/an Ontario/a Manitoba/a Saskatchewan/an Alberta/a British Columbia/a Yukon/a Northwest Territories/a Nunavut] health number?

Having a provincial or territorial health number will assist us in linking to this other information.

  • Yes
  • No

For which province or territory is [[FNAME]'s/your] health number?

If you do not have a Canadian health number, select "No Canadian health number" from the dropdown.
 

  • Province or territory
    • Alberta
    • British Columbia
    • Manitoba
    • New Brunswick
    • Newfoundland and Labrador
    • Northwest Territories
    • Nova Scotia
    • Nunavut
    • Ontario
    • Prince Edward Island
    • Quebec
    • Saskatchewan
    • Yukon
    • No Canadian health number

What is [[FNAME]'s/your] health number?

Enter a health number for [Newfoundland and Labrador/Prince Edward Island/Nova Scotia/New Brunswick/Quebec/Ontario/Manitoba/Saskatchewan/Alberta/British Columbia/Yukon/the Northwest Territories/Nunavut]. In [Newfoundland and Labrador/Prince Edward Island/Nova Scotia/New Brunswick/Quebec/Ontario/Manitoba/Saskatchewan/Alberta/British Columbia/Yukon/the Northwest Territories/Nunavut], the health number is made up of [twelve numbers/eight numbers/ten numbers/nine numbers/four letters followed by eight numbers/ten numbers. Do not include the two letters at the end for green health cards/nine numbers, beginning with 002 or 003/one letter followed by seven numbers].

Do not insert blanks, hyphens or commas between the numbers.

[Note: In Manitoba, health numbers of a family's members can be listed on the same card.  Be sure to capture [FNAME]'s health number if there is more than one on the card/Note: In British Columbia, residents may have a combined driver's license and health card. If [FNAME] has a combined card, the health number is on the back above the barcode./]

  • Health number

To avoid duplication of surveys, Statistics Canada has signed agreements to share the data from this survey with provincial and territorial ministries of health [and the Institut de la statistique du Québec]. Provincial or territorial ministries of health [and the Institut de la statistique du Québec] may make the data available to local health authorities.

Data shared with your ministry of health [and the Institut de la statistique du Québec] may also include identifiers such as name, address, telephone number and health card number. Local health authorities would receive only survey responses and the postal code.

These organizations have agreed to keep the data confidential and use it only for statistical purposes.

Do you agree to share the information [you and [FNAME]/you] provided?

  • Yes
  • No

To avoid duplication of surveys, Statistics Canada has signed agreements to share the data from this survey with provincial and territorial ministries of health [and the Institut de la statistique du Québec]. The [Institut de la statistique du Québec and] provincial or territorial ministries of health may make this data available to local health authorities.

Data shared with your ministry of health [and the Institut de la statistique du Québec] may also include identifiers such as name, address, telephone number and health card number. Local health authorities would receive only survey responses and the postal code.

These organizations have agreed to keep the data confidential and use it only for statistical purposes.

As a reminder, information about you collected through this survey includes the answers provided by you and those provided about you by your parent or legal guardian.

Do you give your consent for Statistics Canada to share the information about you that you and your parent or legal guardian provided as part of this survey with these organizations?

  • Yes
  • No

Thank you for completing the Canadian Health Survey on Children and Youth!

If applicable to your secondary school program, you can now request proof that confirms that you volunteered to complete the survey as part of your community involvement activities.

If you need this proof of participation, select "Yes" to the question below and confirm your contact information. Statistics Canada will send you an email with proof of participation by Spring 2027.

Do you need Statistics Canada to provide proof of participation in this survey?

  • Yes
  • No

So that Statistics Canada can provide you with proof of participation in this survey, please verify your contact information and correct it if necessary.

  • First name:
    • Prefilled with [youth's first name]
  • Last name:
    • Prefilled with [youth's last name]
  • Email:
    • Prefilled with [email address]

Survey on Research Activities and Commercialization of Intellectual Property in Higher Education (SRACIPHE) 2025 — Glossary

This glossary provides definitions of key terms used in the Survey on Research Activities and Commercialization of Intellectual Property in Higher Education (SRACIPHE).

Affiliated legal entity: A legally distinct organization that has a formal relationship with a postsecondary institution, such as an affiliated college, centres collégiaux de transfert de technologie et de pratiques sociales novatrices (college centres for the transfer of technology and innovative social practices; CCTT) research institute, technology transfer organization or other related entity, and whose activities may be reported separately or included in a combined report, as permitted by the survey.

Centre collégial de transfert de technologie (CCTT): A Quebec-based college technology transfer centre that supports applied research and technology transfer to industry.

Collaborative research agreement: A project-specific agreement under which two or more organizations jointly undertake research activities and share expertise, resources, facilities or research outcomes with no external funds brought to the reporting institution.

Copyrights: A form of intellectual property that protects original works, including scientific publications, software code, artistic works, technical documentation and other creative outputs arising from research or innovation activities

Field and environmental infrastructures: Research facilities and sites located in natural or controlled environments that support data collection, monitoring, observation or experimentation outside traditional laboratory settings. Examples include observatories, field stations, experimental farms and environmental monitoring sites.

Full-time equivalent (FTE): A measure of work effort expressed as the total hours worked divided by the average annual hours worked in a full-time position.

Grant-based research agreements: A research project funded through a formal grant from a government, non-profit organization or other funding body, where the funding is subject to specified terms and conditions related to project activities, reporting or intellectual property.

Industrial design: A form of intellectual property that protects the visual features of a product, including its shape, configuration, pattern or ornamentation.

Institutional-level research partnership agreement: A formal, ongoing collaboration framework between an institution and an external organization that supports multiple or future research projects. Formal research partnerships are broader than individual project-specific research agreements.

Integrated circuit topographies: A recognized form of intellectual property in Canada that protects the three-dimensional layout design of the electronic components and connections within a semiconductor integrated circuit.

Intellectual property (IP): Assets arising from creations of the mind that may be legally protected. Examples include patents for inventions, copyrights for original works, trademarks for names and logos, trade secrets for confidential information and industrial designs for the visual appearance of products.

Intellectual property (IP) commercialization: Activities that support the transfer, development or use of intellectual property arising from research or innovation. Commercialization pathways may include licensing, assignment (sale of intellectual property), spin-offs, start-ups and collaborative partnerships.

Intellectual property (IP) licence: A legal agreement that grants a person or organization permission to use, develop, or otherwise exploit intellectual property (IP) owned by another party under specified terms and conditions. Ownership of the intellectual property remains with the licensor. Licences allow use without transferring ownership.

Intellectual property (IP) management: Activities related to the identification, assessment, protection, administration, transfer and licensing of intellectual property (IP). These activities may include invention disclosures, IP assessment, patenting, licensing, management of IP assets and portfolios, negotiation of IP-related agreements, and support for the commercialization of intellectual property.

Intellectual property (IP) support: Advisory, educational or facilitation services related to intellectual property. These services may include disclosure support, patent strategy advice, IP-related industry liaison activities, training, outreach or other assistance that supports intellectual property activities without necessarily involving ownership or direct management of intellectual property.

Invention disclosure: A formal notification submitted to an institution that describes a potentially protectable invention, design, copyright, plant variety, software, algorithm, trade secret, trademark or other intellectual property arising from research or innovation activities. Invention disclosures are used to evaluate, manage, protect or support the commercialization of intellectual property.

Inventions: A novel product, process or technical solution arising from research, experimental development or other creative activity. An invention may be eligible for protection through intellectual property rights such as patents.

New product: A good or service that is new or significantly improved during the reporting period with respect to its characteristics, functionality, software, components, materials or intended use, and that reached final development, demonstration, qualification, deployment, operational use or commercialization during the reporting period. Minor modifications or routine updates are not considered new or improved products.

New or improved process: A method, technique, procedure or system that is new or significantly improved during the reporting period and is used to produce, deliver or support goods, services or other activities. Improvements may include changes to workflows, manufacturing methods, operational practices, equipment or software. For this survey, report only processes that reached final development, demonstration, qualification, deployment, operational use or commercialization during the reporting period.

New or improved prototype: A preliminary or functional version of a product, process or technology that is new or significantly improved during the reporting period and is developed to test, demonstrate, validate or refine a concept, design or technical solution before full implementation, deployment or commercialization. For this survey, report only prototypes that reached final development, demonstration, qualification, deployment, operational use or commercialization during the reporting period.

Patent: A form of intellectual property that grants the owner the exclusive right, for a limited period, to prevent others from making, using or selling an invention without permission in the jurisdictions where the patent is granted.

Patent application: A formal request submitted to a patent office seeking patent protection for an invention.

Plant variety rights: A form of intellectual property that protects new plant varieties and grants the breeder exclusive rights over the propagation and commercialization of the variety.

Research and development (R&D): Creative and systematic work undertaken to increase the stock of knowledge and to develop new applications of that knowledge. For the purposes of this survey, the terms research and research and development (R&D) include basic research, applied research, and experimental development, where applicable to the institution completing this form. These activities are defined according to the Frascati Manual:

  • Basic research: Experimental or theoretical work undertaken primarily to acquire new knowledge without a specific practical application in view.
  • Applied research: Original investigation undertaken to acquire new knowledge directed primarily towards a specific practical aim or objective.
  • Experimental development: Systematic work that draws on existing knowledge and practical experience to develop new or improved products, processes, or services.

Research services / testing agreements: A fee-for-service arrangement in which an institution provides research, testing or analysis for an external organization according to agreed requirements and deliverables.

Spin-off: For this survey, a spin-off is a company created to commercialize intellectual property (IP) or technology developed at the institution.

A spin-off must have a formal and verifiable link to IP developed at the institution. This includes companies where at least one of the following conditions applies:

  • The company has licensed IP (e.g., patents, software or know-how) from the institution.
  • The company is based on an invention disclosure submitted to the institution.
  • The institution holds equity in the company as a result of an IP contribution.

Exclude:

  • Companies based solely on knowledge, skills or experience acquired at the institution without a documented link to institutional IP, even if they receive support through incubators, accelerators or mentorship programs.
  • Start-ups founded by students, graduates, faculty or staff that do not have a formal relationship to IP developed at the institution.

Start-ups: A start-up is a new company created to address a market need, typically built on a novel idea or technology and supported by a business plan and growth strategy. 

For the purpose of this survey, start-up refers to a business that may receive support from this institution, but where there is no formal or verifiable relationship to IP developed at this institution.

Start-ups may include student-led ventures, incubator or accelerator-supported companies or external clients.

Sponsored or contract research agreement: A project-specific research agreement under which an external organization funds research activities in exchange for defined deliverables, timelines or reporting requirements.

Technology access centre (TAC): A specialized applied research and innovation centre affiliated with a Canadian college or CEGEP that provides applied research, testing, technical services and innovation support to external organizations, particularly small and medium-sized enterprises (SMEs), to support technology development, adoption, commercialization and the resolution of business or technical challenges.

Technology readiness levels (TRLs): A scale used to assess the maturity of a technology, product, process or prototype as it progresses from research and development to deployment and operational use.

  • TRL 1–3: Research, concept development and proof of concept.
  • TRL 4–6: Validation, refinement and testing in laboratory, simulated or relevant operational environments.
  • TRL 7–9: Demonstration, qualification, deployment and operational use.

Technology transfer office (TTO): An office that supports the identification, protection, management and transfer of intellectual property and research outputs arising from research and innovation activities. TTOs may provide services such as invention disclosure management, intellectual property assessment, patenting, licensing, partnership development and support for intellectual property commercialization.

Trade secret: Confidential business or technical information that derives value from not being generally known and is protected through measures to maintain its secrecy.

Trademarks, branding or marketing outputs: Forms of intellectual property that protects distinctive names, logos, symbols, slogans or other identifiers used to distinguish goods or services from those of others.

Survey on Research Activities and Commercialization of Intellectual Property in Higher Education (SRACIPHE) 2025 Reporting Guide

This guide is designed to assist respondents in completing the Survey on Research Activities and Commercialization of Intellectual Property in Higher Education (SRACIPHE).

If you require additional information or clarification while completing the survey, please contact Statistics Canada:
Help Line: 1-877-949-9492
Email: statcan.sraciphe-earcpies.statcan@statcan.gc.ca

Confidentiality

Your answers are confidential.

Statistics Canada is prohibited by law from releasing any information it collects that could identify any person, business, or organization, unless consent has been provided by the respondent or disclosure is permitted under the Statistics Act.

Information collected through this survey will be used for statistical purposes only.

Survey Purpose

The purpose of this survey is to collect information about commercialization activities undertaken within the higher education sector.

Survey Coverage

This survey focuses on the higher education sector, including applied research and technology transfer organizations or units that carry out basic commercialization activities on behalf of postsecondary education institutions.

1) Higher education sector

The higher education sector, as defined in the Organisation for Economic Co-operation and Development (OECD) Frascati Manual, consists of institutions that provide formal postsecondary education programs such as universities, colleges, collège d'enseignement général et professionnel (CEGEPs), institutes of technology and polytechnics.

Research activities under the direct control of, or administered by, a postsecondary institution performed at another institution such as a hospital or research institute are considered part of the higher education sector. These activities are to be included in this survey and should be reported by the associated higher education institution.

For the purpose of this survey, research also includes experimental development, where applicable to the institution completing this form.

The terms research and research and development (R&D) used in this survey encompass basic, applied research and experimental development, as described by the Frascati Manual.

To reduce respondent burden, only postsecondary institutions performing more than $500,000 of R&D in the 2025 fiscal year are being asked to complete this survey.

2) Applied research and technology transfer organizations

Technology transfer offices (TTOs), Technology access centres (TACs) and centre collégial de transfert de technologie et de pratiques sociales novatrices (college centres for the transfer of technology and innovative social practices; CCTTs) are included in the survey population, including those that are external to or independent of a higher education institution. This ensures that relevant commercialization activities undertaken by some institutions are not excluded from the survey solely based on how these services are owned, organized or accessed by a postsecondary institution.

General information

General reporting principle

Information for this survey may be distributed across research offices, technology transfer offices, commercialization units, faculties, departments, affiliated organizations, and finance offices. Respondents are encouraged to coordinate across these units to provide the most complete response possible.

When deciding whether to include an activity, legal entity, agreement, intellectual property asset, or commercialization activity, include it if the activity is under the control of, administered by, owned by, or formally managed by the reporting institution during the reporting period. If the activity is managed and reported by another organization, do not report it unless specifically instructed elsewhere in the questionnaire.

Reporting

Postsecondary institutions should report for themselves wherever possible. Combined reporting is permitted where it is more practical for the institutions involved, provided that the activity of each legal entity is reported only once and is not double counted across multiple reports. If you provide information for more than one institution, please indicate the legal units included in this report in Questions 9 and 10.

The activities of TTOs, TACs and CCTTs that are administrative units of a postsecondary education institution should be reported by the postsecondary education institution. All TACs should fall into this category.

TTOs and CCTTs that are registered as a not-for-profit organization and are affiliated with one or more postsecondary education institutions, as subsidiaries or other legally distinct entities, will receive the survey. These institutions should report for themselves unless their activities are reported by their affiliated postsecondary institution as noted in Question 9.

Hospital(s) that conduct research and affiliated research institute(s) or research centre(s) whose research is not majority controlled and administered by a higher education institution are not considered part of the postsecondary sector and therefore will not receive a survey questionnaire. Postsecondary institutions affiliated with these organizations should however report the portion of research activities carried out at the affiliated hospital, research institute or research centre that are under their direct control or administration. This research is typically overseen by professors cross-appointed to the affiliated body and undertaken by graduate students of the higher education institution. Research activities that are not under the control or administered by the postsecondary institution should not be reported. This approach ensures that only the activities attributable to the higher education sector are included.

In cases where a postsecondary institution manages commercialization activities for another institution, such as fostering technology transfer or managing intellectual property (IP), pertinent questions will enable the respondent to indicate how these activities are organized and how they will be reported by this institution.

Reporting Period (Question 8)

All questions in this survey should be answered in reference to this institution's fiscal year that ended between April 1, 2025, and March 31, 2026, inclusive. The start date of the fiscal year does not matter; only the fiscal year end date is used to determine the reporting period. This period represents the Reference Year for the survey (2025).

For example:
Fiscal year April 1, 2024, to March 31, 2025, → Do not report (end date is before April 1, 2025).
Fiscal year July 1, 2024, to June 30, 2025, → Report (end date falls within the reporting period).
Fiscal year January 1, 2025, to December 31, 2025, → Report (end date falls within the reporting period).
Fiscal year April 1, 2025, to March 31, 2026, → Report (end date falls within the reporting period).

All information reported in this survey should correspond to the institution's fiscal period identified above. Financial information, including commercialization revenues and other reportable activities, should be reported for that period. Personnel counts, full-time equivalents (FTEs) and other institutional measures should also relate as closely as possible to the same reporting period. Where exact alignment is not possible, respondents should use the best available information from institutional records and apply reasonable estimates where necessary. Please note any significant departures from the reporting period or estimation methods in the survey comments section.

If the institution underwent structural changes during the reference period (e.g., amalgamation, transfer of functions, or dissolution), respondents should report data consistent with the institutional boundary applicable during the stated fiscal year and provide clarification in the comments section.

Use of Comment Boxes

Comment boxes are provided at the end of each module. Respondents are encouraged to:

  • Clarify or qualify responses,
  • Explain assumptions or estimation methods used,
  • Identify data limitations or reporting challenges, and
  • Provide suggestions to improve question wording, definitions, or response options.

Comments are reviewed by Statistics Canada and used to improve future versions of the survey.

Providing detailed and constructive feedback helps ensure that the survey remains clear, relevant, and aligned with institutional practices across the higher education sector.

General reporting instructions

Four data types

The questions in the questionnaire fall into four categories: date, categorical, numerical and currency (dollar amounts).

Date questions require a specific date as the response (e.g., DD/MM/YYYY).

Categorical questions require selecting one or more predefined response options (e.g., Yes/No, multiple choice categories).

Numerical questions require a number as the response, such as counts or percentages.

Report all dollar amounts in thousands of Canadian dollars ($CAD '000), rounded to the nearest whole thousand. For example, $55,417 should be reported as 55.

If exact figures are unavailable, provide your best estimate based on institutional records, sampling, extrapolation, administrative data, or professional judgment. Estimates are preferred to leaving responses blank whenever a reasonable estimate can be produced.

Reporting federal business numbers

Providing a federal business number is optional. If a business number is not available, you may leave this field blank and continue filling out the other fields in the question.

Reporting zero

Please respond to each question whenever possible. If the data are unavailable, leave the question blank—do not enter zero unless the correct value is zero.

Reporting incomplete or unavailable information

If precise figures are not available, please provide your best estimates.

The survey questionnaire includes non-mandatory checks in the form of pop-up windows that remind respondents of unanswered questions. By closing the pop-up window, respondents can skip the question and proceed to the next question. However, it is important to note that missing responses are considered non-responses and may result in imputation or follow-up.

Response option – not applicable

In this survey, the "Not Applicable" option means that the institution does not carry out the activities in question and that this option should be selected. Leaving responses blank will be interpreted as the information being "not available" or "unknown" and may lead to follow-up. In the event a respondent is unable to provide an answer (i.e., the information is unknown and cannot be obtained or estimated), respondents are advised to skip the question (i.e., submit a blank response) and indicate in the relevant comment box that the question could not be answered.

If a question includes a "Not applicable" or similar response option, select the option that best applies. For quantitative questions that do not include a "Not applicable" option, leave the response blank if there was no activity, activity was negligible, or a reasonable estimate cannot be provided. Please explain any omitted responses in the comment box at the end of the applicable module. This will assist Statistics Canada in interpreting your submission.

Responses, including additional information provided in the open comment boxes, will be analyzed to inform future iterations of the survey.

The Questionnaire

Module 1: Institutional Information (Question 7 - Question 11)

Question 7 – Institution Type and Structure

This question asks the respondent to confirm the type of the reporting institution. Question 7 is a filter question that all respondents are asked. It serves to minimize response burden for smaller institutions, or for those who perform more modest levels of R&D. Only institutions that are reflected in one of the three answer categories are required to complete the full questionnaire.

The response "None of the above" in Question 7 should be selected only if the institution type and structure is not reflected in the preceding answer categories.

Definition: Research and Development (R&D)

R&D includes systematic, creative activities undertaken to increase knowledge and to develop new or improved products, processes, services, or technologies.

Include:

  • Salaries and benefits of employees employed by the institution conducting R&D (including permanent, temporary, or casual employees)
  • Payments to self-employed individuals or contractors working on-site on the institution's internal R&D projects
  • Other current expenditures that directly support in-house R&D activities (e.g., materials, supplies, software, or utilities used for R&D projects)
  • Capital expenditures for R&D related infrastructure and for machinery and equipment used in R&D activities
  • Payments to external institutions for R&D where the tertiary educational institution administers or has direct control over the research being conducted.

Exclude:

  • Payments for R&D performed by external organizations, individuals, or companies that are not controlled or administered by this institution (extramural R&D)
  • Grants, fellowships, or contracts paid to individuals or organizations within or outside Canada
  • Routine activities (e.g., standard testing, maintenance, training, or market research) should only be included if they are an integral part of a defined R&D project.

Reporting instructions: Question 9 and 10

Many universities, colleges, polytechnics and CEGEPs have complex legal structures covering multiple legal entities that serve the core activities of the higher education institution. The following question is not an exercise to list all the legal structures that are part of an institution's organizational structure but to clarify what entities are being reported through this questionnaire to avoid double counting.

In general, this report should include all organizational units and legal entities that support the mission of the higher education institution. This includes the activities of all departments within the institution that are engaged, in whole or in part, in research, intellectual property support and management, and commercialization. For colleges and CEGEPs this includes the activities of centre collégial de transfert de technologie et de pratiques sociales novatrices (college centres for the transfer of technology and innovative social practices; CCTTs) and Technology Access Centres that are embedded within the institution.

Postsecondary institutions affiliated with research institutes or hospitals should report only the portion of research activities carried out at the affiliated hospital, research institute or research centre that is under the direct control of or administered by the postsecondary institution. Research activities that are not under the control or administered by the postsecondary institution should not be reported.

Technology transfer offices (TTOs) and CCTTs that operate as not-for-profit organizations affiliated with one or more postsecondary institutions, as subsidiaries may report independently.

Combined reporting

A single combined response may be submitted for the following institutional entities or arrangements, provided that the information is held or managed by the institution completing this survey, and the affiliated institution is not submitting a report in its own name.

Examples of affiliated legal entities that may be included in a combined report include:

  • affiliated or federated university colleges that do not administer research funding independently, and do not receive invention disclosures directly
  • small affiliated entities whose research activities (if any) and intellectual property are fully managed by the parent institution
  • established network of institutions, wholly owned and operated subsidiaries (e.g., innovation centres, affiliated research institutes)
  • TTOs and CCTTs that operate as separate not-for-profit organizations affiliated with one or more postsecondary education institutions, as subsidiaries, where noted in Question 10.

In Question 9 the reporting institution should indicate whether the report covers only the institution verified as the respondent in the beginning of the questionnaire (option 1), whether the report covers the verified respondent and other affiliated legal entities (option 2) or if the institution specified as the verified respondent is included in another institution's report (option 3). If the reporting institution is included in another institution's report, then the responding institution will be prompted to end the questionnaire.

An institution should select option 1 if the responding institution is:

  • an overarching institution, such as a university, college, CEGEP or polytechnic. Include any centre collégial de transfert de technologie et de pratiques sociales novatrices (college centre for the transfer of technology and innovative social practices; CCTT), technology access centre or technology transfer office (TTO) embedded within the institution in this report; or,
  • a CCTT or TTO that operates as a separate not-for-profit organization affiliated with one or more postsecondary institutions.

Question 10 is intended to identify all legally distinct entities whose activities are included in this report. Do not list all organizations that are affiliated with this institution. Only include affiliated higher education institutions (e.g., federated or affiliated colleges), centre collégial de transfert de technologie et de pratiques sociales novatrices (CCTTs), or technology transfer offices (TTOs) whose research, intellectual property, or commercialization activities are being reported through this questionnaire. This information is used to define the reporting boundary and prevent double counting across multiple reports. Providing a federal business number is optional. If a business number is not available or the reporting institution is not able to provide the data, you may leave this field blank and continue to add the entity.

Example

University A submits a combined report that includes:

  • the university;
  • an affiliated federated college; and
  • a separately incorporated TTO.

All three entities should be listed in Question 10.

Activities should only be reported once. If an activity is reported by an affiliated institution, TTO, or CCTT, do not report the same activity again in another questionnaire. The affiliated entities should select option 3 of Question 9 "The response for this institution is included in the report of another institution".

Do not list:

  • affiliated foundations,
  • alumni associations,
  • student organizations,
  • pension entities, or
  • other affiliated organizations whose activities are not included in this report.

Module 3: Intellectual property (Question 16 to Question 35)

This module collects information on IP management and support activities undertaken by your institution as well as IP commercialization activities.

IP management activities include identifying, protecting and managing intellectual property, such as invention disclosures, patent applications, IP portfolio management and licensing activities.

IP support activities include advisory, administrative or facilitation services that help researchers, inventors or institutions identify, protect, manage or use intellectual property.

Examples of IP management and support activities include:

  • administering invention disclosure processes;
  • identifying potential applications or users of research results;
  • providing IP assessments, advice or education;
  • preparing documentation required to protect IP;
  • supporting patent, copyright or trademark applications;
  • managing institutional IP portfolios;
  • providing licensing guidance or administrative support;
  • facilitating collaborations related to IP development or use;
  • providing commercialization support services or knowledge transfer assistance;
  • providing funding for IP-related activities; and
  • applying for IP on behalf of a third party or supporting an application by preparing the required documentation.

Institutions should report these activities whether they are delivered by internal staff or through external service providers or partners.

IP commercialization activities involve transferring, licensing, assigning, commercializing or otherwise applying intellectual property to generate economic or societal value outside the institution. These activities typically involve formal agreements, transactions or relationships with external organizations.

Examples of IP commercialization activities include:

  • licensing or assigning IP rights;
  • executing option agreements;
  • creating or supporting spin-off companies based on institutional IP (covered in module 5);
  • negotiating commercialization agreements;
  • generating licensing, royalty or other commercialization revenue;
  • transferring technology or know-how to industry or other organizations; and
  • supporting the market adoption of research-based products, services or technologies.

The key distinction is that IP management or support activities focus on identifying, protecting, administering and enabling the use of IP, whereas IP commercialization activities focus on transferring or exploiting IP to create economic or societal value through licensing, commercialization agreements, start-up creation or other forms of technology transfer.

IP-related activities may be carried out by one or more organizational units, such as an office of applied research, the vice-president (research) office, an industry liaison office or a technology transfer office.

Module 4: Support for advancing projects toward commercialization (Question 36 to Question 40)

The questions in this section use the Technology Readiness Level (TRL) framework to describe the maturity of a product, process or prototype. The TRL scale is referenced in the response categories for Question 36 to help respondents identify activities conducted to help advance projects towards commercialization. Respondents who did not select the following option in Question 36: "Final development, qualification or market-ready preparation of products, processes or prototypes (associated with TRL 7 and above)" are not required to answer Questions 37 to 40. These follow-up questions apply only to respondents reporting activities at TRL 7 and above.

Examples of activities typically associated with TRL 7 and above

  • field testing of a prototype in an operational environment
  • pilot deployment with an external client or partner
  • certification, qualification, or regulatory testing
  • final design refinement before market launch
  • demonstration of a technology under real-world conditions.

If you provide an estimate for the number of new or improved products, processes or prototypes, please describe your estimation method and any key assumptions or calculations in the comment box for Question 39 or Question 40.

If your institution does not track activities that advanced research outcomes toward commercialization (Question 37), you may skip Question 38, which asks for the number of new or improved products, processes or prototypes.

Definition: Technology readiness levels (TRL)

A TRL scale is used to assess the maturity of a technology, product, process or prototype as it progresses from research and development to deployment and operational use.

The following table provides a short summary of each TRL level.

TRLShort DefinitionDescriptionExamples of Activities
1Basic principles observed and reported.Lowest level of technology readiness. Scientific research begins to be translated into applied research and development (R&D).Activities might include theoretical studies of a technology's basic properties.
2Technology concept and/or application formulated.Invention begins. Once basic principles are observed, practical applications can be invented. Applications are speculative, and there may be no proof or detailed analysis to support the assumptions.Activities are limited to analytical studies.
3Analytical and experimental critical function and/or characteristic proof of concept.Active R&D is initiated. This includes analytical studies and laboratory studies to physically validate the analytical predictions of separate elements of the technology.Activities include components that are not yet integrated or representative.
4Component(s)/subsystem(s) and/or process validation in a laboratory environment.Basic components are integrated to establish that they will work together.Activities include integration of "ad hoc" hardware or software in the laboratory.
5Semi-integrated component(s)/subsystem(s) and/or process validation in a simulated environment.The basic components are integrated for testing in a simulated environment.Activities include laboratory integration of components.
6System and/or process prototype demonstration in a simulated environment.A model or prototype that represents a near desired configuration.Activities include testing a model or prototype in a simulated or laboratory environment.
7Prototype system ready (form, fit, and function) for demonstration in an appropriate operational environment.Prototype is ready for demonstration in an operational environment and is at planned operational level.Activities include prototype field testing in a real-world operational setting.
8Actual solution completed and qualified through tests and demonstrations.Solution has been proven to work in its final form and under expected conditions.Activities include developmental testing and evaluation of whether it will meet operational requirements.
9Actual solution proven through successful deployment in an operational setting.Actual application of the technology in its final form and under real-life conditions, such as those encountered in operational tests and evaluations.Activities include using the innovation under operational conditions.

Module 5: Business support (Question 41 to Question 47)

Reporting instruction: Question 43

Providing a federal business number is optional. If a business number is not available or the reporting institution is not able to provide the data, you may leave this field blank and continue to add the spin-off.

Definition: Spin-off

For the purpose of this survey, a spin-off refers to a company created to commercialize intellectual property (IP) or technology developed at this institution.

Institutions should report only spin-offs where there is a formal and verifiable link to IP developed at the institution.
Please consider companies that registered as a legal entity within the 2025 fiscal year.

Include only companies that meet at least one of the following conditions:

  • The company has licensed IP (e.g., patents, software, or know-how) from this institution
  • The company is based on an invention disclosure submitted to this institution
  • The institution has equity participation in the company based on an IP contribution.

Exclude:

  • Start-ups founded by students, graduates, or staff without a formal IP relationship to the institution
  • Companies based on general knowledge, skills, or experience acquired at the institution, without documented IP linkage
  • Start-ups supported by incubators, accelerators, or mentorship programs unless they meet the IP-related conditions above.

Only include spin-offs that the institution can identify and substantiate based on formal records or agreements.

Definition: Start-ups

For the purpose of this survey, a start-up refers to a new company created to address a market need, typically built on a novel idea or technology and supported by a business plan and growth strategy.

Institutions should report only start-ups where there is no formal or verifiable relationship to IP developed at this institution. This applies regardless of whether the start-ups received support from this institution or not.

Please consider companies that registered as a legal entity within the 2025 fiscal year.

Include only companies that meet at least one of the following conditions:

  • founded by students, graduates, or staff without a formal IP relationship to the institution
  • Companies formed based on general knowledge, skills, or experience acquired at the institution, without documented IP linkage
  • Companies supported by incubators, accelerators, or mentorship programs unless they meet the IP-related conditions above.

Exclude:

  • Spin-offs that have licensed IP (e.g., patents, software, or know-how) from this institution
  • Companies that are based on an invention disclosure submitted to this institution
  • Companies where the institution has equity participation in the company based on an IP contribution.