Statistics Canada's Fees Report, Fiscal year 2025–26

On this page

Minister's message

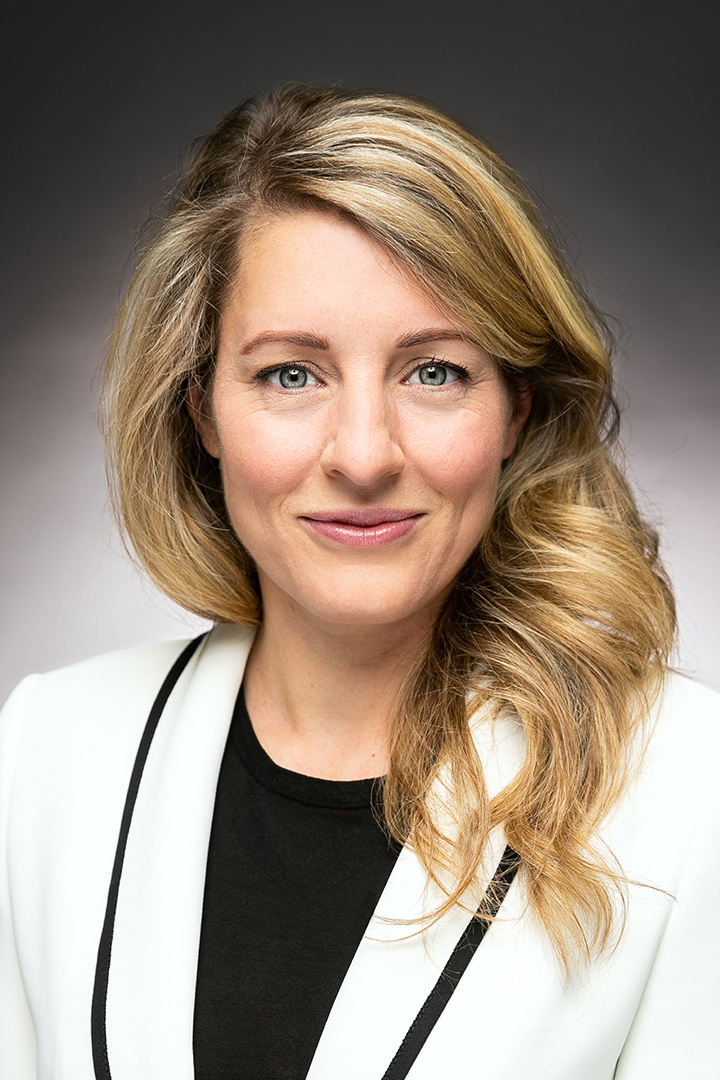
Photo of The Honourable Mélanie Joly

The Honourable Mélanie Joly, Minister of Industry and Minister responsible for Canada Economic Development for Quebec Regions.

I am pleased to present Statistics Canada's report on fees for 2025–26.

The Service Fees Act provides a modern legislative framework that enables cost-effective delivery of services and, through better reporting to Parliament, improves transparency and oversight.

The report provides a comprehensive breakdown of individual fees under the department's authority, the charged amount, the service standard, performance result and remissions, if applicable. This information provides further context on each fee, promoting transparent and accountable fee management.

Statistics Canada reports to the Minister of Industry and Minister responsible for Canada Economic Development for Quebec Regions. Its mandate is to produce data that help Canadians better understand their country - its population, resources, economy, environment, society and culture. As Canada's central statistical office, Statistics Canada is legislated to serve this function for Canada and each of the provinces and territories. The agency must also conduct the Census of Population and the Census of Agriculture every five years, providing a detailed picture of Canadian society. Statistics Canada operates under the authority of the Statistics Act and is committed to protecting the confidentiality and privacy of the information it is entrusted with.

As part of the Innovation, Science and Economic Development Canada (ISED) portfolio, Statistics Canada has the authority to collect fees set by contract from external clients for cost-recovered statistical services.

The Service Fees Act enhances the transparency and accountability of fees charged by ISED and its portfolios. I support this reporting regime and I am committed to ensuring that Canadians and Canadian businesses receive quality services that reflect the principles of this Act.

The Honourable Mélanie Joly, P.C., M.P.
Minister of Industry and Minister responsible for Canada Economic Development for Quebec Regions

About this report

This report, which is tabled under section 20 of the Service Fees Act, the Low‑Materiality Fees Regulations, and subsection 4.2.9 of the Treasury Board Directive on Charging and Special Financial Authorities, contains information about the fees Statistics Canada had the authority to charge in fiscal year 2025–26.

The report covers fees that are subject to the Service Fees Act.

For reporting purposes, fees are categorized by fee-setting mechanism. There are three mechanisms:

  1. Act, regulation or fees notice
    The authority to set these fees is delegated to a department, minister or Governor in Council pursuant to an act of Parliament.
  2. Contract
    Ministers have the inherent authority to enter into contracts, which are usually negotiated between the minister and an individual or organization, and which cover fees and other terms and conditions. In some cases, that authority may also be provided by an act of Parliament.
  3. Market rate or auction
    The authority to set these fees comes from an act of Parliament or a regulation, and the minister, department or Governor in Council has no control in determining the fee amount.

No fees under Statistics Canada's authority are set by act, regulation or fees notice. This report therefore only covers fees set by contract. It provides total revenue and costs only.

Fees charged by Statistics Canada under the Access to Information Act are not subject to the Service Fees Act and are not included in this report. Information on Statistics Canada's access to information fees can be found in our annual report to Parliament on the administration of the Access to Information Act: Annual Reports on Access to Information and Privacy.

Remissions

In 2025–26, Statistics Canada was not subject to the requirements in section 7 of the Service Fees Act and had no authority to remit, so this report does not include remission amounts.

Overall totals, by fee-setting mechanism

The following table presents the total revenue, cost and remissions for all fees Statistics Canada had the authority to charge in 2025–26, by fee-setting mechanism.

Overall totals for 2025–26, by fee-setting mechanism

Fee-setting mechanism

Revenue ($)

Cost ($)

Remissions ($)

Fees set by contract

$20,669,677

$20,669,677

Remissions do not apply to fees set by contract.

Retail Commodity Survey: CVs for Total Sales (June 2026)

Retail Commodity Survey: CVs for Total Sales (June 2026)
Table summary
This table displays the results of Retail Commodity Survey: CVs for Total Sales (June 2026). The information is grouped by NAPCS-CANADA (appearing as row headers), and Month (appearing as column headers).
NAPCS-CANADAMonth
202605202606
Total commodities, retail trade commissions and miscellaneous services0.580.63
Retail Services (except commissions) [561]0.570.64
Food and beverages at retail [56111]0.391.66
Cannabis products, at retail [56113]0.000.00
Clothing at retail [56121]0.720.64
Jewellery and watches, luggage and briefcases, at retail [56123]3.513.63
Footwear at retail [56124]0.991.11
Home furniture, furnishings, housewares, appliances and electronics, at retail [56131]0.890.83
Sporting and leisure products (except publications, audio and video recordings, and game software), at retail [56141]2.552.55
Publications at retail [56142]7.278.27
Audio and video recordings, and game software, at retail [56143]4.174.06
Motor vehicles at retail [56151]1.971.58
Recreational vehicles at retail [56152]4.873.85
Motor vehicle parts, accessories and supplies, at retail [56153]1.381.44
Automotive and household fuels, at retail [56161]1.421.29
Home health products at retail [56171]2.402.70
Infant care, personal and beauty products, at retail [56172]4.443.60
Hardware, tools, renovation and lawn and garden products, at retail [56181]1.631.98
Miscellaneous products at retail [56191]3.443.49
Retail trade commissions [562]1.661.53

Survey of Marine Vessel Operators – 2025

Reporting period information

1. Please report the start and end dates of this business's most recent 12-month fiscal period.

Note: For this survey, the end date should fall between April 1, 2025, and March 31, 2026.

The reported fiscal period end date will be used as the reference point for the remainder of the survey.

  • Start date
    Example: YYYY-MM-DD
  • End date
    Example: YYYY-MM-DD

Business information

2. What is the form of ownership of this business?

  • Sole proprietorship
  • Incorporated company
    Include non-profit organizations, partnerships and limited partnerships in incorporated companies.
  • Crown corporation
    Include port authorities and pilotage authorities.
  • Government
    Include federal, provincial, municipal and First Nations government-operated ferries.
  • Other
    e.g., businesses operating as subsidiaries
    • Specify other form of ownership:

Flow condition: If "Crown corporation" or "Government" are selected in Q2, survey will conclude. Otherwise, go to Q3.

3. How many vessels did this business operate in total during its last fiscal year ending in 2025/2026?

Report the total number of vessels operated that were owned, leased or chartered and not the number of times a vessel was operated. 

Include barges, cargo ships, tankers, ferries, research vessels, tugboats, escort vessels, icebreakers, offshore vessels, dredgers, buoy tenders, derricks or cranes, salvage vessels, diving vessels, dump vessels, floating dry docks, survey ships, or patrol boats that were operated by this business regardless of gross tonnage (GT).

Exclude vessels that were owned and not operated, as well as private pleasure craft and fishing vessels. 

Enter "0" if this business did not operate any vessels.

  • Number of vessels operated by this business:

Flow condition: If Q3 is greater than 0 or blank, go to Q4, otherwise go to Q5.

4. How many of the vessels operated were 15 gross tonnage and above?

Report the total number of vessels operated that were owned, leased or chartered and were 15 GT and above.

Include barges, cargo ships, tankers, ferries, research vessels, tugboats, escort vessels, icebreakers, offshore vessels, dredgers, buoy tenders, derricks or cranes, salvage vessels, diving vessels, dump vessels, floating dry docks, survey ships, or patrol boats operated by this business that were 15 GT and above.

Exclude vessels that were owned and not operated, as well as private pleasure craft and fishing vessels.

Enter "0" if this business did not operate any vessels 15 GT and above.

  • Number of vessels operated 15 GT and above

5. How many vessels did this business own in total during its last fiscal year ending in 2025/2026?

Include barges, cargo ships, tankers, ferries, research vessels, tugboats, escort vessels, icebreakers, offshore vessels, dredgers, buoy tenders, derricks or cranes, salvage vessels, diving vessels, dump vessels, floating dry docks, survey ships, or patrol boats owned by this business.

Exclude private pleasure craft and fishing vessels. 

Enter "0" if this business did not own any vessels.

  • Number of vessels owned by this business:

Flow condition: If Q5 is greater than 0 or blank, go to Q6. Otherwise go to Q7.

6. How many of the vessels owned were 15 gross tonnage and above?

Include barges, cargo ships, tankers, ferries, research vessels, tugboats, escort vessels, icebreakers, offshore vessels, dredgers, buoy tenders, derricks or cranes, salvage vessels, diving vessels, dump vessels, floating dry docks, survey ships, or patrol boats owned by this business that were 15 GT and above.

Exclude private pleasure craft and fishing vessels.

Enter "0" if this business did not own any vessels 15 GT and above.

  • Number of vessels owned 15 GT and above:

Flow condition: If Q3 = 0 or Q4 =0, survey will conclude. Otherwise go to Q7.

Revenue from vessel operations

7.  What was the total revenue from vessel operations for the fiscal year ending in 2025/2026?

Include revenue from the transportation of commodities, cargo, freight, passengers or vehicles; revenue from the towing of commodities or log booms; chartering or leasing; cost compensation from parent companies; revenue from on-vessel sales and concessions; and water transport subsidies.

Please report in Canadian dollars.

If the exact value is not available, please provide your best estimate.

  • Total revenue from vessel operations in CAN$:

Flow condition: If Q7 is equal to or greater than $6,000,000 or blank, go to Q8. Otherwise go to Q10. 

Business information

8. For the fiscal year ending in 2025/2026, of the vessels that were 15 gross tonnage and above, which of the following types of vessels were operated? 

If this business operated vessels that transport both passenger vehicles and commercial vehicles together, report them as passenger and all vehicle type ferries.

Exclude vessels that were owned and not operated, as well as private pleasure craft and fishing vessels.

Select all that apply.

  • Barges
    Include deck, hopper or tank barges.
  • Cargo ships
    Include solid cargo vessels; container ships; dry bulk, liquid bulk and breakbulk carriers; and roll-on-roll-off cargo vessels.
  • Tankers
    Include oil, chemical, liquefied gas and product (gas or diesel) tankers.
  • Passenger vessels
    Include day or overnight cruises and sightseeing vessels.
    Exclude ferries.
  • Passenger and passenger vehicle ferries
    Exclude commercial vehicles.
  • Passenger and all vehicle type ferries
    Include commercial and passenger vehicle roll-on-roll-off ferries.
  • Passenger-only ferries
    Include water taxis.
    e.g., cyclists, pedestrians
  • Research vessels
    Include seismic and fishing vessels.
  • Tugboats or escort vessels
    Include vessels that assist in moving larger ships and barges at ports or in narrow waterways.
  • Icebreakers
    Include those used to escort research vessels in icy waters.
  • Offshore vessels
    Include supply vessels, workboats, cable-laying and floating platforms, and vessels used for production storage and offloading.
  • Dredgers
    Include vessels used for excavation and maintenance of waterways, construction support or resource extraction.
  • Buoy tenders
  • Derricks or cranes
  • Salvage vessels
  • Diving vessels
  • Dump vessels
  • Floating dry docks
  • Survey ships
  • Patrol boats
  • Other types of vessels operated
    • Specify the other types of vessels:

Display condition: Only vessel types that were selected in Q8 are displayed in Q9. If no vessel types were selected in Q8, display all vessel types.

9. For the fiscal year ending in 2025/2026, how many of each of the following types of vessels that were 15 gross tonnage and above did this business operate?

If this business operated vessels that transport both passenger vehicles and commercial vehicles together, only report them once, as passenger and all vehicle type ferries.

Exclude vessels that were owned and not operated, as well as private pleasure craft and fishing vessels. 

Number of vessels 15 GT and above

  • Barges:
    Include deck, hopper or tank barges.
  • Cargo ships:
    Include solid cargo vessels; container ships; dry bulk, liquid bulk and breakbulk carriers; and roll-on-roll-off cargo vessels.
  • Tankers:
    Include oil, chemical, liquefied gas and product (gas or diesel) tankers.
  • Passenger vessels:
    Include day or overnight cruises and sightseeing vessels.
    Exclude ferries.
  • Passenger and passenger vehicle ferries:
    Exclude commercial vehicles.
  • Passenger and all vehicle type ferries:
    Include commercial and passenger vehicle roll-on-roll-off ferries.
  • Passenger-only ferries:
    Include water taxis.
    e.g., cyclists, pedestrians
  • Research vessels:
    Include seismic and fishing vessels.
  • Tugboats or escort vessels:
    Include vessels that assist in moving larger ships and barges at ports or in narrow waterways.
  • Icebreakers:
    Include those used to escort research vessels in icy waters.
  • Offshore vessels:
    Include supply vessels, workboats, cable-laying and floating platforms, and vessels used for production storage and offloading.
  • Dredgers:
    Include vessels used for excavation and maintenance of waterways, construction support or resource extraction.
  • Buoy tenders:
  • Derricks or cranes:
  • Salvage vessels :
  • Diving vessels:
  • Dump vessels:
  • Floating dry docks:
  • Survey ships:  
  • Patrol boats:
  • Other types of vessels operated:
  • Total:

10. For the fiscal year ending in 2025/2026, has this business chartered in or leased any vessels for its operations?

Chartered in or leased: Process by which an individual or a business entity, called the lessee, rents a vessel from a shipowner (the lessor) for a specific voyage or period of time (also known as chartering in). This can be done by bareboat charter.

Exclude private pleasure craft and fishing vessels.

  • Yes
    Please indicate the number of vessels that were chartered in or leased by this business.
    Number of vessels chartered in or leased:
  • No
  • Don't know

Flow condition: If Q7 is equal to or greater than $6,000,000 or blank, go to Q11, otherwise go to Q13. 

11. For the fiscal year ending in 2025/2026, was this business directly or indirectly owned or controlled by any other businesses?

Control: Having the authority or enough voting shares to make corporate decisions for the business.

  • Yes
    • Where were those businesses located?
      Select all that apply.
      • Inside Canada
      • Outside Canada
        • What region is the majority owner or controller of this business located in? 
          Majority owner or controller: The business that has the greatest share of ownership or control of this business.
          • United States
          • Central America, the Caribbean, Mexico and South America
          • United Kingdom
          • Europe other than United Kingdom
            Include Eastern and Western Europe.
          • Australia
          • New Zealand
          • Asia and Oceania
            Exclude Australia and New Zealand.
          • Middle East and Africa
  • No
  • Don't know

12. For the fiscal year ending in 2025/2026, did this business own or control any other businesses engaged in foreign marine activities?

Control: Having the authority or enough voting shares to make corporate decisions for the business.

  • Yes
    • Where were those businesses located?
      Select all that apply.
      • Inside Canada
      • Outside Canada
  • No 
  • Don't know

Type of operation

13. For the fiscal year ending in 2025/2026, was this business engaged in the transportation of commodities, cargo or freight, passengers or vehicles?

Commodities: Basic raw materials or bulk goods, usually transported in large quantities. These include a wide range of products, such as crude oil, natural gas, coal, iron ore, grains, chemicals and other bulk goods. These goods are usually transported in large quantities using specialized vessels.

Cargo or freight: Goods or freight, used as a general term, often regarding commercial inventory, can include any type of product or good, such as packaged goods, manufactured products, machinery and containers.

Passenger: A person carried on a vessel by the owner or operator in exchange for payment. 

Select all that apply.

  • Commodities
  • Cargo or freight
  • Passengers or vehicles
    Include ferries, day or overnight cruises and sightseeing vessels.
    OR
  • This business was not engaged in the transportation of commodities, cargo or freight, passengers or vehicles.
    e.g., drayage, research, construction, equipment
    • Please indicate the type of activities other than the transportation of commodities, cargo or freight, passengers or vehicles that this business was engaged in.
      Select all that apply.
      • Construction or industrial support
        Include vessels used as work platforms for construction, installation or industrial activities.
        Exclude the transport of goods between locations.
      • Offshore resource activities
        Include support services for offshore energy or resource development.
      • Dredging or seabed work
        Include dredging, excavation or seabed preparation.
      • Bunkering or lightering
        Include ship-to-ship fuel or cargo transfer.
        Exclude the transportation of fuel or cargo between ports.
      • Aquaculture or fisheries support
        Include servicing aquaculture or fishing operations. 
        Exclude the transport of fish or seafood to market.
      • Accommodation
        Include stationary or semi-stationary accommodation or support vessels (e.g., floatels).
        Exclude the transport of passengers or workers.
      • Towing
        Include towing or escorting vessels.
      • Icebreaking
        Include icebreaking or ice management services.
        Exclude ice navigation advice only.
      • Research activities
        Include scientific, technical or environmental research conducted using vessels or marine facilities (e.g., data collection, surveys, monitoring).
        Exclude commercial transportation or industrial operations.
      • Other activities
        • Specify other activities:

Sources of power

14. For the fiscal year ending in 2025/2026, which of the following sources of power were purchased for propulsion in vessel operations? 

Only report sources of power in vessel operations.

Include sources of power and propulsion for main engines.

Select all that apply.

  • Fuel oil
    Include bunker C oil, diesel oil and gas oil.
    Please indicate the type of fuel oil that was purchased.
    Select all that apply.
    • Heavy fuel oil
      Please indicate the type of heavy fuel oil that was purchased.
      Select all that apply.
      • Bunker C oil
      • IFO380
      • VLSFO
    • Diesel oil
    • Gas oil
      OR
    • Don't know
  • Gasoline
  • Liquefied natural gas (LNG)
  • Biodiesel or biofuel
  • Hydrogen
  • Ammonia
  • Methanol
  • Electric
    Include batteries.
  • Green fuel sources
    Please indicate the type of green fuel that was purchased.
    Select all that apply.
    • E-LNG
    • Bio-LNG
    • Green ammonia
    • Green methanol
    • Green hydrogen
  • Other sources of power
    • Specify the other sources of power for propulsion
      OR
  • Don't know

Flow condition: If Q14= "Don't know", go to Q16. If Q7 is equal to or greater than $6,000,000 or blank, go to Q15. Otherwise, go to Q16.

Display condition: Only sources of power that were selected in Q14 are displayed in Q15. If no sources of power were selected in Q14, display "Fuel oil", "Gasoline", "Liquefied natural gas (LNG)", "Biodiesel or biofuel", "Hydrogen", "Ammonia", "Methanol", "Electric", "Green fuel sources", and "Other sources of power".

15. For the fiscal year ending in 2025/2026, what percentage of this business's total vessel propulsion fuel spending was attributable to each propulsion fuel or power source?

If exact values are not available, please provide your best estimate.

Percentages should be rounded to whole numbers, and the total should equal to 100%.

Percentage of propulsion fuel purchased

  • Fuel oil:
  • Heavy fuel oil:
  • Bunker C oil:
  • IFO380:
  • VLSFO:
  • Diesel oil:
  • Gas oil:
  • Gasoline:
  • Liquefied natural gas (LNG):
  • Biodiesel or biofuel:
  • Hydrogen:
  • Ammonia:
  • Methanol:
  • Electric:
  • Green fuel source:
  • E-LNG:
  • Bio-LNG :
  • Green ammonia:
  • Green methanol:
  • Green hydrogen:
  • Other source of power:
  • Total:

 16. Over the next five years, does this business plan to modify the source of power or fuel type used in its vessels? 

e.g., switching from diesel to biodiesel, installing shore power connection equipment on the vessel, changing technology to take advantage of environmentally friendly fuels or to improve efficiency

  • Yes
    What source of power or fuel type does this business plan to use?
    Source of power or fuel type:
  • No
  • Don't know

Flow condition: If Q7 is equal to or greater than $6,000,000 or blank, go to Q17. Otherwise, go to Q19. 

Shore power stations

17. For the fiscal year ending in 2025/2026, did this business's vessels use shore power stations in Canada? 

Shore power station: The source of the power used by the vessel while docked at port, allowing access to landside electrical power. Shore power alleviates the unnecessary use of fuel, which would otherwise be used to power vessels while in port. 

Exclude vessels that use the power of terminals for propulsion.

  • Yes
    • Please indicate the quantity of electricity purchased and expenditures at shore power stations in Canada.
      • Quantity purchased in kWh:
      • Electricity expenditures in CAN$:
        If the exact value is not available, please provide your best estimate.
  • No
  • Don't know

Flow condition: If Q7 is equal to or greater than $6,000,000 or blank, go to Q18. Otherwise, go to Q19. 

Revenue from vessel operations

18. Based on this business's reported revenue from vessel operations, please provide a breakdown of this revenue for the fiscal year ending in 2025/2026. 

Include revenue from the transportation of commodities, cargo, freight, passengers or vehicles; revenue from the towing of commodities or log booms; chartering or leasing; cost compensation from parent companies; revenue from on-vessel sales and concessions; and water transport subsidies.

Please report in Canadian dollars.

If exact values are not available, please provide your best estimate.

If no revenue was earned for an activity, please report "0" where applicable.

Revenue CAN$

Vessel operating revenue

  • Transport and towing of commodities, cargo or freight:
  • Transport of passengers:
    Include sightseeing vessels and ferries.
    Exclude revenue from concessions and food and beverage sales when not included in the cost of the trip fare.
  • Charter or lease of owned Canadian-registered vessels to other operators:
    Include chartered or leased non-duty paid Canadian-registered vessels and chartered or leased foreign-registered vessels under a coasting trade licence.
  • Water transport subsidies:

Other water transportation revenue

  • Towing, docking or turning of self-propelled vessels:
  • Other water transportation revenue:

Revenues from other marine activities of a commercial nature, non-transportation

  • Construction or industrial support:
  • Offshore resource exploration and development activities:
  • Dredging and seabed work:
  • Bunkering and lightering:
  • Aquaculture and fisheries support:
  • Accommodation and support vessels:
  • Icebreaking:
  • Other commercial marine activities that do not have a transportation component:

Revenue from activities incidental to water transportation

  • Terminal and cargo handling services:
    Include terminal operations, stevedoring, yarding and storage related to cargo movement.
  • Logistics and agency services:
    Include freight forwarding, customs brokerage, and vessel and cargo agency fees.
  • Vessel and cargo delay charges:
    Include demurrage charges and detention charges.
  • Marine support and emergency services:
    Include marine salvaging, emergency response and specialized marine support services.

Other sources of revenue

  • Other sources of revenue incidental to water transportation activities:
    Include vessel dispatching and voyage planning services, transportation equipment rental (excluding vessels), and standby and availability fees.
  • Other sources of revenue from transportation activities:
    Include railway transportation, trucking, etc.
  • Other sources of revenue not related to transportation:
    Include concrete aggregates, production of construction materials, etc.
  • Other sources of revenue related to on-vessel sales and concessions:
    Include rooms, food and beverages, souvenirs or other non-food items.

Total:

Flow condition: If Q7 is less than $6,000,000, go to Q19. Otherwise, go to Q20. 

Total revenue 

19. Based on this business's reported revenue from vessel operations, please provide a breakdown of this revenue for the fiscal year ending in 2025/2026.

Include revenue from the transportation of commodities, cargo, freight, passengers or vehicles; revenue from the towing of commodities or log booms; chartering or leasing; cost compensation from parent companies; revenue from on-vessel sales and concessions; and water transport subsidies.

Please report in Canadian dollars.

If exact values are not available, please provide your best estimate.

If no revenue was earned for an activity, please report "0" where applicable.

  • Vessel operating revenue:
    Include the transport and towing of commodities, cargo or freight, the transport of passengers, and the charter or lease of owned Canadian-registered vessels to other operators.
  • Other water transportation revenue:
    Include the towing, docking or turning of self-propelled vessels, and other water transportation revenue.
  • Revenues from other marine activities of a commercial nature:
    Exclude transportation. 
    Include construction or industrial support, offshore resource exploration and development activities, dredging and seabed work, bunkering and lightering, aquaculture and fisheries support, accommodation and support vessels, icebreaking, and other commercial marine activities that do not have a transportation component.
  • Revenue from activities incidental to water transportation:
    Include terminal and cargo handling services, logistics and agency services, vessel and cargo delay charges, and marine support and emergency services.
  • Other sources of revenue:
    Include other sources of revenue incidental to water transportation activities, other sources of revenue from transportation activities, other sources of revenue not related to transportation, and on-vessel sales and concessions.
  • Total revenue:

Vessel operating expenses

20. What were this business's total vessel operating expenses for the fiscal year ending in 2025/2026?

Include vessel operating costs, vessel maintenance and repairs, insurance and other fees, terminal and office expenses, non-transportation expenses, other transportation expenses and depreciation. 

Please report in Canadian dollars. 

If exact values are not available, please provide your best estimate.

Enter "0" if this business did not incur any expenses.

  • Total vessel operating expenses in CAN$:

Flow condition: If Q7 is equal to or greater than $6,000,000 or blank, go to Q21. Otherwise, go to Q22. 

21. Based on this business's reported expenses from vessel operations, please provide the breakdown of these expenses for the fiscal year ending in 2025/2026.

Please report in Canadian dollars.

If exact values are not available, please provide your best estimate.

If no expenses were incurred, please report "0" where applicable.

Vessel operating costs

  • Vessel crew remuneration:
    Include gross payroll and mandatory and non-mandatory contributions. 
    Exclude contractors.
  • Sources of power for propulsion:
    Include non-refundable taxes.
    e.g., fuel oil, gasoline, liquefied natural gas (LNG)
  • Vessel maintenance and repairs:
    Include allocation for the ship's survey, annual overhaul, lay-up or fit out; lubricating oil (inclusive of non-refundable taxes); and remuneration for maintenance crew who are not on the vessel.
  • Bareboat charter or lease hired in Canada:
  • Bareboat charter or lease hired abroad:
  • Food and provisions:
  • Communication expenses:
    e.g., radar, radio, satellite, computer, cellular phone

Insurance and other fees

  • Insurance:
    Include hull and machinery insurance, third-party liability insurance, and cargo insurance. 
    e.g., package freight policy premiums
  • Berthage and port dues:
    e.g., wharfage, anchorage, buoyage and dockage
  • Pilotage:
  • Canal and seaway tolls:
  • Coast guard fees:
  • Waste disposal expenses:
  • Purchased towage or escort services:

Terminal and office expenses

  • Office and terminal employee remuneration:
    Include gross payroll and mandatory and non-mandatory contributions.
  • Demurrage:
    Include fees charged when a vessel, container or cargo remains at a port, terminal or berth beyond the allowed free time for loading or unloading, because of delays while under the control of the terminal or port.
    e.g., a vessel is billed for demurrage when the cargo cannot be unloaded within the agreed-upon time because of terminal congestion

Non-transportation expenses

  • Corporate taxes paid at the federal, provincial and municipal levels:

Other expenses

  • Other transportation expenses:
    Include railway transportation, trucking, etc.
  • Other purchased transport:
    e.g., transportation services purchased from a third party, transportation of crew or other cargos in support of business operations
  • Depreciation:
    Include vessels and floating equipment.

Total expenditures:

Flow condition: If Q7 is less than $6,000,000, go to Q22. Otherwise, go to Q23. 

22. Based on this business's reported expenses from vessel operations, please provide the breakdown of these expenses for the fiscal year ending in 2025/2026.

Please report in Canadian dollars.

If exact values are not available, please provide your best estimate.

If no expenses were incurred, please report "0" where applicable.

  • Vessel operating costs:
    Include vessel crew remuneration, sources of power for propulsion, lubricating oil, vessel maintenance and repairs, boat charter or lease hired in Canada or abroad, food and provisions, and communication expenses. 
    e.g., radar, radio, satellite, computer, cellular phone
  • Insurance and other fees:
    Include insurance, berthage and port dues, pilotage, canal and seaway tolls, coast guard fees, inspection fees, waste disposal expenses, and purchased towage or escort services.
  • Terminal and office expenses:
    Include office and terminal employee remuneration and demurrage.
    e.g., a vessel is billed for demurrage when the cargo cannot be unloaded within the agreed-upon time because of terminal congestion
  • Non-transportation expenses:
    Include corporate taxes paid at the federal, provincial and municipal levels.
  • Other expenses:
    Include other transportation expenses, other purchased transport and depreciation.
    e.g., transportation services purchased from a third party, transportation of crew or other cargos in support of business operations
  • Total expenditures:

Employment

23. As of this business's peak season for the fiscal year ending in 2025/2026, how many people worked for this business's vessel operations, by type of occupation and by number of Canadian citizens or permanent residents and non-permanent residents?

Include all employees who received a T4 working for this business's vessel operations, whether full-time, part-time, seasonal or temporary. 
Exclude contract workers.

Canadian citizen: A person described as a citizen under the Citizenship Act. This means a person who is Canadian by birth (either born in Canada or born outside Canada to a Canadian citizen who was either born in Canada or granted citizenship) or has applied for a grant of citizenship and has received Canadian citizenship. 

Permanent resident: A person who has legally immigrated to Canada but is not yet a Canadian citizen.

Non-permanent resident: A person from another country with a usual place of residence in Canada and who has a work or study permit or who has claimed refugee status (asylum claimant), including individuals employed under the Temporary Foreign Worker (TFW) Program or other temporary work permit programs.

Enter "0" if this business did not have employees in one of the occupation types.

  • Number of Canadian citizens and permanent residents  
    • Deck officers:
      e.g., captains, chief officers, second or third officers
    • Engineering officers:
      e.g., chief engineers, second or third engineers
    • Deck crew:
      e.g., seafarers
    • Engine crew:
      e.g., oilers, motor persons, wipers, electricians
    • Stewards and catering:
      e.g., cooks, stewards
    • Dock and warehouse:
      e.g., longshorepersons, cargo handlers, forklift operators
    • Office and administration:
      e.g., shipping clerks, logistics coordinators, port agents
    • Other:
      e.g., pilots, tug operators, compliance or environmental officers, customer service agents, clerks, pursers, attendants, industrial electricians, trainees
    • Total number of employees:
  • Number of non-permanent residents 
    • Deck officers:
      e.g., captains, chief officers, second or third officers
    • Engineering officers:
      e.g., chief engineers, second or third engineers
    • Deck crew:
      e.g., seafarers
    • Engine crew:
      e.g., oilers, motor persons, wipers, electricians
    • Stewards and catering:
      e.g., cooks, stewards
    • Dock and warehouse:
      e.g., longshorepersons, cargo handlers, forklift operators
    • Office and administration:
      e.g., shipping clerks, logistics coordinators, port agents
    • Other:
      e.g., pilots, tug operators, compliance or environmental officers, customer service agents, clerks, pursers, attendants, industrial electricians, trainees
    • Total number of employees:
  • Total number of employees in each occupation
    • Deck officers:
      e.g., captains, chief officers, second or third officers
    • Engineering officers:
      e.g., chief engineers, second or third engineers
    • Deck crew:
      e.g., seafarers
    • Engine crew:
      e.g., oilers, motor persons, wipers, electricians
    • Stewards and catering:
      e.g., cooks, stewards
    • Dock and warehouse:
      e.g., longshorepersons, cargo handlers, forklift operators
    • Office and administration:
      e.g., shipping clerks, logistics coordinators, port agents
    • Other:
      e.g., pilots, tug operators, compliance or environmental officers, customer service agents, clerks, pursers, attendants, industrial electricians, trainees
    • Total number of employees:

Flow condition: If "number of Canadian citizens and permanent residence" or "number of non-permanent residents" are greater than 0, go to Q24. Otherwise, go to Q25. 

24. For the employees reported in the "other" category in question 23, please specify the other type of occupation.

  • Other occupations of the Canadian citizens and permanent residents:
  • Other occupations of the non-permanent residents:

Flow condition: If Q7 is equal to or greater than $6,000,000 or blank, go to Q25. Otherwise, go to Q26. 

25. As of this business's peak season for the fiscal year ending in 2025/2026, was this business experiencing labour shortages or job vacancies?

Labour shortages: Difficulties finding qualified workers.

Job vacancies: Unfilled positions.

Select all that apply.

  • Labour shortages
    • Please select the occupations in which this business was experiencing labour shortages.
      Labour shortages: Difficulties finding qualified workers.
      Select all that apply.
      • Deck officers
        e.g., captains, chief officers, second or third officers
      • Engineering officers
        e.g., chief engineers, second or third engineers
      • Deck crew
        e.g., seafarers
      • Engine crew
        e.g., oilers, motor persons, wipers, electricians
      • Stewards or catering
        e.g., cooks, stewards
      • Dock and warehouse
        e.g., longshorepersons, cargo handlers, forklift operators
      • Office and administration
        e.g., shipping clerks, logistics coordinators, port agents
      • Other occupations
        e.g., pilots, tug operators, compliance or environmental officers, customer service agents, clerks, pursers, attendants, industrial electricians, trainees

        • Specify the other occupations:

        OR

      • None of the above
  • Job vacancies

    • Please select the occupations in which this business was experiencing job vacancies.
      Job vacancies: Unfilled positions. 
      Select all that apply.
      • Deck officers
        e.g., captains, chief officers, second or third officers
      • Engineering officers
        e.g., chief engineers, second or third engineers
      • Deck crew
        e.g., seafarers
      • Engine crew
        e.g., oilers, motor persons, wipers, electricians
      • Stewards or catering
        e.g., cooks, stewards
      • Dock and warehouse
        e.g., longshorepersons, cargo handlers, forklift operators
      • Office and administration
        e.g., shipping clerks, logistics coordinators, port agents
      • Other occupations
        e.g., pilots, tug operators, compliance or environmental officers, customer service agents, clerks, pursers, attendants, industrial electricians, trainees

        • Specify the other occupations:

        OR

      • None of the above

    OR

  • This business did not experience labour shortages or job vacancies

Flow condition: If Q13 is "commodities" or "cargo or freight", go to Q26. Otherwise, go to Q28.

Commodities, cargo and freight transported

26. For the fiscal year ending in 2025/2026, please select all types of commodities, cargo or freight that this business transported. 

Commodities: Basic raw materials or bulk goods, usually transported in large quantities. These include a wide range of products, such as crude oil, natural gas, coal, iron ore, grains, chemicals and other bulk goods. These goods are usually transported in large quantities using specialized vessels.

Cargo or freight: Goods or freight, used as a general term, often regarding commercial inventory, can include any type of product or good, such as packaged goods, manufactured products, machinery and containers.

Select all that apply.

  • Containerized freight
  • Dry bulk cargo
  • Liquid bulk cargo
  • Project or breakbulk cargo
  • General cargo
  • Other types of commodities, cargo or freight
    • Specify the other types of commodities, cargo or freight transported:

Display condition: Only types of commodities, cargo or freight selected in Q26 are displayed in Q27. If no types of commodities, cargo or freight was selected, display all categories in Q27.

27. For the fiscal year ending in 2025/2026, please report how much of each of the following types of commodities, cargo or freight was transported by this business. 

If exact numbers are not available, please provide your best estimate.

  • Please report the total twenty-foot equivalent units (TEUs) of containerized freight transported by this business.
    • TEUs of containerized freight transported:
      OR
    • Don't know
  • Please report the total tonnage of containerized freight transported by this business.
    • Tonnage of containerized freight transported:
      OR
    • Don't know
  • Please report the total tonnage of dry bulk cargo transported by this business.
    • Tonnage of dry bulk cargo transported:
      OR
    • Don't know
  • Please report the total tonnage of liquid bulk cargo transported by this business.
    • Tonnage of liquid bulk cargo transported:
      OR
    • Don't know
  • Please report the total tonnage of project or breakbulk cargo transported by this business.
    • Tonnage of project or breakbulk cargo transported:
      OR
    • Don't know
  • Please report the total tonnage of general cargo transported by this business.
    • Tonnage of general cargo transported:
      OR
    • Don't know
  • Please report the total tonnage of other types of commodities, cargo or freight transported by this business.
    • Tonnage of commodities, cargo or freight transported:
      OR
    • Don't know

Flow condition: If "Passenger or vehicles" is selected in Q13, go to Q28. Otherwise, go to Q30. 

Ferry and passenger services 

28. For the fiscal year ending in 2025/2026, please indicate the types of services related to passengers and vehicles provided by this business.

Select all that apply.

  • Ferry services
    Include shuttle services.
    • Please indicate the types of ferry services that were offered by this business.
      Select all that apply.
      • Passenger and passenger vehicle ferries
        Exclude commercial vehicles.
      • Passenger and all vehicle type ferries
        Include commercial and passenger vehicle roll-on-roll-off ferries.
      • Passenger-only ferries
        Include water taxis.
        e.g., cyclists, pedestrians
  • Passenger services
    Include day or overnight cruises and sightseeing vessels.
    Exclude ferry services.
  • Other types of services

    • Specify the other types of passenger and vehicle transportation services provided:

    OR

  • None of the above

Flow condition: If Q7 is equal to or greater than $6,000,000 or blank and "Passenger or vehicles" is selected in Q13 and "none of the above" was NOT selected in Q28, go to Q29. Otherwise go to Q30.

Display condition: Only services related to passengers and vehicles selected in Q28 are displayed in Q29. If no type of services related to passengers and vehicles was selected in Q28, display "Ferry services", "Passenger services", and "Other types of services" in Q29.

29. For the fiscal year ending in 2025/2026, please report the number of tickets sold and the number of trips related to ferry and passenger services provided by this business.

Ticket: A ticket is a legal document or electronic record that confirms payment and entitles a person or entity to transport between specified locations.

Trip: A trip starts with the embarkation of ticket holders and ends when those ticket holders disembark the vessel. In the case of passenger services, in-transit stops are not considered disembarkation. Therefore, the final disembarkation point is considered the end of the trip. 

If exact numbers are not available, please provide your best estimate.

  • Number of tickets sold
    • Ferry services:
      Include shuttle services.
    • Passenger and passenger vehicle ferries:
      Exclude commercial vehicles.
    • Passenger and all vehicle type ferries:
      Include commercial and passenger vehicle roll-on-roll-off ferries.
    • Passenger-only ferries:
      Include water taxis.
      e.g., cyclists, pedestrians
    • Passenger services:
      Include day or overnight cruises and sightseeing vessels.
      Exclude ferry services.
    • Other types of services:
    • Total:
  • Number of trips
    • Ferry services:
      Include shuttle services.
    • Passenger and passenger vehicle ferries:
      Exclude commercial vehicles.
    • Passenger and all vehicle type ferries:
      Include commercial and passenger vehicle roll-on-roll-off ferries.
    • Passenger-only ferries:
      e.g., cyclists, pedestrians
    • Passenger services:
      Include day or overnight cruises and sightseeing vessels.
      Exclude ferry services.
    • Other types of services:
    • Total: 

Obstacles

30. Please indicate to what extent this business experienced each of the following obstacles during its fiscal year ending in 2025/2026.

  • Drayage scheduling uncertainty
    Drayage: The short-distance, truck-based transport of shipping containers and cargo, usually connecting ports, rail yards or warehouses within the same urban area.
    • Not an obstacle
    • Minor obstacle
    • Moderate obstacle
    • Major obstacle
    • Don't know
  • Seafarer shortages
    • Not an obstacle
    • Minor obstacle
    • Moderate obstacle
    • Major obstacle
    • Don't know
  • Labour challenges at ports or terminals
    • Not an obstacle
    • Minor obstacle
    • Moderate obstacle
    • Major obstacle
    • Don't know
  • Delays because of regulatory requirements
    e.g., inspection, permits
    • Not an obstacle
    • Minor obstacle
    • Moderate obstacle
    • Major obstacle
    • Don't know
  • Delays at ports because of other factors
    • Not an obstacle
    • Minor obstacle
    • Moderate obstacle
    • Major obstacle
    • Don't know
  • Supply chain interruptions
    • Not an obstacle
    • Minor obstacle
    • Moderate obstacle
    • Major obstacle
    • Don't know
  • Economic uncertainty and inflation
    • Not an obstacle
    • Minor obstacle
    • Moderate obstacle
    • Major obstacle
    • Don't know
  • Irregular water level
    • Not an obstacle
    • Minor obstacle
    • Moderate obstacle
    • Major obstacle
    • Don't know
  • Weather-related cancellations
    • Not an obstacle
    • Minor obstacle
    • Moderate obstacle
    • Major obstacle
    • Don't know
  • Extreme weather events
    • Not an obstacle
    • Minor obstacle
    • Moderate obstacle
    • Major obstacle
    • Don't know
  • Other
    • Not an obstacle
    • Minor obstacle
    • Moderate obstacle
    • Major obstacle
    • Don't know

Government data presentation on a System of National Accounts basis compared to the Government Finance Statistics program

The annual Government Finance Statistics (GFS) program is a principal data source for the estimation of the government sector on a System of National Accounts (SNA) basis. However, there are key differences between these two programs in how they compile their government sector estimates. This note highlights some of the notable differences between SNA and GFS methodologies, concepts, and coverage.

Within the SNA, there are two primary programs that release data on the government sector: the Income and Expenditure Accounts (IEA) and the Financial and Wealth Accounts (FWA). Estimates within the IEA include revenues and expenditures within the GDP and current and capital accounts. The FWA starts with the capital account from IEA and tracks the financial flows for the government sector through the financial account and other change in assets account, ending with positions in the balance sheet for assets and liabilities.

The sequence of accounts within the SNA are fully consistent (within and across sectors) and balanced, and include transactions with residents and non-residents (outside Canada). As such, some of the differences noted below are to maintain the consistency within the sequence. The GFS is also a consistent set of accounts but with a narrower focus on the accounting consistency within government sectors.

Key differences between the SNA and the GFS

Fiscal year versus calendar year

Generally, the GFS data are on a fiscal year (i.e., March 31st year-end), whereas the SNA is on a calendar year (i.e., December 31st year-end). As a result, the fiscal year data from the GFS must be 'calendarized' to be incorporated into the SNA. For Federal government, the receipt of quarterly data facilitates integration, while in other instances, only annual fiscal data is available.

Accrual accounting

The GFS is based on fiscal year accrual accounting. When this data is integrated into the quarterly accounts, the accrual adjustments must be distributed to better reflect quarterly economic activity on a calendar basis. This is primarily an issue for the provincial/territorial administration subsector.

Year-end adjustments

In the GFS program, reporting data from government entities can include fiscal year-end adjustments. These year-end adjustments can perturb the estimates of economic growth in the SNA accounts, so these adjustments must first be spread through the four quarters of the fiscal year to align to fiscal year annual totals and then the calendarization process is applied as mentioned above.

Intergovernmental transfers

The SNA primarily uses counterparty information for transactions, that is, recording the amounts paid by a government entity as the receipts of that counterparty sector, whether it is government or non-government. This ensures internal bi-directional consistency for these flows. The GFS program articulates distinctly what is reported by the government making the transfer and the government receiving the transfer. For the GFS, when two sides of a transfer do not match between payer and recipient, an adjustment is made to 'Other revenues' and 'Other expenditures' so that the total balances of net lending/borrowing are consistent, but the transfers to and from will not necessarily align.

Estimation of capital investment, consumption of fixed capital, and stock of fixed capital

Conceptual differences and timeliness sometimes preclude the use of GFS source data for the estimate of capital investment within the SNA. In general, for federal government capital investment, the SNA is aligned with the GFS source data. For other government sectors, the capital investment estimate within the IEA is from the Annual Capital and Repair Expenditures Survey and may be adjusted with the GFS source data. This capital investment subsequently flows into the Stock and Consumption of Fixed Capital program (SCFC) and the FWA. The final GFS estimates also incorporate this capital investment data. Similarly, the SCFC provides estimates of the consumption of fixed capital (CFC) and stocks of fixed capital assets that are subsequently incorporated into the IEA, FWA and GFS, where applicable. Altogether, this ensures full consistency within the sequence.

The capital stock and CFC (also known as depreciation) within the SCFC is an economic measure of available capital in use in production processes and the associated economic depreciation of this capital. It is developed using the flow of capital investment from the IEA and is estimated on a replacement cost basis using a geometric depreciation method and specific service lives by asset. As a result, it differs from the asset and deprecation values that would be provided according to public sector and business accounting principles

Compensation of employees for government sector

Within the SNA, the compensation of employees for the general government and government sub-sectors is estimated using a similar methodology to the market sector, that is using administrative data, specifically T4 information from Canada Revenue Agency.  This administrative data is supplemented with additional data from the Survey of Employment, Payroll and Hours, Pension Plans in Canada, and from Employment and Social Development Canada. This ensures full consistency within the SNA. The GFS uses wages as reported in the government source data, which may differ from the SNA given the different sources.

Treatment of corporate income tax

In the IEA, the treatment of corporate incomes taxes aligns to the corporations' accrual perspective. This means that corporate reporting on income taxes paid are used to replace the GFS-based corporate income tax receipts of government, which may reflect more of a cash-basis perspective. This ensures consistency between both payers and recipients. The GFS replaces federal corporate income tax receipts with this corporate data but not the receipts of provincial and territorial governments. In both programs, GFS data is used for Quebec and Alberta to aid in the allocation of total provincial and territorial corporate income tax receipts.

Financial services

In the IEA, there are certain financial services that must be measured implicitly to derive an output. For example, the margin between what deposit-taking institutions earn on their loan assets versus what they pay on their deposit liabilities is considered an output of these entities. To ensure that this output aligns to all uses such as final demand, there are adjustments made to impute these expenditures by sector, including government. The GFS does not explicitly incorporate these expenses.

Indigenous general governments

In the IEA and FWA, Indigenous general governments is a distinct sub-sector of general governments. The GFS does not currently articulate this sector.

Bond liabilities

Within the FWA, data on government bond liabilities are taken from Canada's securities statistics program instead of the GFS as the data is timelier, and this practice maintains consistency within the sequence of the accounts for both issuer and debtor perspectives.

Consolidation

The FWA presents the general government sectors on an unconsolidated basis; this means that the debt securities and loan assets of one level of government corresponding to the liabilities of another government sector are shown gross. The GFS presents information on both a consolidated and unconsolidated basis (i.e., a statement of operations and balance sheet). A specific example of consolidation involves the social security fund sector's holdings of government debt. The GFS may consolidate these holdings and remove both asset and liability at the level of general government sector, whereas these will be shown gross in the FWA. However, the FWA publishes from-whom-to-whom estimates that allow users to produce consolidated estimates as needed.

Gross versus net loans

In the FWA, loans are presented on a gross basis versus net of allowances (or expected credit losses) while in the GFS, loans are presented net of allowances.

Pension entitlement estimates

In the FWA, pension entitlements are measured using pension plan and pension fund information to measure the accrued entitlement benefit. These estimates differ from GFS, which uses pension entitlements as presented according to public sector accounting standards.

Seasonal adjustment

This is unique to the quarterly IEA in which the government estimates are seasonally adjusted, whereas the quarterly FWA are presented on a non-seasonally adjusted basis.

Published information on the government sector

Income and expenditure accounts, quarterly

Taxes less subsidies, government final expenditure, government capital investment, current and capital accounts for general government and sub-sectors

Financial and wealth accounts, quarterly

Government assets and liabilities, non-financial and financial, government net worth, for general government and sub-sectors

Provincial-territorial Economic Accounts, annual

Government revenue, expenditure, and budgetary balance, by region

Government Finance Statistics, quarterly

GFS quarterly data are derived by mapping the quarterly SNA data to GFS standards and conventions

Consolidated Canadian Government Finance Statistics, annual

Government and sub-sector revenues, expenditures and financial transactions

User Guide: Canadian System of Macroeconomic Accounts

Labour Market Indicators - September 2026

In September 2026, questions measuring the Labour Market Indicators were added to the Labour Force Survey as a supplement.
Questionnaire flow within the collection application is controlled dynamically based on responses provided throughout the survey. Therefore, some respondents will not receive all questions, and there is a small chance that some households will not receive any questions at all. This is based on their answers to certain LFS questions.

Labour Market Indicators

ENTRY_Q01 / EQ 1 - From the following list, please select the household member that will be completing this questionnaire on behalf of the entire household.

AIG_Q01 / EQ 2 - Are you aware of Generative AI tools used for generating human-like text, images, computer code and more?

  1. Yes, I am aware and have a good understanding of their use
  2. Yes, I am aware and have some understanding of their use
  3. Yes, I am aware, but do not have a good understanding of their use
  4. No, I have never heard of them

AIG_Q02 / EQ 3 - How familiar are you with Generative AI tools in terms of how they could be applied to your current work?

  1. Familiar with Generative AI tools, but they have no applicability to your work
  2. Not familiar at all
  3. Somewhat familiar
  4. Moderately familiar
  5. Very familiar

AIG_Q03 / EQ 4 - In the last 12 months, did you use any of the following AI or automation technologies as part of your main job or business?

  1.  Generative AI tools
  2. Natural language processing
  3. Voice recognition software
  4. Machine learning
  5. Other
  6. None of the above

AIG_Q04 / EQ 5 - Currently, how often do you use Generative AI tools as part of your main job or business?

  1. Daily
  2. A few times a week
  3. A few times a month
  4. A few times a year

AIG_Q05 / EQ 6 - Currently, for what proportion of tasks do you use Generative AI tools as part of your main job or business?

  1. For almost all tasks
  2. For most tasks
  3. For some tasks
  4. For almost no tasks

AIG_Q06 / EQ 7 - Currently, how often do you use Generative AI tools outside of work?

  1. Daily
  2. A few times a week
  3. A few times a month
  4. A few times a year
  5. Never

AIG_Q07 / EQ 8 - What are the reasons why you are not using Generative AI tools as part of your main job or business?

  1. No interest
  2. Lack of access to AI tools
  3. Too difficult to integrate into your existing workflow
  4. Lack of skills or knowledge
  5. Lack of structured training from your employer
  6. No dedicated time during work hours for informal training
  7. Company or organisational policy
  8. Security, privacy or ethical concerns with using AI
  9. Few or no incentives and rewards
  10. Other
  11. Generative AI tools have no applicability to your work

Delivering trusted, modern statistics for Canadians

For over a century, Statistics Canada (StatCan) has been committed to providing high-quality, insightful, and accessible data to help Canadians better understand their country. Trust is the core currency of official statistics. In an era characterized by a rapid expansion of data sources and an insatiable thirst for information, we continually anchor our work in strict professional standards, transparency, and accountability. 

At the same time, producing official statistics has become increasingly complex. Canada's economy and society are evolving rapidly, shaped by globalization, technological change, new business models, shifting demographics, climate-related events, and the growing digital economy. Canadians expect statistics that are more timely, detailed, connected, and cost-effective—all while maintaining the highest standards of quality and trust. Meeting these expectations requires continual innovation in how official statistics are produced, without compromising the professional principles that underpin them.

Recent discussions have highlighted the universal challenges national statistical agencies face—including an increasingly complex information environment shaped by misinformation and disinformation, evolving public engagement, changing survey response dynamics, and the need to operate efficiently within current fiscal realities. We hear these perspectives and are proactively reshaping how we gather, guard, and grow our data systems to meet the expectations of Canadians today and into the future. 

Addressing changing response rates: The shift to a modern collection ecosystem

Traditional survey response rates have experienced a global downward trend over the past few decades, driving a strategic shift in how we build a more resilient statistical ecosystem. 

To maintain the high accuracy and representation that Canadians rely on, we are implementing a multi-faceted approach: 

  • An "administrative data first" approach: To reduce response burden on households and businesses, we are increasingly leveraging existing secure administrative and alternative data sources, such as tax data, municipal rolls, and land registries. By integrating these sources into our statistical programs, we can often substitute or supplement traditional survey questions. For example, household income information that was once collected directly through surveys is now largely obtained from administrative data files provided by the Canada Revenue Agency. This improves data quality while reducing the number of questions Canadians are asked to answer.
  • Responsive and sustainable collection: We are incorporating behavioural science and active monthly live testing into major programs like the Labour Force Survey (LFS). By better understanding our respondents, optimizing our digital communications, and focusing follow-up efforts on under-represented units, we are actively modernizing operations to keep our landmark surveys strong. 
  • Advanced non-response treatments: StatCan utilizes cutting-edge mathematical models and external validation data to protect against non-response bias. This ensures that even with smaller sample sizes or shifting response dynamics, the final data outputs remain robust, representative, and highly granular. 
  • Responsible AI and machine learning: To improve efficiency, enhance quality, and respond to emerging information needs, we are responsibly integrating artificial intelligence (AI) and machine learning into statistical production and analysis. Through human oversight, transparent methods, bias mitigation, and strong governance, these tools uphold the principles of official statistics while helping maintain the public trust that underpins our work.

Clarifying revisions: Precision in a fast-moving economy

In a fast-moving economy, delivering information when it matters most requires a careful balance between timeliness and ultimate completeness. StatCan publishes initial estimates using the highest-quality data available at that moment. As more complete information flows in over subsequent months—such as corporate tax updates, comprehensive trade summaries, or late survey responses—we refine those numbers. This standard methodology ensures that policymakers, businesses, and the public are equipped with immediate insights first, while valuable information received afterwards is incorporated to yield the most complete and accurate historical record possible. 

A key element of modern statistical science is the standard practice of data revisions. Revisions are not a sign of initial error; they reflect a commitment to timeliness, precision, transparency, and producing the best possible evidence. Today's economy is more dynamic and interconnected than ever, making the measurement of economic activity and unexpected economic shocks increasingly complex. As additional information becomes available, revisions ensure that Canada's economic statistics continue to reflect the most accurate picture of the economy.

Guarding privacy and fostering transparency

We recognize that the willingness of Canadians to participate in our data collection relies entirely on their confidence in our privacy frameworks. Through the Statistics Canada Trust Centre, we make our data governance visible. Every project we undertake is strictly evaluated against the pillars of legal authority, necessity, proportionality, and ethics. 

Whether we are deploying advanced machine learning tools or integrating complex datasets, we mask, anonymize, and de-identify personal data to guarantee that individual privacy is never compromised. 

Keeping standards and measurement frameworks current

Producing relevant official statistics also requires continually updating the standards and measurement frameworks that underpin them. As Canada's economy and society evolve, so too must the concepts, classifications, and statistical frameworks used to measure them. Emerging technologies, new forms of work, digital commerce, globalization, and changing social realities require ongoing methodological review to ensure that official statistics remain meaningful, internationally comparable, and reflective of Canadians' lived experiences. By regularly modernizing these foundational standards, StatCan ensures that the data used by governments, businesses, researchers, and Canadians continues to accurately represent the country we measure.

Looking to the future

Maintaining the relevance of official statistics requires continual improvement. As outlined in our 2026-27 Departmental Plan, we are working to deliver a fuller, more connected picture of Canada with significantly less response burden. By modernizing and standardizing key processes, expanding the use of integrated data sources, and preparing our data and technology environment to support advanced analytics and AI, we are ensuring that Canadian data remains a global standard for trustworthiness and public good. 

Monthly Survey of Food Services and Drinking Places: CVs for Total Sales by Geography - June 2026

CVs for Total sales by geography
GeographyMonth
202506202507202508202509202510202511202512202601202602202603202604202605202606
percentage
Canada0.050.050.060.060.080.070.090.120.10.080.110.140.12
Newfoundland and Labrador0.260.20.20.280.310.320.450.530.460.440.660.870.67
Prince Edward Island0.390.40.340.450.591.171.171.71.441.021.354.820.76
Nova Scotia0.20.170.190.240.250.60.430.380.360.720.570.620.43
New Brunswick0.240.190.210.350.390.820.360.470.410.970.570.60.42
Quebec0.080.080.170.150.270.170.180.280.240.20.240.280.23
Ontario0.090.070.090.10.130.120.160.20.160.130.190.230.22
Manitoba0.240.230.220.340.370.590.520.690.610.690.70.70.48
Saskatchewan0.390.540.260.40.350.690.460.531.110.690.780.990.47
Alberta0.150.190.160.160.170.20.230.320.210.220.380.370.31
British Columbia0.10.160.120.120.130.170.190.250.20.20.230.290.29
Yukon Territory0.911.031.071.321.642.062.182.842.742.433.072.952.88
Northwest Territories2.511.181.291.171.292.172.342.842.62.3312.262.872.77
Nunavut2.142.6747.682.722.464.641.92.852.593.363.543.63.14

Visitor Travel Survey: AES Calibration Groups - Q1 2026

Table 1
AES Calibration Groups for American Visitors
Calibration groupsNumber of groups
Region/Province of entry by duration of stay18
Table 2
AES Calibration Groups for Overseas Visitors
Calibration groupsNumber of groups
Country of residence 24
Country of residence by duration48
Region by duration10

Eh Sayers Episode 34 - A Honeybee Trivia Showdown

Release date: August 19, 2026

Catalogue number: 45-20-0003
ISSN: 2816-2250

Eh Sayers Episode 34 - A Honeybee Trivia Showdown

Listen to "Eh Sayers" on:

Think your honeybee knowledge is as sweet as honey? Test it in this Eh Sayers trivia showdown. Discover honey production, beekeeper numbers, colony counts and the vital role bees play in our food supply.

Host

Max Zimmerman

Guests

Jacqueline Luffman, Marc Lemire, Vince Germano

Listen to audio

Eh Sayers Episode 34 - A Honeybee Trivia Showdown - Transcript

Max: Welcome to a special summer edition of Eh Sayers Trivia. Today, I've forced three of my colleagues to come compete against each other in a series of skill testing questions. Today's theme, bees. The rules are simple. I'll ask them all four questions worth one point each and one bonus question worth three points.

Whoever has the most points at the end of the show wins. What's the prize for the winner, you might ask? Absolutely nothing, except... No, really, nothing. The studio's buzzing, so grab your honey and get ready to see who comes out on top as our queen bee. Without further ado, let's meet our contestants

Jackie: I'm Jacqueline Luffman.

I am chief of publishing services and dissemination division. I've been here 29 years.

Marc: My name is Marc Lemire. I am chief of corporate communications here at Statistics Canada.

Max: All right. Welcome to the winner of the inaugural Christmas tree trivia episode of Eh Sayers. Who am I sitting in front of right now?

Please introduce yourself to all the folks for your victory lap.

Vince: I am Vince Germano, a communications officer at Statistics Canada.

Max: And how much do you know about bees and honey? On a scale of one to 10, where, where would you rank yourself?

Jackie: On a scale of one to 10, I would rank myself maybe a five.

Marc: Oh, my gosh.

Uh, let's, let's go middle of the pack to lower. So let's go with four. Four. Four.

Max: So like a seasoned bee expert.

Marc: Y- oh, yeah. Don't embarrass me. Well, I'll, I'll do my best. Thank goodness for multiple choice.

Max: Okay.

Vince: Mm. I would say probably like six

Max: All right, so we'll jump right into it here. Question number one, are you ready?

Jackie: Sure.

Vince: Yes, let's do it. I guess I just buzz in?

Max: That's... Oh, look at what he did there. Yes, sir. Okay. Number one, how many pounds of honey were produced in Canada in 2025? Multiple choice here: A, 43 million pounds of honey; B, 71 million pounds; C, 84 million pounds; or D, 117 million pounds.

Jackie: Well, this is, this is tough, and I don't know yet how many beekeepers there are or anything like that.

I like the middle. I'm gonna say 80 million pounds or whatever the 81 was.

Max: C, 84 million pounds.

Jackie: 84 million pounds. Final answer.

Max: Final answer.

Vince: Let's go with A. A, 43 million pounds, final answer?

Marc: Yes. Let's go with C, 84 million.

Max: C, 84 million, final answer?

Marc: Final answer.

Max: Correct. Yes, sir. You got it. 84 million pounds of honey was produced in Canada in 2025.

Well done.

Marc: I am off to a lucky start.

Jackie: I like middle. We're- That was my strategy.

Max: We're batting 1,000. Let's keep it up. Okay.

Jackie: All right.

Max: All right, moving on. Number two, so sales of honey rose 14.8% year over year in 2025. Ooh. What is the total dollar amount of honey sold in 2025? You got A, $241 million worth of honey; B, $356 million; C, $792 million; or D, $1.3 billion.

Vince: That's a lot of honey, some would say. Let's go with D.

Jackie: Ooh, okay. Well, if there was about 80 million pounds and generated... Well, that doesn't necessarily mean that all of it was sold, but I would imagine you have to at least... You know, it's gonna be over a dollar a pou- Well, maybe it'd be a dollar a pound. Eh, it could be more than that.

Max: I like where you're going with this.

Jackie: You see where I'm going, yeah?

Max: Absolutely. I- Yes.

I'm catching what you're putting down.

Jackie: Again, this is my reverse math here. Um, I think I'll go with B. Billion.

Marc: Wow. What was B again?

Max: B was $356 million.

Marc: That one sounds good to me.

Max: B. Locking it in?

Marc: Locking it in.

Max: The answer was A, $241 million.

Jackie: No.

Max: But that's close. Okay. You were in the ballpark. Oh, you

Jackie: know what? I was doing-

Max: Yeah. Oh, 100%. I- You were... I thought you were gonna get it bang on. Yeah. But not far off, so.

Jackie: I, I went a little high.

Max: Well- I

Marc: was, I was on the

Max: right side. Yeah, absolutely. Definitely. A

Marc: billion dollars in sales.

Max: That's- $1.3 billion is a lot.

Yeah. That's for sure.

Marc: Yeah.

Max: That's for sure.

Okay. Number three: In 2025- Mm-hmm ... the number of beekeepers in Canada rose 6.5% year over year to its highest level since the 1980s. The number of beekeepers in Canada in 2025 was almost double the number compared to a decade ago. The question is, how many beekeepers were there in Canada in 2025?

No multiple choice on this one.

Vince: Let's go with around 8,000.

Jackie: Oh, Lord. Um, y- I did read something about beekeepers recently, something we produced in th- at Stats Can.

Vince: Okay.

Jackie: So I thought there was actually, like, in the thousands. I thought it was, like, 20,000 maybe.

Marc: Okay, so it doubled from where it was in the '80s.

Max: No, it's reached its highest level since the 1980s.

Marc: Oh,

okay. Sorry.

Max: And it's doubled compared to a decade ago.

Marc: Right. Okay. Gotcha. Let's go with, uh, 15,000 beekeepers.

Max: Marc, are you a genius? Because the answer was 16,000- Really? ... 360 beekeepers.

Marc: That was a shot in the dark. I swear I did not study for this.

Max: All right, moving on.

So number four, there's two kinds of bees. There's honeybees and pollinator bees. 4/5 of all honey produced in Canada in 2025 came from the honeybees of the prairie provinces. Pollinator bees don't make as much honey, but they do make more money. So pollinator bees contribute billions of dollars annually to Canada's farm economy.

Bees are essential for pollinating many fruits and vegetables grown in Canada, including apples in Nova Scotia, blueberries in Quebec, veggies in Ontario, and cherries in British Columbia. All that being considered, almost 2/3, 64.5%, of beekeepers in Canada in 2025 were located in this province: A, Ontario, B, British Columbia, C, Quebec, D, Saskatchewan, or E, Manitoba.

Jackie: Well, even though I am originally from Winnipeg, I'm not gonna say Manitoba 'cause I don't think that's the answer. Okay. I'm gonna guess it, because it's the biggest province, Ontario.

Marc: I'm gonna go Quebec.

Max: C, Quebec, finally.

Marc: C, quebec, final answer.

Vince: Uh, let's go with D, Saskatchewan.

Max: D, Saskatchewan. The answer was B, British Columbia.

Jackie: Oh.

Vince: What?

Max: Yeah.

Jackie: Interesting.

Max: Yeah.

Jackie: Okay.

Max: Caught me off guard as well.

Jackie: But it sort of makes sense for pollinator bees, doesn't it?

Max: That's right.

So the bonus, are you ready?

Jackie: Yeah.

Max: This is the big one.

Jackie: Okay.

Max: Not for all the marbles, but for a lot of the marbles.

Jackie: Okay.

Max: All right. According to StatCan's Food Availability release-

Jackie: Mm-hmm

Max: which estimates the amount of food physically present in the country for consumption, how many kilograms of honey were available per Canadian in 2023? No multiple choice.

Jackie: Per person, okay. So our population is around 41 million.

Max: Mm-hmm.

Jackie: I would say we produced, if I recall, you said we produced lot of pounds of honey there.

So I'm going to say, kilograms you want?

Max: Kilograms of honey per person.

Jackie: I would say like two kilograms per person.

Vince: Kilograms?

Max: Mm-hmm.

Vince: I have no idea.

Max: Got to guess. Take your time.

Vince: 1,800 kilograms.

Max: 1,800 kilograms per person.

Vince: Let's just go with that.

Max: The answer is just over one kilogram per Canadian.

Vince: Oh, really?

Jackie: Really?

Max: Yeah. Great answer.

Jackie: Well, that's awesome.

Marc: Okay, now let's not have that go to air then.

Max: No, good try. Good try. 25, I mean, you're, you're in the ballpark still. I mean...

Marc: I just, I figured, yeah, I figured it would produce a lot more.

Max: Congratulations to my and your queen bee, Jacquie Luffman.

Jackie: Okay. There. That's awesome.

I do make a mean honey cake.

Max: Okay. Well...

Jackie: Yes. And you use about, you know, a full cup and a half of honey.

Max: I need to try this cake then.

Jackie: Yes. Okay. Yes. I have a very good recipe if you ever need it, so.

Max: You've been listening to Eh Sayers. Thank you to our guests Jacquie Luffman, Vince Germano and Mark Lemire. You can find this show wherever you get your podcasts. There, you can also find a French version of our show called Écoutez bien. If you like this show, please rate, review and subscribe. And as always, thanks for listening.

Statistics Canada's 2025–26 Departmental Results Report
Statistics Canada's Financial Statements, March 31, 2026

Statement of Management Responsibility Including Internal Control over Financial Reporting

Responsibility for the integrity and objectivity of the accompanying financial statements for the year ended March 31, 2026, and all information contained in these financial statements rests with the management of Statistics Canada. These financial statements have been prepared by management using the Government of Canada's accounting policies, which are based on Canadian public sector accounting standards.

Management is responsible for the integrity and objectivity of the information in these financial statements. Some of the information in the financial statements is based on management's best estimates and judgment and gives due consideration to materiality. To fulfill its accounting and reporting responsibilities, management maintains a set of accounts that provides a centralized record of the agency's financial transactions. Financial information submitted in the preparation of the Public Accounts of Canada, and included in the agency's Departmental Results Report, is consistent with these financial statements.

Management is also responsible for maintaining an effective system of internal control over financial reporting (ICFR) designed to provide reasonable assurance that financial information is reliable, that assets are safeguarded, and that transactions are properly authorized and recorded in accordance with the Financial Administration Act and other applicable legislation, regulations, authorities, and policies.

Management seeks to ensure the objectivity and integrity of data in its financial statements through careful selection, training and development of qualified staff; through organizational arrangements that provide appropriate divisions of responsibility; through communication programs aimed at ensuring that regulations, policies, standards, and managerial authorities are understood throughout the agency and through conducting an annual risk-based assessment of the effectiveness of the system of ICFR.

The system of ICFR is designed to mitigate risks to a reasonable level based on an ongoing process to identify key risks, to assess the effectiveness of associated key controls, and to make any necessary adjustments.

A risk-based assessment of the system of ICFR for the year ended March 31, 2026, was completed in accordance with the Treasury Board Policy on Financial Management and the results and action plans are summarized in the annex, which can be found at the end of the notes to these financial statements.

The effectiveness and adequacy of the agency's system of internal control is reviewed by the work of internal finance staff, who conduct periodic assessments of different areas of the agency's operations, and by the Departmental Audit Committee (DAC), who provide advice to the Chief Statistician on the adequacy and effectiveness of the agency's risk management, control and governance frameworks and processes.

The financial statements of Statistics Canada have not been audited.

Original copy signed by:

André Loranger
Chief Statistician

Ottawa, Canada
September 15, 2026

Martin Chapman
Chief Financial Officer

Ottawa, Canada
September 15, 2026

Statement of Financial Position (Unaudited)
As at March 31
(in thousands of dollars)
 

2026

2025

Liabilities

Accounts payable and accrued liabilities (note 4)

109,257

85,590

Vacation pay and compensatory leave

41,547

47,610

Deferred revenue (note 6)

424

0

Employee future benefits (note 7)

12,880

13,916

Total net liabilities

164,108

147,116

Financial assets

Due from Consolidated Revenue Fund

105,848

68,878

Accounts receivable and advances (note 8)

10,576

10,357

Total gross financial assets

116,424

79,235

Financial assets held on behalf of Government

Accounts receivable and advances (note 8)

(4,558)

(3,473)

Total financial assets held on behalf of Government

(4,558)

(3,473)

Total net financial assets

111,866

75,762

Departmental net debt

52,242

71,354

Non-financial assets

Prepaid expenses

3,860

7,918

Consumable supplies

1,568

1,479

Tangible capital assets (note 9)

111,883

122,257

Total non-financial assets

117,311

131,654

Departmental net financial position

65,069

60,300

Contractual obligations and contractual rights (note 10)

The accompanying notes form an integral part of these financial statements.

Original copy signed by:

André Loranger
Chief Statistician

Ottawa, Canada
September 15, 2026

Martin Chapman
Chief Financial Officer

Ottawa, Canada
September 15, 2026

Statement of Operations and Departmental Net Financial Position (Unaudited)
For the Year Ended March 31
(in thousands of dollars)
 

2026 Planned Results

2026 Actual

2025 Actual

Expenses

Statistical Information

1,017,091

921,116

858,895

Internal services

111,180

103,264

105,784

Total expenses

1,128,271

1,024,380

964,679

Revenues (note 5)

Special statistical services

144,300

133,806

157,020

Services to other government departments

0

158

0

Other revenues

39

14

20

Revenues earned on behalf of Government

(24,339)

(23,747)

(28,801)

Total revenues

120,000

110,231

128,239

Net cost of operations before government funding and transfers

1,008,271

914,149

836,440

Government funding and transfers

Net cash provided by Government of Canada
 

772,604

748,681

Change in due from Consolidated Revenue Fund
 

36,970

(15,903)

Services provided without charge by other federal government departments (note 11a)
 

109,215

97,362

Transfer of assets from other government departments
 

129

(116)

Net cost (net results) of operations after government funding and transfers


(4,769)

6,416

Departmental net financial position - Beginning of year


60,300

66,716

Departmental net financial position - End of year


65,069

60,300

Segmented information (note 12)

The accompanying notes form an integral part of these financial statements.

Statement of Change in Departmental Net Debt (Unaudited)
For the Year Ended March 31
(in thousands of dollars)
 

2026 Actual

2025 Actual

Net cost (net result) of operations after government funding and transfers

(4,769)

6,416

Change due to tangible capital assets

Acquisition of tangible capital assets (note 9)

17,225

20,813

Amortization of tangible capital assets (note 9)

(27,374)

(28,609)

Net loss on disposal/write-off of tangible capital assets including adjustments

(225)

(1,569)

Total change due to tangible capital assets

(10,374)

(9,365)

Change due to consumable supplies

89

(123)

Change due to prepaid expenses

(4,058)

2,791

Increase (decrease) in departmental net debt

(19,112)

(281)

Departmental net debt - Beginning of year

71,354

71,635

Departmental net debt - End of year

52,242

71,354

Statement of Cash Flows (Unaudited)
For the Year Ended March 31
(in thousands of dollars)
 

2026

2025

Operating activities

Net cost of operations before government funding and transfers

914,149

836,440

Non-cash items:
Amortization of tangible capital assets (note 9)

(27,374)

(28,609)

Net loss on disposal/write-off of tangible capital assets including adjustments

(225)

(1,569)

Services provided without charge by other federal government departments (note 11a)

(109,215)

(97,362)

Transfer of assets to other federal government departments

(129)

116

Variations in Statement of Financial Position:
Increase (decrease) in accounts receivable and advances

(866)

244

Increase (decrease) in prepaid expenses

(4,058)

2,791

Increase (decrease) in consumable supplies

89

(123)

Decrease (increase) in accounts payable and accrued liabilities

(23,667)

15,154

Decrease (increase) in vacation pay and compensatory leave

6,063

1,253

Decrease (increase) in deferred revenue

(424)

0

Decrease (increase) in employee future benefits

1,036

(467)

Cash used in operating activities

755,379

727,868

Capital investing activities

Acquisitions of tangible capital assets (note 9)

17,225

20,813

Cash used in capital investing activities

17,225

20,813

Net cash provided by Government of Canada

772,604

748,681

The accompanying notes form an integral part of these financial statements.

Notes to the Financial Statements (Unaudited) For the Year Ended March 31

1. Authority and objectives

Statistics Canada (the agency) was established in 1918, pursuant to the Statistics Act. The agency received full departmental status by order-in-council in 1965.

The agency is a division of the public service named in Schedule I.1 of the Financial Administration Act. The minister responsible for Statistics Canada is the Minister of Innovation, Science and Economic Development, who represents the agency in Parliament and in Cabinet.

The agency's mandate derives primarily from the Statistics Act. The act requires the agency — under the direction of the minister — to collect, compile, analyze, and publish statistical information on the economic, social, and general conditions of the country and its citizens. Statistics Canada has a mandate to coordinate and manage the country's statistical system.

The agency's mandate has two primary objectives:

  • Provide statistical information and analysis of the economic and social structure and functioning of Canadian society as a basis for the development, operation and evaluation of public policies and programs. This information is used for public and private decision-making, and for the general benefit of all Canadians.
  • Promote the quality, coherence, and international comparability of Canada's statistics through collaboration with other federal departments and agencies, with the provinces and territories, and in accordance with sound scientific standards and practices.

The agency reports on the two core responsibilities described below.

Statistical information - The agency has a responsibility to produce objective high-quality statistical information for the whole of Canada. The statistical information produced relates to the commercial, industrial, financial, social, economic, environmental, and general activities and conditions of the people of Canada.

Internal services - Internal services are groups of related activities and resources that are administered to support the needs of programs and other corporate obligations of an organization.

2. Summary of significant accounting policies

These financial statements are prepared using the agency's accounting policies stated below, which are based on Canadian public sector accounting standards. The presentation and results using the stated accounting policies do not result in any significant differences from Canadian public sector accounting standards.

The significant accounting policies are as follows:

(a) Parliamentary authorities

The agency is financed by the Government of Canada through Parliamentary authorities. Financial reporting of authorities provided to the agency do not parallel financial reporting according to generally accepted accounting principles since authorities are primarily based on cash flow requirements. Consequently, items recognized in the Statement of Operations and Departmental Net Financial Position and in the Statement of Financial Position are not necessarily the same as those provided through authorities from Parliament. Note 3 provides a reconciliation between the bases of reporting. The planned results amounts in the "Expenses" and "Revenues" sections of the Statement of Operations and Departmental Net Financial Position are the amounts reported in the Future-oriented Statement of Operations included in the 2025-26 Departmental Plan. Planned results are not presented in the "Government funding and transfers" section of the Statement of Operations and Departmental Net Financial Position and in the Statement of Change in Departmental Net Debt because these amounts were not included in the 2025-26 Departmental Plan.

(b) Net cash provided by Government

The agency operates within the Consolidated Revenue Fund (CRF), which is administered by the Receiver General for Canada. All cash received by the agency is deposited into the CRF, and all cash disbursements made by the agency are paid from the CRF. The net cash provided by the Government is the difference between all cash receipts and all cash disbursements, including transactions between departments of the Government.

(c) Amounts due from or to the CRF

Amounts due from or to the CRF are the result of timing differences at year-end between when a transaction affects authorities and when it is processed through the CRF. Amounts due from the CRF represent the net amount of cash that the agency is entitled to draw from the CRF without further authorities to discharge its liabilities.

(d) Revenues and deferred revenues

Revenues are comprised of revenues earned from non-tax sources. They include exchange transactions where goods or services are provided for consideration where a performance obligation exists, and non-exchange transactions where no performance obligations exist to provide a good or service. These transactions can be recurring or non-recurring in nature. Recurring transactions are viewed as ongoing, routine activities that form part of the normal course of operations and can be used to indicate if they can be reasonably expected to be earned again in future years.

Deferred revenue consists of amounts received in advance of the delivery of goods and rendering of services that will be recognized as revenue in a subsequent fiscal year as it is earned. Other revenues are recognized in the period the event giving rise to the revenues occurred.

Revenues that are non-respendable are not available to discharge the department's liabilities. While the chief statistician is expected to maintain accounting control, he or she has no authority regarding the disposition of non-respendable revenues. As a result, non-respendable revenues are earned on behalf of the Government of Canada and are therefore presented as a reduction of the entity's gross revenues. Revenues earned on behalf of Government consist of the sale of services and gains on the sale of assets. These are recognized when earned.

(e) Expenses

  • Transfer payments are recorded as an expense in the year the transfer is authorized, and all eligibility criteria have been met by the recipient.
  • Vacation pay and compensatory leave are accrued as the benefits are earned by employees under their respective terms of employment.
  • Services provided without charge by other government departments for accommodation, employer contributions to the health and dental insurance plans, and workers' compensation are recorded as operating expenses at their carrying value.

(f) Employee future benefits

  1. Pension benefits — Eligible employees participate in the Public Service Pension Plan, a multi-employer pension plan administered by the Government. The agency's contributions to the Plan are charged to expenses in the year incurred and represent the total departmental obligation to the Plan. The agency's responsibility with regard to the Plan is limited to its contributions. Actuarial surpluses or deficiencies are recognized in the financial statements of the Government of Canada, as the Plan's sponsor.
  2. Severance benefits — The accumulation of severance benefits for voluntary departures ceased for applicable employee groups. The remaining obligation for employees who did not withdraw benefits is calculated using information derived from the results of the actuarially determined liability for employee severance benefits for the Government as a whole.

(g) Financial Instruments

A contract establishing a financial instrument creates, at its inception, rights, and obligations to receive or deliver economic benefits. The financial assets and financial liabilities portray these rights and obligations in the financial statements. The Department recognizes a financial instrument when it becomes a party to a financial instrument contract.

Financial instruments consist of accounts receivable, and accounts payable and accrued liabilities. All financial assets and liabilities are recorded at cost. Any associated transaction costs are added to the carrying value upon initial recognition. When necessary, an allowance for valuation is recorded to reduce the carrying value of accounts receivable to amounts that approximate their net recoverable value.

(h) Non-financial assets

  • The costs of acquiring land, buildings, equipment, and other capital property are capitalized as tangible capital assets and, except for land, are amortized to expense over the estimated useful lives of the assets, as described in Note 9. All tangible capital assets and leasehold improvements having an initial cost of $10,000 or more are recorded at their acquisition cost. Tangible capital assets do not include immovable assets located on reserves as defined in the Indian Act, works of art, museum collection and Crown land to which no acquisition cost is attributable, and intangible assets.
  • Purchased intangibles are identifiable non-monetary economic resources without physical substance that are acquired in exchange transactions from arm's length third parties. Purchased intangibles exclude software, which is included in tangible capital assets. Commencing April 1, 2023, the cost of a purchased intangible is capitalized as an asset when the department controls the intangible and the intangible contributes to the capacity of the government to deliver services and products, generate future cash inflows or reduce cash outflows. Purchased intangible assets are amortized to expense over the estimated useful life of the assets. Prior to April 1, 2023, purchased intangibles were expensed as incurred.
  • Consumable supplies include items held for future program delivery and are not intended for resale. These supplies are recorded at the acquisition cost. If there is no longer a service potential, the supplies are valued at the lower of cost or net realizable value.

(i) Contingent liabilities

Contingent liabilities are potential liabilities which may become actual liabilities when one or more future events occur or fail to occur. If the future event is likely to occur or fail to occur, and a reasonable estimate of the loss can be made, a provision is accrued, and an expense recorded to other expenses. If the likelihood is not determinable or an amount cannot be reasonably estimated, the contingency is disclosed in the notes to the financial statements.

(j) Contingent assets

Contingent assets are possible assets which may become actual assets when one or more future events occur or fail to occur. If the future event is likely to occur or fail to occur, the contingent asset is disclosed in the notes to the financial statements.

(k) Transactions involving foreign currencies

Transactions involving foreign currencies are translated into Canadian dollar equivalents using rates of exchange in effect at the time of those transactions. Monetary assets and liabilities denominated in foreign currencies are translated into Canadian dollars using the rate of exchange in effect at March 31. The Government has elected to recognize gains and losses resulting from foreign currency translation, including those arising prior to settlement or derecognition of the financial instrument, directly on the Statement of Operations and Departmental Net Financial Position according to the activities to which they relate.

(l) Measurement uncertainty

The preparation of these financial statements requires management to make estimates and assumptions that affect the reported and disclosed amounts of assets, liabilities, revenues and expenses reported in the financial statements and accompanying notes at March 31. The estimates are based on facts and circumstances, historical experience, general economic conditions and reflect the Government's best estimate of the related amount at the end of the reporting period. The most significant items where estimates are used are the liability for employee future benefits and the useful life of tangible capital assets. Actual results could significantly differ from those estimated. Management's estimates are reviewed periodically and, as adjustments become necessary, they are recorded in the financial statements in the year they become known.

(m) Related party transactions

Related party transactions, other than inter-entity transactions, are recorded at the exchange amount. Inter-entity transactions are transactions between commonly controlled entities. Inter-entity transactions, other than restructuring transactions, are recorded on a gross basis and are measured at the carrying amount, except for the following:

  1. Services provided on a recovery basis are recognized as revenues and expenses on a gross basis and measured at the exchange amount.
  2. Certain services received on a without charge basis are recorded for departmental financial statement purposes at the carrying amount.

3. Parliamentary authorities

The agency receives most of its funding through annual parliamentary authorities. Items recognized in the Statement of Operations and Departmental Net Financial Position and the Statement of Financial Position in one year may be funded through parliamentary authorities in prior, current, or future years. Accordingly, the agency has different net results of operations for the year on a government funding basis than on an accrual accounting basis. The differences are reconciled in the following tables:

(a) Reconciliation of net cost of operations to current year authorities used

Reconciliation of net cost of operations to current year authorities used
 

2026

2025

(in thousands of dollars)

Net cost of operations before government funding and transfers

914,149

836,440

Adjustments for items affecting net cost of operations but not affecting authorities:

Amortization of tangible capital assets

(27,374)

(28,609)

Loss on disposal/write-off of tangible capital assets, including adjustments

(225)

(1,569)

Services provided without charge by other federal government departments

(109,215)

(97,362)

Decrease (increase) in vacation pay and compensatory leave

6,063

1,253

Decrease (increase) in employee future benefits

1,036

(467)

Refund of prior years' expenditures

323

840

Increase in respendable revenues

0

0

Consumption of prepaid expenses

(8,671)

(6,700)

Consumption of supplies

0

(123)

Bad debt expense

(263)

(281)

Increase (decrease) in accrued receivable

(304)

193

Adjustment to previous year disposal

34

0

Total items affecting net cost of operations but not affecting authorities

(138,596)

(132,825)

Adjustments for items not affecting net cost of operations but affecting authorities:

Acquisition of tangible capital assets

17,225

20,813

Decrease in respendable accounts receivable

(945)

(170)

Acquisition of prepaid expenses

4,614

9,493

Acquisition of consumable supplies

89

0

Increase in salary receivable

730

518

Increase in salary advances

0

4

Payments for pay equity settlement

14,419

0

Total items not affecting net cost of operations but affecting authorities

36,132

30,658

Current year authorities used

811,685

734,273

(b) Authorities provided and used

Authorities provided and used
 

2026

2025

(in thousands of dollars)

Authorities provided:

Vote 1 - Operating expenditures

754,130

679,131

Statutory amounts

102,588

96,249

Total authorities provided

856,718

775,380

Less:

Lapsed: Operating expenditures

(45,033)

(41,107)

Current year authorities used

811,685

734,273

4. Accounts payable and accrued liabilities

The following table presents details of the agency's accounts payable and accrued liabilities:

Accounts payable and accrued liabilities
 

2026

2025

(in thousands of dollars)

Accounts payable - Other federal government departments and agencies

4,304

10,096

Accounts payable - External parties

32,737

34,904

Accrued salaries and wages

72,216

40,590

Total accounts payables and accrued liabilities

109,257

85,590

5. Revenues

The department has the following major types of revenues: special statistical services, services to other government departments, miscellaneous revenues, and revenues earned on behalf of the Government. Miscellaneous revenues include gains on sales of assets, other gains on foreign exchange valuations and other fees and charges. These are recorded when performance obligations are satisfied.

(a) Disaggregated revenues

Disaggregated revenues
 

2026

2025

(in thousands of dollars)

Revenues

Special statistical services (exchange)

133,806

157,020

Services to other government departments (exchange)

158

0

Miscellaneous
Gains on sales of assets (exchange)

11

13

Gains on foreign exchange valuations (non-exchange)

3

2

Other fees and charges (exchange and non-exchange)

0

5

Total miscellaneous

14

20

Revenues earned on behalf of Government (exchange)

(23,747)

(28,801)

Total revenuesFootnote 1

110,231

128,239

Disaggregated revenues - Footnote 1

Total non-recurring revenues of $14 thousands were incurred in relation to Gains on sales of assets, Gains on foreign exchange valuations, and interest on overdue accounts receivable.

Disaggregated revenues - Return to footnote 1 referrer

6. Deferred revenue

The agency has the authority to expend revenue received during the fiscal year. Deferred revenue represents the balance at year-end of unearned revenues stemming from amounts received from external parties, which are restricted for specific statistical services. Revenue is recognized in the period in which these expenditures are incurred or in which the service is performed. Details of the transactions related to this account are as follows:

Deferred revenue
 

2026

2025

(in thousands of dollars)

Opening balance

0

0

Amount received

19,886

26,813

Revenues recognized

(19,462)

(26,813)

Net closing balance

424

0

7. Employee future benefits

(a) Pension benefits

The agency's employees participate in the Public Service Pension Plan ("the Plan"), which is sponsored and administered by the Government of Canada. Pension benefits accrue up to a maximum period of 35 years at a rate of 2 percent per year of pensionable service, times the average of the best five consecutive years of earnings. The benefits are integrated with Canada/Québec Pension Plan benefits and they are indexed to inflation.

Both the employees and the agency contribute to the cost of the Plan. Due to the amendment of the Public Service Superannuation Act following the implementation of provisions related to Economic Action Plan 2012, employee contributors have been divided into two groups – Group 1 relates to existing plan members as of December 31, 2012, and Group 2 relates to members who joined the Plan as of January 1, 2013.  Each group has a distinct contribution rate.

The 2025-26 expense amounts to $65,034 thousand ($61,726 thousand in 2024-25).  For Group 1 members, the expense represents approximately 1.01 times (1.02 times in 2024-25) the employee contributions and, for Group 2 members, approximately 1.00 times (1.00 times in 2024-25) the employee contributions.

The agency's responsibility with regard to the Plan is limited to its contributions. Actuarial surpluses or deficiencies are recognized in the Consolidated Financial Statements of the Government of Canada, as the Plan's sponsor.

(b) Severance benefits

Severance benefits provided to the agency's employees were previously based on an employee's eligibility, years of service and salary at termination of employment. However, since 2011 the accumulation of severance benefits for voluntary departures progressively ceased for substantially all employees. Employees subject to these changes were given the option to be paid the full or partial value of benefits earned to date or collect the full or remaining value of benefits upon departure from the public service. By March 31, 2018, substantially all settlements for immediate cash out were completed. Severance benefits are unfunded and, consequently, the outstanding obligation will be paid from future authorities.

The changes in the obligations during the year were as follows:

Severance benefit obligations
 

2026

2025

(in thousands of dollars)

Accrued benefit obligation - Beginning of year

13,916

13,449

Expense or adjustment for the year

10,732

1,623

Benefits paid during the year

(11,768)

(1,156)

Accrued benefit obligation - End of year

12,880

13,916

8. Accounts receivable and advances

The following table presents details of the agency's accounts receivable and advances balances:

Accounts receivable and advances
 

2026

2025

(in thousands of dollars)

Receivables - Other federal government departments and agencies

3,584

1,969

Receivables - External parties

7,333

8,892

Employees advances

483

57

Subtotal

11,400

10,918

Allowance for doubtful accounts on receivables from external parties

(824)

(561)

Gross accounts receivable and advances

10,576

10,357

Accounts receivable held on behalf of Government

(4,558)

(3,473)

Net accounts receivable and advances

6,018

6,884

The following table provides an aging analysis of accounts receivable from external parties and the associated valuation allowances used to reflect their net recoverable value:

Aging analysis of accounts receivable from external parties
 

2026

2025

(in thousands of dollars)

Accounts receivable from external parties:

Impaired

824

561

Not past due

5,401

6,730

Number of days past due
1 to 30

193

729

31 to 60

17

14

61 to 90

6

94

91 to 365

41

179

Over 365

851

585

Sub-total

7,333

8,892

Less: valuation allowance

(824)

(561)

Total

6,509

8,331

9. Tangible capital assets

Amortization of tangible capital assets is done on a straight-line basis over the estimated useful life of the asset as follows:

Amortization period of tangible capital assets

Asset class

Amortization period

Computer hardware

5 years

Computer software

5 years

Other equipment

5 years

Vehicles

7 years

Leasehold improvements

25 years

Assets under construction

Once available for use

Software under development

Once available for use

Assets under construction and software assets under development are recorded in the applicable asset class in the year that they become available for use and are not amortized until they are available for use.

Assets under construction and software assets under development

Capital Asset Class

Cost

Accumulated Amortization

Net Book Value

Opening Balance

Acquisitions

Disposals and Write-Offs

AdjustmentsAssets under construction and software assets under development - Footnote 1

Closing Balance

Opening Balance

Amortization

Disposals and Write-Offs

AdjustmentsAssets under construction and software assets under development - Footnote 1

Closing Balance

2026

2025

(in thousands of dollars)

Computer hardware

2,162

-

-

-

2,162

1,904

78

-

-

1,982

180

258

Computer software

410,349

-

(3,893)

22,737

429,193

338,258

25,029

(3,732)

-

359,555

69,638

72,091

Other equipment

4,197

362

-

-

4,559

3,092

285

-

-

3,377

1,182

1,105

Motor Vehicles

329

54

-

-

383

196

29

-

-

225

158

132

Other Vehicles

8,366

21

(18)

-

8,369

3,777

894

(18)

-

4,653

3,716

4,588

Leasehold improvements

26,428

215

-

-

26,643

14,453

1,059

-

-

15,512

11,131

11,975

Assets under construction

-

-

-

-

-

-

-

-

-

-

-

-

Software under development

32,106

16,573

-

(22,801)

25,878

-

-

-

-

-

25,878

32,108

Total

483,937

17,225

(3,911)

(64)

497,187

361,680

27,374

(3,750)

-

385,304

111,883

122,257

Assets under construction and software assets under development - Footnote 1

Included in adjustments are the following: software assets under development of $22,737 thousand that were transferred to computer software upon completion of the assets and $64 thousand that was expensed due to an adjustment of previous year capitalized software under development.

Assets under construction and software assets under development - Return to the first footnote 1 referrer

10. Contractual obligations and contractual rights

(a) Contractual obligations

The nature of the agency's activities may result in some large multi-year contracts and obligations whereby the agency will be obligated to make future payments when the services/goods are received. Significant contractual obligations that can be reasonably estimated are summarized as follows:

Contractual obligations
 

2027

2028

2029

2030

2031 and subsequent

Total

(in thousands of dollars)

Acquisition of goods and services

129,731

33,555

1

-

-

163,287

Total

129,731

33,555

1

-

-

163,287

(b) Contractual rights

The activities of the agency sometimes involve the negotiation of contracts or agreements with outside parties that result in the agency having rights to both assets and revenues in the future. They involve sales of goods and services. The agency does not have significant contractual rights to disclose as of March 31, 2026.

11. Related party transactions

The agency is related as a result of common ownership to all government departments, agencies, and Crown corporations. Related parties also include individuals who are members of key management personnel or close family members of those individuals, and entities controlled by, or under shared control of, a member of key management personnel or a close family member of that individual.

The agency enters into transactions with these entities in the normal course of business and on normal trade terms.

(a) Common services provided without charge by other federal government departments

During the year, the agency received services without charge from certain common service organizations related to accommodation, the employer's contribution to the health and dental insurance plans and workers' compensation coverage. These services provided without charge have been recorded at the carrying value in the agency's Statement of Operations and Departmental Net Financial Position as follows:

Common services provided without charge by other federal government departments
 

2026

2025

(in thousands of dollars)

Accommodation

42,308

41,184

Employer's contribution to the health and dental insurance plans

66,878

56,139

Worker's compensation

29

39

Total

109,215

97,362

The Government has centralized some of its administrative activities for efficiency, cost-effectiveness purposes and economic delivery of programs to the public. As a result, the Government uses central agencies and common service organizations so that one department performs services for all other departments and agencies without charge. The costs of these services, such as the payroll and cheque issuance services provided by Public Services and Procurement Canada and audit services provided by the Office of the Auditor General are not included in the agency's Statement of Operations and Departmental Net Financial Position.

(b) Other transactions with other federal government departments and agencies

Other transactions with other federal government departments and agencies
 

2026

2025

(in thousands of dollars)

Accounts receivable

3,584

1,969

Accounts payable

4,304

10,096

Expenses

29,052

21,564

Revenues

94,284

106,430

Expenses and revenues disclosed in (b) exclude common services provided without charge, which are already disclosed in (a).

12. Segmented information

Presentation by segment is based on the agency's core responsibilities. The presentation by segment is based on the same accounting policies as described in the Summary of significant accounting policies in note 2. The following table presents the expenses incurred and revenues generated for the main core responsibilities, by major object of expense and by major type of revenue. The segment results for the period are as follows:

Expenses incurred and revenues generated for the main core responsibilities
 

Statistical Information

Internal services

2026 Total

2025 Total

(in thousands of dollars)

Operating expenses

Salaries and employee benefits

745,988

83,030

829,018

781,384

Accommodation

38,070

4,237

42,307

41,183

Professional and special services

27,482

6,238

33,720

33,556

Transportation, communication, and postage

32,485

914

33,399

20,291

Amortization

26,642

732

27,374

28,609

Repairs and maintenance

573

210

783

1,216

Utilities, materials and supplies

3,773

819

4,592

10,665

Rentals

40,750

6,937

47,687

37,645

Information

19,378

129

19,507

9,051

Loss on disposal/write-off of tangible capital assets

143

19

162

676

Other operating expenses

(14,168)

(1)

(14,169)

403

Total operating expenses

921,116

103,264

1,024,380

964,679

Total expenses

921,116

103,264

1,024,380

964,679

Revenues

Special statistical services

133,806

-

133,806

157,020

Services to other government services

0

158

158

-

Other revenues

14

-

14

20

Revenues earned on behalf of Government

(23,747)

-

(23,747)

(28,801)

Total revenues

110,073

158

110,231

128,239

Net cost from continuing operations

811,043

103,106

914,149

836,440

Annex to the Statement of Management Responsibility Including Internal Control over Financial Reporting of Statistics Canada for Fiscal Year 2025-2026 (Unaudited)

1. Introduction

This document is attached to Statistics Canada's (StatCan) Statement of Management Responsibility Including Internal Control over Financial Reporting for the 2025-2026 fiscal year. This annex provides summary information on the measures taken by StatCan to maintain an effective system of internal control over financial reporting (ICFR), as well as information on internal control management, assessment results and related action plans.

Detailed information on the agency's authority, mandate and core responsibilities can be found in the Statistics Canada's 2026-27 Departmental Plan, Statistics Canada's 2025-26 Departmental Plan and the Statistics Canada's 2024-25 Departmental results report.

2. Departmental system of internal control over financial reporting

2.1 Internal control management

StatCan has a well-established governance and accountability structure to support departmental assessment efforts and oversight of its overall system of internal control. A departmental internal control management framework, approved by the Chief Financial Officer (CFO), is in place and comprises:

  • organizational accountability structures as they relate to internal control management to support sound financial management, including roles and responsibilities of senior managers for control management in their areas of responsibility;
  • values and ethics;
  • ongoing communication and training on the legislative and policy requirements for sound financial management and control; and
  • monitoring and regular updates on internal control management, as well as provision of related assessment results and action plans to the Chief Statistician and senior departmental management and, as applicable, to the Departmental Audit Committee (DAC).

The DAC provides advice to the Chief Statistician on the adequacy and effectiveness of the agency's risk management, control and governance frameworks and processes.

2.2 Service arrangements relevant to financial statements

StatCan relies on other organizations for processing certain transactions that are recorded in its financial statements, as follows:

2.2.1 Common service arrangements
  • Public Services and Procurement Canada (PSPC) administers the payment of salaries, the procurement of certain goods and services, and provides accommodation services;
  • Shared Services Canada (SSC) provides information technology (IT) infrastructure services;
  • The Department of Justice Canada provides legal services; and
  • The Treasury Board of Canada Secretariat (TBS) provides information on public service insurance and centrally administers payment of the employer's share of contribution toward statutory employee benefit plans.
2.2.2 Specific arrangements
  • PSPC provides StatCan with the Common Departmental Financial System platform to capture and report financial and material management transactions, as well as procurement information. 

Readers of this annex may refer to the annexes of the above-noted departments for a greater understanding of the systems of internal control over financial reporting (ICFR) related to these specific services.

3. StatCan assessment results for the 2025-2026 fiscal year

StatCan adopted an ongoing, rotational, risk-based monitoring approach to support testing of internal control over financial reporting. In 2024, StatCan updated its Internal Control over Financial Management (ICFM) Ongoing Monitoring Framework, which replaced its previous version from 2020. According to the new strategy, the ongoing monitoring cycle was extended to a five-year period, and the plan is adjusted through an annual environmental scan process.

The following table summarizes the status of the ongoing monitoring activities according to the previous fiscal year's rotational plan under ICFR and ICFM.

Progress during the 2025-2026 fiscal year

Previous fiscal year's rotational ongoing monitoring plan for current fiscal year
 

Status

Internal Controls Over Financial Reporting

Revenue

Completed as planned; remedial actions completed.

Capital Assets

Completed as planned; remedial actions started.

Information technology general controls under agency management - (Medium risk)

Completed as planned; remedial actions started.

Information technology general controls under agency management - Cloud

Completed as planned; remedial actions started.

Information technology general controls under agency management - Customer Relationship Management System (CRMS)

Completed as planned; remedial actions started.

Entity Level Controls

Completed as planned; remedial actions started.

Procurement

Design Effectiveness stage completed. Operating Effectiveness testing will conclude during 2026-2027.

Internal Controls Over Financial Management

Chief Financial Officer (CFO) Attestation

Completed as planned; remedial actions started.

Procurement

Design Effectiveness stage completed. Operating Effectiveness testing will conclude during 2026-2027.

New or significantly amended key controls are summarized in section 3.1. The areas of the departmental system of internal controls that were reviewed this fiscal year are summarized in section 3.2.

3.1 New or significantly amended key controls

In the current fiscal year, there were no significantly amended key controls in existing processes that required a reassessment.

In fiscal year 2025-2026, Statistics Canada completed the design effectiveness testing for newly implemented controls related to the Forecasting, Payroll and Benefits, and Operating Expenditures processes. These controls will require reassessment as part of ongoing monitoring activities. These controls were established to strengthen processes and ensure the availability of funds prior to approval. As part of this initiative, complementary oversight controls were introduced to enhance senior management's awareness of material disbursements before Section 32 authorization is granted.

3.2 Ongoing monitoring program

As part of its rotational ongoing monitoring plan, the agency completed its reassessment of IT General Controls (ITGCs) under medium risk, Cloud and Customer Relationship Management System (CRMS) and the financial controls within the business processes of:

  • Revenues
  • Capital Assets
  • Entity Level Controls
  • CFO Attestation of Cabinet and TB Submissions
  • Forecasting (Design Effectiveness of new controls)

Management action plans addressing the recommendations were developed by the business process owners.

4. Statistics Canada action plan for the next fiscal year (2026-2027) and subsequent fiscal years

Statistics Canada's rotational ongoing monitoring plan over the next three years is shown in the following table. The ongoing monitoring plan is based on:

  • an annual validation of high-risk processes and controls; and
  • related adjustments to the ongoing monitoring plan as required.

An annual risk assessment is conducted to validate the high-risk controls and to adjust the ongoing monitoring plan as required. Action plans from previous years will be followed up on to ensure that remedial actions have been taken.

Rotational ongoing monitoring plan

Internal Control over Financial Reporting

Key control areas

Fiscal Year 2026–2027

Fiscal Year 2027–2028

Fiscal Year 2028–2029

Entity-level controls

No

No

No

Information technology general controls under agency management

Yes

Yes

Yes

Capital assets

No

No

No

Financial close and reporting

Yes

No

Yes

Operating expenditures

No

Yes

No

Revenues

No

Yes

No

Census payroll

Yes

No

No

Payroll and benefits

Yes

No

Yes

Stage of monitoring

Internal Control over Financial Management

Key control areas

Fiscal Year 2026–2027

Fiscal Year 2027–2028

Fiscal Year 2028–2029

Budgeting

Ongoing Monitoring

Ongoing Monitoring

Ongoing Monitoring

Costing

Ongoing Monitoring

Ongoing Monitoring

Ongoing Monitoring

Forecasting

Ongoing Monitoring

Ongoing Monitoring

Ongoing Monitoring

Payroll

Ongoing Monitoring

Ongoing Monitoring

Ongoing Monitoring

CFO Attestation of Cabinet and TB Submissions

Ongoing Monitoring

Ongoing Monitoring

Ongoing Monitoring

Investment Planning

Ongoing Monitoring

Ongoing Monitoring

Ongoing Monitoring

Procurement

Operating Effectiveness

Operating Effectiveness

Ongoing Monitoring